Barrick Beats On Adjusted EPS, But Cost Creep, Flat Sequential Earnings And A Slipping IPO Temper The Quarter
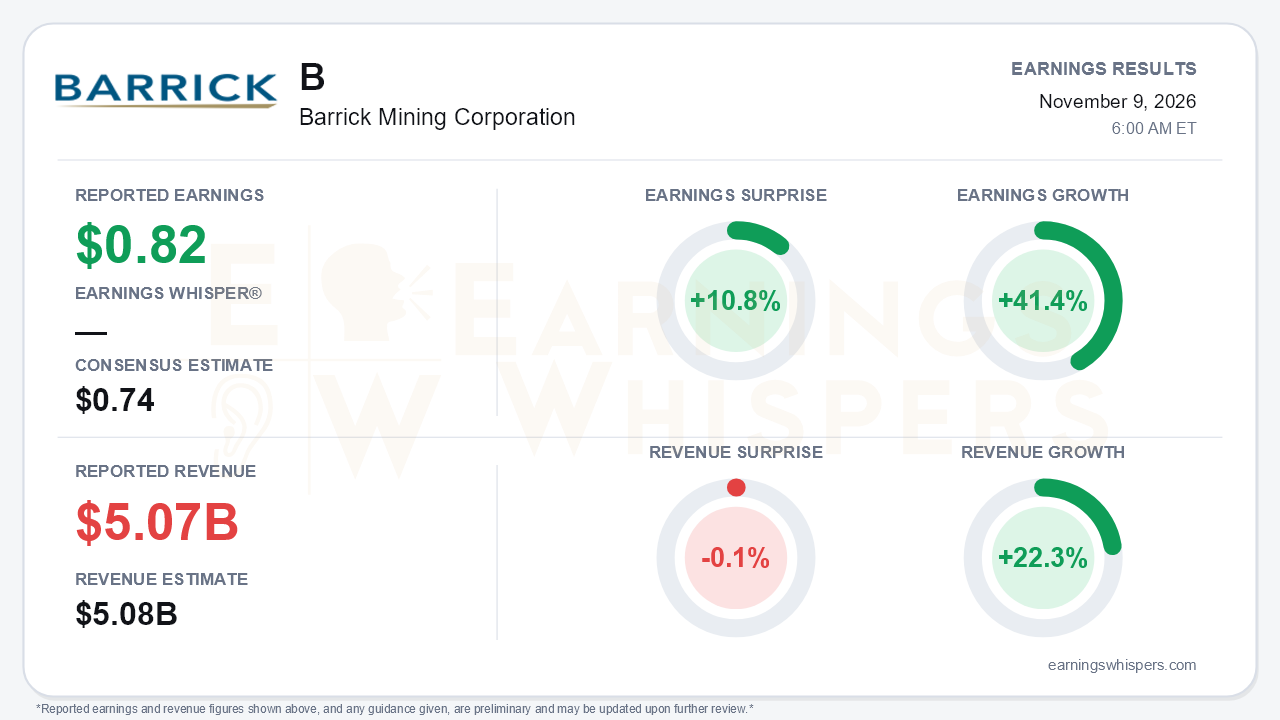
Barrick Mining Corporation (NYSE: B) reported adjusted earnings of $0.82 per share for the third quarter, beating the $0.74 consensus by 10.8% and rising 41.4% from a year ago. Revenue of $5.073 billion grew 22.3% but came in essentially in line with the $5.08 billion consensus, a 0.1% shortfall. The year-over-year comparison is strong, but the sequential picture is flatter. Adjusted EPS was unchanged from Q2's $0.82, revenue fell 4% sequentially as realized gold slipped to $4,243 per ounce from $4,417, and the 22% revenue growth rate is well below the 42% pace for the first nine months. This was a beat driven by metal prices and steady execution. It does not show earnings re-accelerating.
The quality of the quarter is mixed. GAAP net earnings were $1.32 billion, or $0.80 per share, up only 5%. The gap to adjusted results is roughly a wash: a $102 million gain on the Bambadji sale was stripped out, while $104 million of other expenses was added back, mainly retroactive royalties, penalties and interest tied to Mali's 2023 Mining Code at Loulo-Gounkoto. Costs are the bigger concern.
- Gold AISC rose to $1,911 per ounce from $1,866 in Q2 and $1,538 a year ago, pressing against the top of the $1,760–$1,950 guidance range. Lower grades, price-linked royalties, diesel and higher sustaining capital drove the increase.
- Copper production fell to 50 thousand tonnes from 56 thousand. Copper AISC jumped to $4.52 per pound, and the year-to-date $4.05 already sits above the $3.45–$3.75 guidance range.
That creates a conflict. The release says copper cost guidance is unchanged, while management on the call said copper unit costs are now expected around the top end of the range. Investors should treat copper cost guidance as effectively under pressure. Attributable EBITDA margin held at 60%, which shows that pricing is still outrunning cost inflation, but that cushion depends on gold and copper prices staying elevated.
Operationally, the gold story is improving. Production climbed to 816 thousand ounces from 796 thousand in Q2 and 719 thousand in Q1. The main contributors were:
- the Goldrush ramp-up at Cortez;
- a record quarter at Carlin's Gold Quarry roaster;
- a 16% sequential gain at Loulo-Gounkoto;
- Kibali's best quarter since late 2023.
Management indicated full-year gold output should land around the midpoint of guidance or slightly above. The weak spots remain. Extreme weather cost Veladero 17 days of downtime, drought at Porgera is extending into Q4, and North Mara's high-grade access was pushed into the fourth quarter. Attributable gold production was still 2% lower year over year. Africa is also absorbing fuel, consumables and currency pressure, and management declined to provide a 2027 cost outlook.
Cash flow and capital returns show the same tension between commitment and capacity. Attributable free cash flow recovered to $642 million from $141 million in Q2, though it was down 44% year over year. Barrick returned $1.04 billion in the quarter, including $761 million of buybacks, so distributions again exceeded attributable free cash flow. Net cash fell to $0.9 billion from $1.2 billion in Q2 and $2.4 billion in Q1. The catalyst list is long:
- an S-1 filing for the North American gold IPO;
- roughly $1.5 billion in Newmont-related Fourmile proceeds that, together with IPO proceeds, management intends to return on top of the 50% free-cash-flow top-up, pending board approval;
- a Hatch study for new Cortez processing and rail capacity;
- record Nevada exploration spending;
- a third flotation train at Pueblo Viejo;
- a review of the Andean portfolio.
Several of these items also slipped. IPO timing moved from 'by year-end' to 'end of this year or early next year,' the Fourmile prefeasibility schedule appears to have been pushed out, and the Nevada processing upgrades are a post-2030 story. Management also explicitly warned against extrapolating a strong fourth quarter into 2027.
Investors were cooling before the report. Earnings Whispers sentiment remained positive but weakened, slipping from 0.22 to 0.14. Price action was choppy. Shares have changed little since the prior report, down 1.6% from the post-report open of $41.22 to $40.56. That modest net move hides a wide range: the stock peaked at $49.14 in late August, dropped to $36.27 on October 30, and entered earnings 17.5% below the high, 11.8% above the low, and 3.2% below its 200-day moving average. The trend readings are mixed, with momentum positive but AVWAP still negative, consistent with a stock rebounding off its lows without reclaiming its post-August footing.
The bottom line is that Barrick delivered a clean adjusted beat and a fourth straight quarter of rising gold output, but the underlying trend is less flattering than the 41% growth headline suggests. Earnings were flat sequentially, unit costs are migrating to or beyond the top of guidance, net cash is shrinking as returns outpace attributable free cash flow, and the IPO and Fourmile timelines have slipped. The capital-return and asset-monetization catalysts are real, but their timing is less certain, and the earnings base remains heavily dependent on metal prices holding up.
Read our earnings preview for Barrick Mining Corporation: https://www.earningswhispers.com/article/B/22552
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 5 hours | |
| 7 hours | |
| 7 hours | |
| 8 hours | |
| 8 hours | |
| 8 hours | |
| 9 hours | |
| 10 hours | |
| Nov-04 | |
| Nov-02 | |
| Oct-22 | |
| Oct-09 |
