ADC Therapeutics Must Show Lotus 7 Can Carry The Story After Lotus 5's FDA Setback
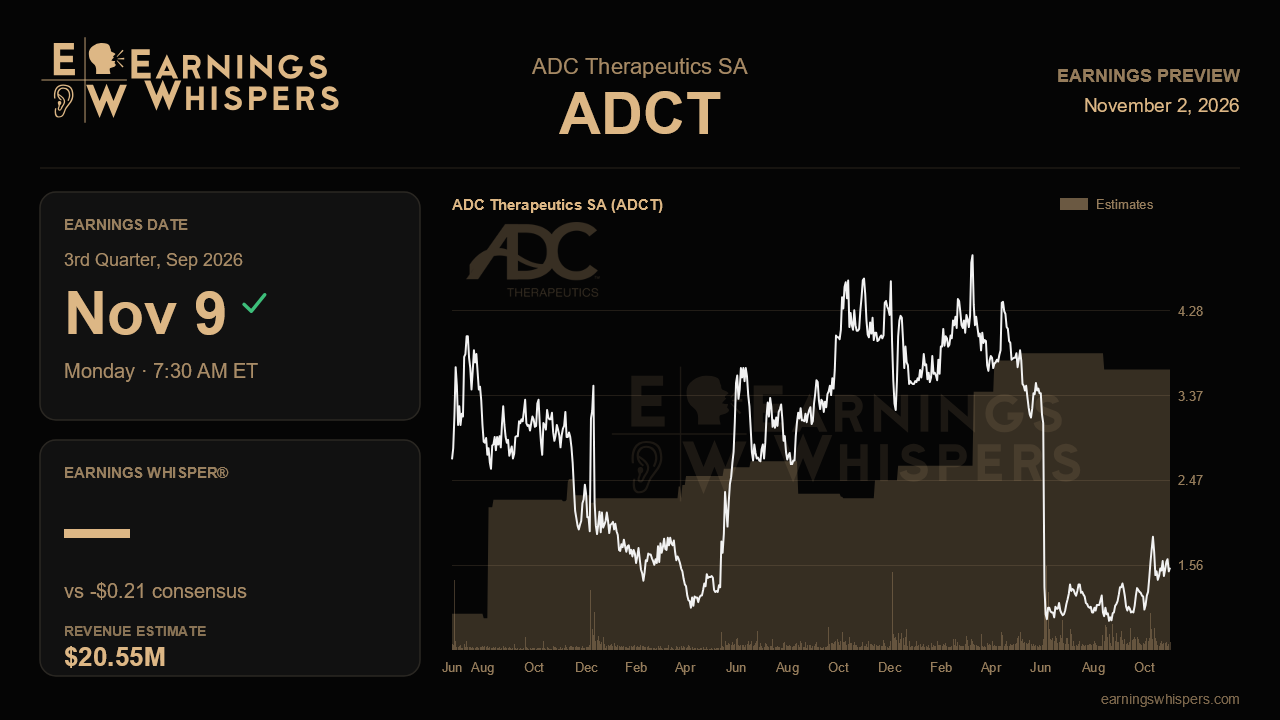
ADC Therapeutics heads into its third-quarter report with a stock that has rallied hard off the wreckage of its last one. Shares have climbed 43% since the previous release, while the S&P 500 slipped 2.5%. That came after a quarter in which the company's main 2027 growth driver ran into a regulatory wall. The rebound looks less like renewed confidence than a bounce from a washed-out low. This report is the first real chance to show whether the pivot from Lotus 5 to Lotus 7 is a strategy or just a retreat.
The Street expects a loss of $0.21 per share on revenue of $20.6 million. That revenue figure would be about 25% above the $16.4 million of a year ago, which sounds healthy until you look at the recent trend. Product revenue slipped to $18.6 million last quarter from $20.0 million the quarter before and $22.3 million two quarters earlier. Hitting consensus therefore requires a sequential reacceleration of roughly 7% from last quarter's total. Without fresh guidance, that number is the clearest test of whether Zynlanta's current monotherapy business is stable or still sliding. The loss estimate is also notably wider than last quarter's $0.11, though still an improvement on the $0.30 loss a year ago. That suggests analysts are not assuming last quarter's narrow loss was the new run rate.
The cost side is where management has the most control and the most to prove. Adjusted operating expenses fell 22% year over year to $37.2 million last quarter. The June restructuring, which cut about 17% of the workforce, was framed as delivering roughly $10 million in additional annualized savings. A full quarter of those savings should now be visible. If spending creeps back up, or if cost of goods keeps climbing as staff shift into commercial manufacturing, the discipline story weakens. Cash fell to $219.1 million from $231 million. Management says that funds operations into 2028, and burn this quarter will show whether that claim has a cushion.
The bigger questions are regulatory. After Lotus 5 met its progression-free survival endpoint, the FDA raised substantial concerns about benefit-risk and whether clinical benefit could be verified. Fatal infections in the trial, mostly bacterial, deepened those concerns. The company withdrew its confident timeline for a year-end sBLA and mid-2027 approval and offered no replacement. The previously cited $600 million to $1 billion peak revenue framing also vanished. Any concrete update on a path forward for Lotus 5 would help. So would reassurance that the confirmatory risk does not spill onto Zynlanta's existing accelerated approval. Continued silence would confirm the market's darker reading.
Lotus 7, the combination of Zynlanta with glofitamab, is now carrying the narrative. Enrollment of 100 patients at the 150 mcg/kg dose is complete, and earlier data showed a 90% response rate with 78% complete responses. Management called it the most compelling combination data it has produced. It promised a breakthrough designation filing this year and an assessment of a Phase 3 trial. Confirmation that the filing went in, signs of a decision on Phase 3 design, and evidence that its different infection prophylaxis is avoiding Lotus 5's safety problems would validate the pivot. The same goes for progress on breakthrough filings in marginal zone and follicular lymphoma.
Sentiment has soured, with bearish readings rising to 67.4% from 53.0% ahead of the last report, even as the stock rallied. At $1.53, shares sit in the upper half of their post-earnings range of $0.94 to $1.87. That is still far below the 200-day average of $2.49 and a fraction of last quarter's $4.13 high. The quarterly numbers matter less than whether management can replace a lost catalyst with a credible new one. A clear Lotus 7 regulatory plan plus visible cost savings keeps the story alive. Vague answers on both fronts leave the rally exposed.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 8 hours | |
| Oct-29 | |
| Oct-08 | |
| Sep-21 | |
| Sep-03 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Aug-06 | |
| Jul-06 | |
| Jul-01 | |
| Jun-30 | |
| Jun-24 | |
| Jun-24 |
