Delcath Faces A Seasonality Test As Street Braces For Sequential Revenue Dip And Loss
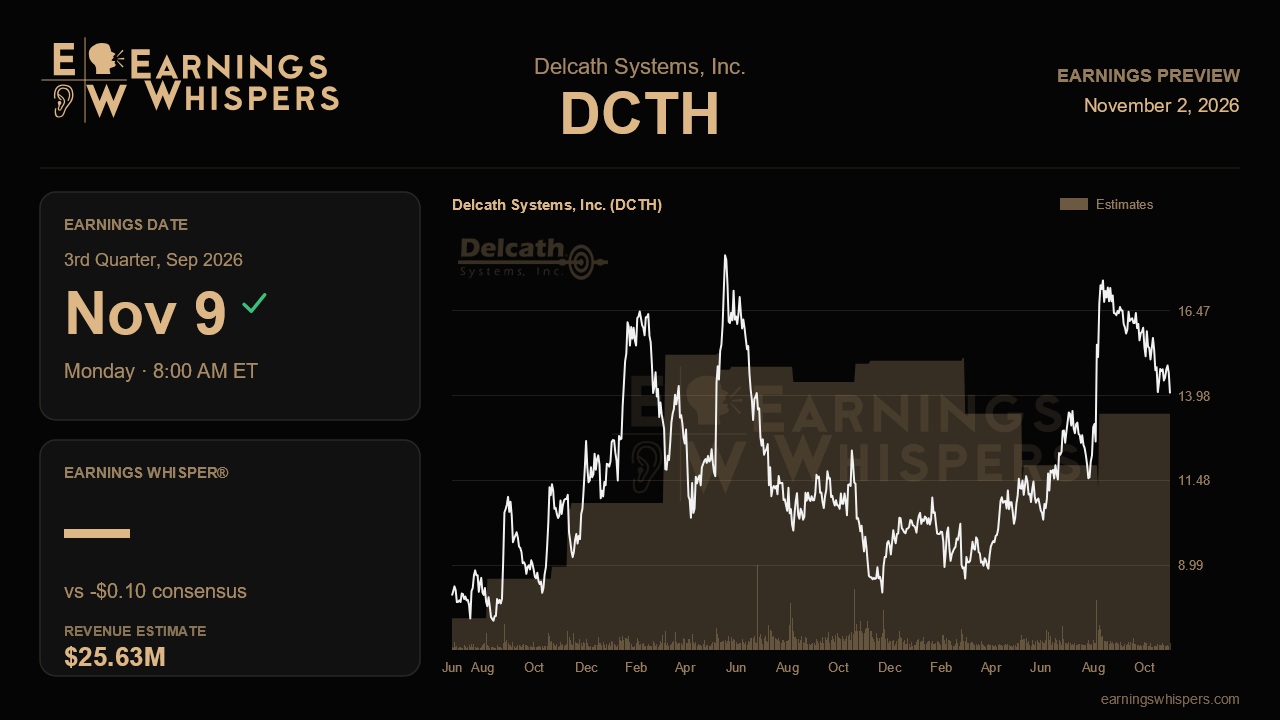
Delcath heads into its third-quarter report with a question it failed to answer convincingly a year ago: can the HEPZATO KIT business hold its momentum through the summer months? Last year's September quarter brought a miss and a guidance cut that left investors wary of seasonal softness. This time management struck a more confident tone, saying its near-term scheduling window was not showing the slowdown it saw at the same point last year. The upcoming release, due before the open on November 9, will show whether that early read held up for the full quarter.
The Street is not taking that confidence entirely at face value. Consensus calls for revenue of about $25.6 million, up roughly 25% from $20.6 million a year ago but well below the $29.1 million Delcath posted last quarter. Analysts also expect a loss of about $0.10 per share, against a $0.07 profit in the prior quarter and $0.02 a year earlier. In other words, the bar assumes healthy annual growth paired with a meaningful sequential pullback and a swing back into the red. A result near or above last quarter's revenue would directly support management's view that seasonality is fading, while a number at or below consensus would suggest the summer lull simply arrived later than the forward window indicated.
Gross margin is the second pillar of the story. Last quarter came in at 90%, up from 86% a year earlier, and management lifted its full-year margin outlook to 86% to 89%, the third successive step up from an initial 84% to 87%. That progression raises the stakes, because the finance team also cautioned that additional manufacturing costs in the back half could push a quarter below 90%. A modest dip would be consistent with that warning and should not alarm anyone. A drop toward the low end of the range, however, would raise questions about whether the guidance increase was premature. Pricing remains the persistent drag, as 340B discounts have pulled the effective price per kit down to roughly $170,000 to $173,000 from about $185,000, which explains why revenue growth has trailed volume growth of around 30%. The gap between those two figures is worth tracking to see whether the 340B mix is stabilizing or widening.
Site activation should provide the cleanest evidence of underlying demand. Management expressed strong confidence in reaching 37 activated treatment centers, describing a queue of hospitals moving through training with patients already scheduled. Progress toward that target, along with reaffirmation of the full-year revenue floor of more than $100 million, would validate the commercial narrative. The clear weak spot is the clinical program. Enrollment in the colorectal and breast cancer trials was running well below plan, with some centers lost because interventional radiology and oncology teams struggled to coordinate. Any sign of stabilization there would help, while further slippage would push out the label-expansion story that underpins longer-term growth.
Sentiment has shifted noticeably, moving from moderately bearish ahead of the last report to moderately bullish now. The stock tells a more muted tale. Shares are essentially flat since the last report, edging out a slightly weaker S&P 500, but at $14.04 they sit just above the post-earnings low of $13.91 after reaching $17.42. The stock remains above its 200-day average and trades in a higher range than the prior quarter, yet it has surrendered most of its post-report gains, implying the market is reserving judgment.
The central issue is whether Delcath can show that its seasonal stumble last year was an anomaly rather than a pattern. Revenue that comfortably clears a consensus that already embeds a sequential decline, alongside margins holding within the raised range and continued site additions, would keep the improving narrative intact. A soft quarter paired with further clinical delays would instead suggest the commercial strength of the spring was more fragile than management's tone implied.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Oct-27 | |
| Oct-26 | |
| Oct-19 | |
| Sep-11 | |
| Aug-31 | |
| Aug-06 | |
| Aug-06 | |
| Jul-28 | |
| Jul-23 | |
| Jul-16 | |
| May-26 | |
| May-15 | |
| May-12 | |
| May-07 |
