GCM Grosvenor Heads Into Q3 With A SpaceX Windfall To Mark And A Fundraising Promise To Keep
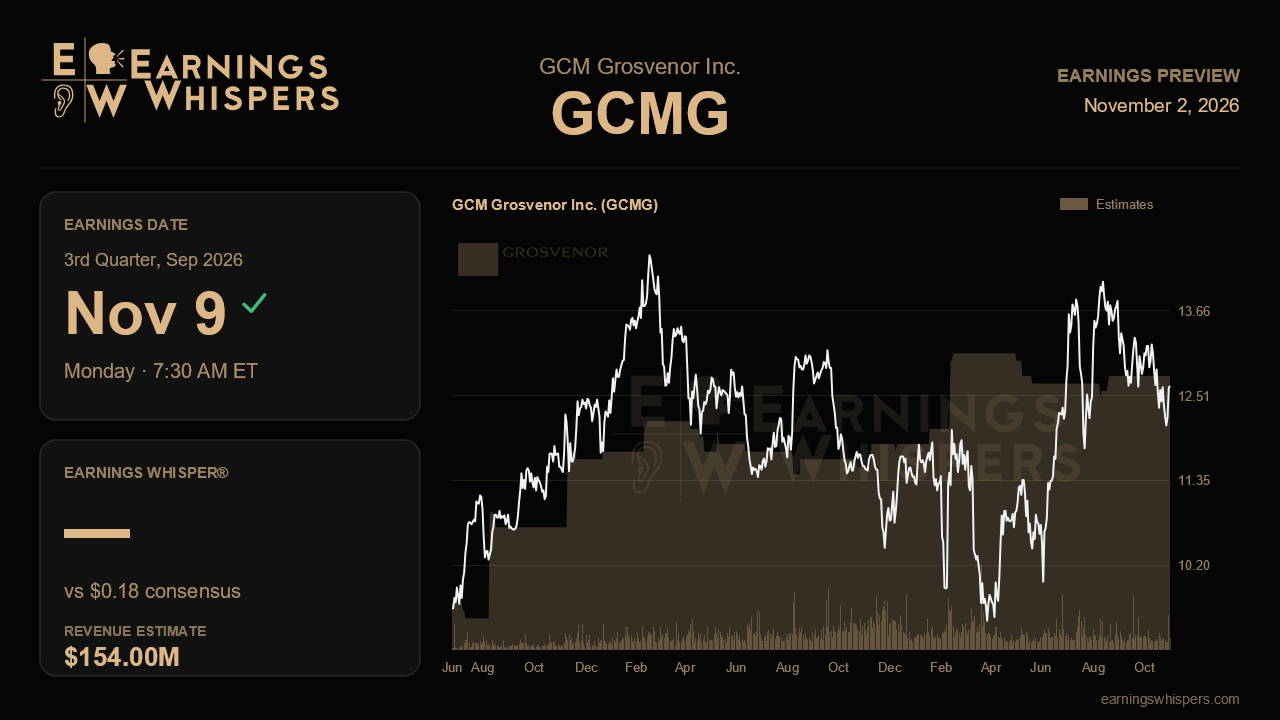
GCM Grosvenor enters its third-quarter report with an unusual setup: a balance sheet of potential upside that has barely touched its share price. Last quarter management disclosed that a SpaceX position bought for roughly $150 million is now worth about $3.5 billion, the largest single-issuer gain in the firm's history. It also said fundraising was reaccelerating and that the second half would top the first. Yet the stock has fallen 8.5% since that call, trailing the S&P 500 by more than six percentage points. The November 9 release, due before the open, is the first real chance to show whether that optimism turns into numbers.
The Street expects earnings of $0.18 a share on revenue of $154.0 million. That would mean revenue growth of about 14% from a year ago while earnings rise only about 6%, a gap worth noticing. Revenue is also expected to jump roughly $20 million from the prior quarter's $134.3 million. That leaves the result sensitive to fee and incentive timing rather than to steady management-fee growth alone. GCM has issued no formal earnings guidance, so the best yardsticks are the specific fee comments it made last quarter.
Those comments pointed in two directions. On the bright side, management guided absolute return strategies management fees up about 10% sequentially and around 20% year over year. That is double the roughly 10% annual pace of earlier quarters, backed by fee-paying assets in that business up 22%. Delivering on that is the cleanest test of whether the hedge fund side has become a real growth engine. On the softer side, private markets management fee growth was guided down to the mid-single digits from about 10%, with no meaningful catch-up fees expected. A result in line there would be neutral. A further slowdown would raise questions about how much of the fee-paying asset growth, now $78 billion, is actually earning fees.
Profitability is the next checkpoint. Fee-related earnings margin rose to 45% last quarter from 44%. Holding or extending it while the business mix shifts would support the operating leverage story. Fundraising matters just as much. After $3.9 billion in the first half, including $2.3 billion in the second quarter, management called the pipeline full. A third quarter that falls well short of that pace would undercut the claim that the second half will be bigger. Credit deserves particular attention after it raised more than $900 million last quarter and closed a $1.2 billion inaugural credit secondaries fund. So does the individual investor channel, which supplied 23% of year-to-date fundraising. Steady inflows from both would ease worries tied to the wider scrutiny of private credit.
Then there is SpaceX. Because private holdings are valued a quarter late, the third quarter should reflect a much higher mark than the $84 per share used in the second quarter. Management said each $10 move is worth about $4 million in performance fees. A visible jump in unrealized carry would confirm the size of the opportunity, but it remains unrealized and timing-dependent. Management also conceded that realizations and middle-market exits are still not firing on all cylinders. Any progress on actual cash realizations would carry more weight than paper gains.
Sentiment has cooled to 24.0% bullish from 34.8% heading into the last report. The stock, at $12.64, sits just above its 200-day moving average of $11.87. It is closer to the bottom of its post-earnings range of $12.05 to $14.87 than to the top. That suggests a bar lowered by skepticism rather than inflated by enthusiasm. The deciding question is whether recurring fee growth, led by the promised acceleration in absolute return fees and a second-half fundraising pickup, shows up on schedule. If it does, the SpaceX gain becomes a bonus on a healthy business. If it does not, the market may keep treating that windfall as a story rather than as earnings.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-31 | |
| Oct-26 | |
| Sep-28 | |
| Sep-25 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Jul-27 | |
| Jul-23 | |
| Jul-15 | |
| Jun-25 | |
| Jun-04 | |
| May-26 | |
| May-19 |
