Kamada's Record Second Quarter Faces A Durability Test As Unraised 2026 Guidance Looms
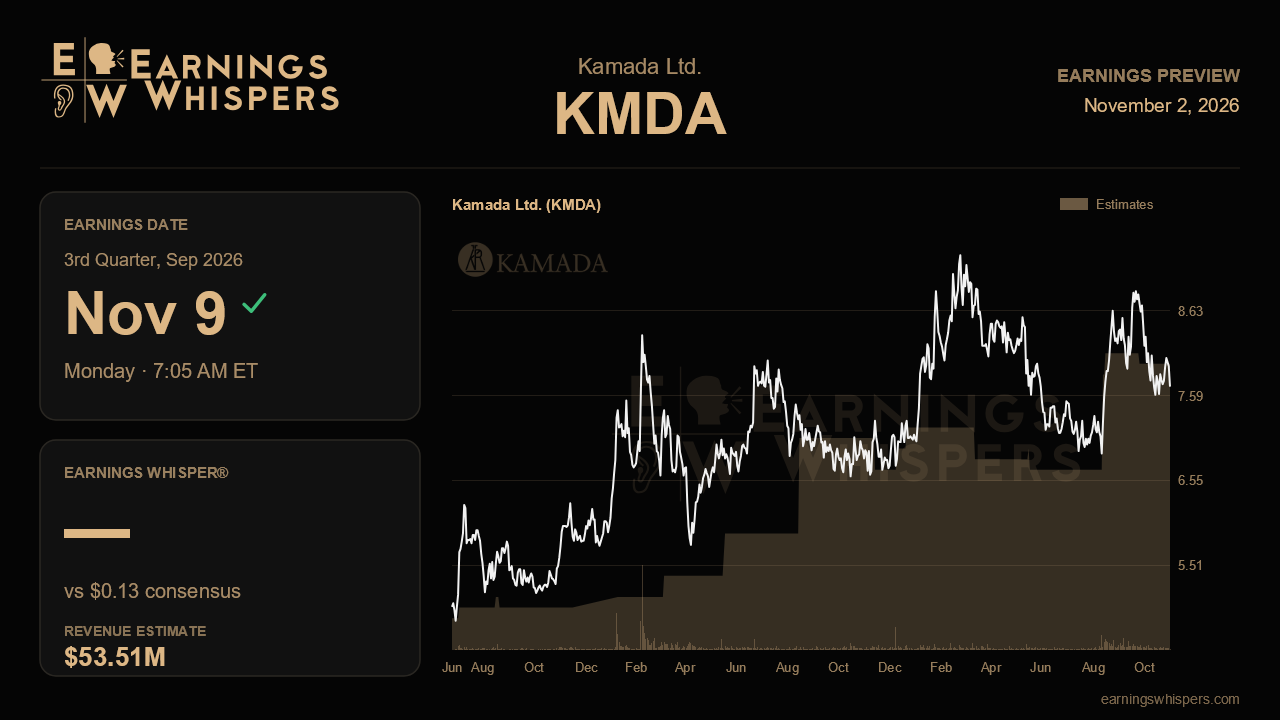
Kamada heads into its third-quarter report with a question that cuts to the heart of its recent momentum: was the record second quarter the start of a sustained step up, or a catch-up quarter flattered by revenue that slipped out of a soft first quarter? Management's decision to reaffirm, rather than raise, its full-year outlook after a strong first half left that question open, and this report is the first real chance to answer it.
The Street is looking for earnings of $0.13 per share on revenue of $53.5 million. That would mark solid year-over-year growth of roughly 14% on the top line and about 44% on earnings against last year's $0.09, but it also represents a modest sequential step down from the $54.9 million and $0.16 posted in the second quarter. In other words, analysts are not extrapolating the 23% growth rate from last quarter. They are modeling something closer to the company's underlying trend, which is a reasonable bar given that part of the prior quarter's strength likely reflected a roughly $2.4 million shipment delay pushed out of the first quarter.
Guidance frames the math. Kamada continues to call for 2026 revenue of $200 million to $205 million and adjusted EBITDA of $50 million to $53 million. With $100.2 million of revenue already booked in the first half, the company needs roughly $100 million to $105 million in the back half. Full-year consensus of about $202.9 million sits just above the midpoint, and if the third quarter lands near $53.5 million, the implied fourth quarter would be around $49 million. That looks undemanding, particularly since the new three-year, $50 million normal source plasma supply agreement is expected to begin contributing sales in the fourth quarter. A third quarter at or above consensus would put the upper half of the range firmly in play and could revive the debate a Stifel analyst raised last quarter about why the outlook was not lifted.
The quality of the revenue matters as much as the total. Management described demand for Kedrab, Varizig and Hepagam as rising, with Kedrab supply to partner Kedrion running above contractual minimums, and the newly FDA-approved in-house rabies antibody lab should speed Kedrab release. Evidence that these specialty products are carrying growth would validate the narrative. Cytogam is the swing story: supportive transplant data could finally reverse a franchise that shrank last year as antivirals gained access, so stabilization there would be meaningful. Incremental contributions from Israeli biosimilar launches and new distribution deals across the Middle East and North Africa would show the growth model is broadening beyond a few products.
Gross margin remains the recurring soft spot. It slipped to around 42% last quarter on product and market mix, and management characterized the move as a quarter-to-quarter shift. Another decline would make that explanation harder to accept and would pressure the EBITDA math, since the company needs roughly $24 million to $27 million in second-half adjusted EBITDA. Commentary on the undisclosed management departure and on cash generation, which more than doubled in the first half, will also shape confidence.
The market has given Kamada some credit. Shares are up 8.6% since the last report while the S&P 500 fell 2.5%, and sentiment, though still bearish, has improved from the prior quarter. Yet at $7.70 the stock has retreated well off its post-earnings high of $8.96 and sits below its 200-day moving average near $8.02, suggesting enthusiasm has cooled. Ultimately, the report hinges on whether Kamada can show that second-quarter strength was underlying demand rather than timing, while holding margins steady enough to make the reaffirmed guidance look conservative.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 9 hours | |
| Oct-19 | |
| Oct-06 | |
| Sep-17 | |
| Sep-10 | |
| Sep-03 | |
| Aug-17 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 | |
| Aug-05 | |
| Jul-20 |
