Heron's Third-Quarter Report Hinges On Sinvanti's Defense, Covenant Headroom And A Strategic Review
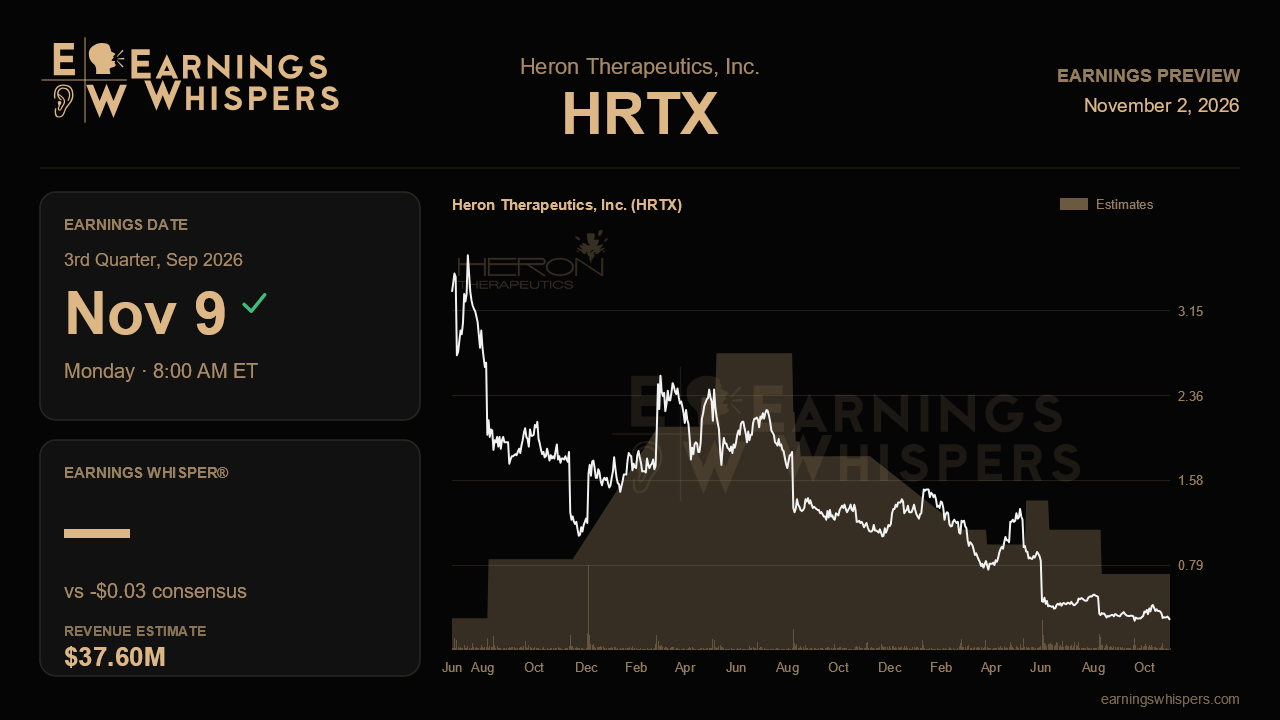
Heron Therapeutics heads into its third-quarter report as a fundamentally different company from the one that spent most of the past year promising an acute care inflection. Last quarter it lost a patent ruling on Sinvanti, its largest product, and withdrew full-year guidance. It also renegotiated its debt, paused a planned salesforce expansion and said it was exploring strategic alternatives. With the stock trading at roughly 28 cents, the November 9 release, due before the open, is less about beating a penny-sized estimate than about whether the business can hold together long enough for that strategic process to produce a result.
The Street expects a loss of 3 cents a share on revenue of about $37.6 million. That would be essentially flat with the $37.7 million reported last quarter and down 1.6% from a year ago. The projected 40% improvement in EPS sounds impressive, but it reflects a smaller loss rather than any real earnings power. The more telling gap is on the full year. Before pulling its outlook, management had guided to $173 million to $183 million in net product sales, and full-year consensus still sits at about $173.1 million, right at the bottom of a range the company no longer stands behind. Hitting that figure would require a sharp second-half acceleration from a run rate in the high $30 millions. The quarterly estimate looks modest, but the annual number looks stale and is a candidate for downward revision whatever this quarter shows.
Sinvanti is the swing factor. Sales of $21.8 million last quarter were already down about 10% from a year earlier before the June court decision opened a path to generic competition. Management said it began defensive contracting early, which usually means trading price for volume. Investors should look closely at whether Sinvanti revenue holds near last quarter's level and whether net pricing is deteriorating. Any update on the appeal or on how soon generics could launch matters just as much. A steep decline would be hard for the smaller products to offset.
Those smaller products remain the one part of the story that still works, though even they fell short of internal plans. Zynrelef reached $11.1 million last quarter with 35% year-over-year growth, but that pace has slowed noticeably from the high 40s seen in late 2025. Aponvy grew 74% to $4.2 million and gained two points of NK1 share. Together they provide the clearest evidence of whether the Ignite 2.0 commercial program, now running in about 3,150 accounts, can sustain growth without the extra sales reps management shelved. Steady sequential gains in both would support the idea that the acute care franchise has value to a buyer or partner. Further deceleration would weaken it.
The balance sheet may matter more than the income statement this time. Pro forma cash after the Hercules paydowns was only about $24.3 million. The amended facility imposes monthly minimums on revenue, EBITDA and cash through December 2027. Gross margin of 69.3% remains below the mid-70s level management has long said would normalize, which leaves little cushion. Clear covenant compliance, disciplined cash burn and any progress on the strategic review would help. Silence on these points would not.
The market's verdict has been severe. Shares have fallen 34% since the last report, against a 2% slip in the S&P 500. They sit far below the 200-day average of 70 cents and near the bottom of a post-earnings range of 26 to 43 cents. Sentiment has improved from deeply muted to modestly bullish, perhaps reflecting speculation about a deal at a depressed price. The central question is whether Sinvanti's erosion can be contained while the acute care products keep growing, because that combination determines both covenant headroom and what Heron is worth to anyone across the table.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-26 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-27 | |
| Jun-02 | |
| Jun-02 | |
| May-12 | |
| May-11 | |
| May-11 | |
| May-11 | |
| Apr-27 | |
| Feb-26 |
