LifeMD Must Prove Its Promised Second-Half Turn After A Bruising Guidance Cut
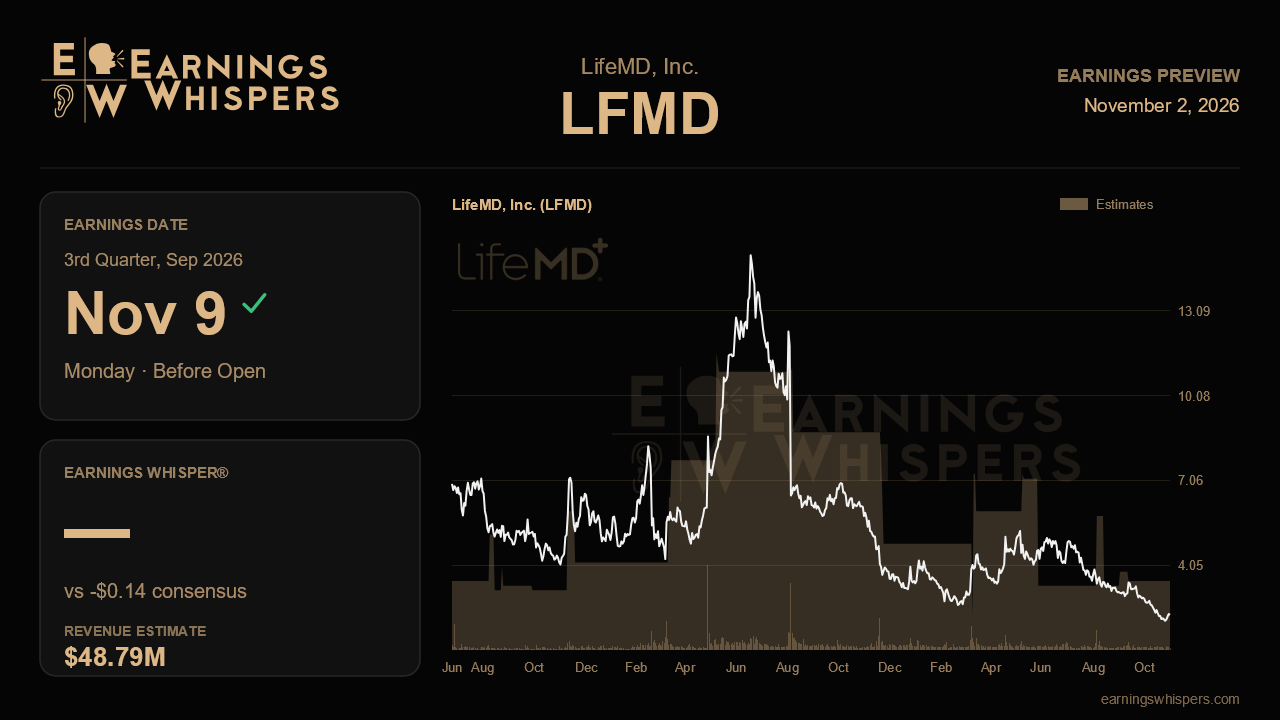
LifeMD heads into its third-quarter report with a credibility problem rather than a demand problem, or at least that is the case management needs to make. In May the company reaffirmed its full-year outlook. In August it cut both revenue and profit targets. It now asks investors to believe that the third quarter marks the start of a sharp second-half inflection. The November 9 report, due before the open, is the first real check on whether that pivot is working or whether another reset is coming.
The Street expects a loss of $0.14 per share on revenue of $48.8 million. That would be a modest sequential improvement from the $0.16 loss and $47.3 million in revenue posted last quarter. Against the year-ago quarter, though, the picture is contraction: revenue down roughly 19% from $60.2 million and a wider loss than the $0.10 reported a year earlier. Consensus sits near the low end of management's $48 million to $51 million quarterly range. Analysts are clearly not giving the company the benefit of the doubt, which lowers the bar for a revenue beat. It also means a print below the range would land hard.
Revenue is only part of the test. Management said it expects to return to positive adjusted EBITDA in the third quarter, following a $3.5 million loss in the second quarter that missed its own guidance. Hitting that target matters more than the headline loss per share. The revised full-year EBITDA range of negative $6 million to breakeven, and the fourth-quarter guide of $60 million to $64 million in revenue with $3 million to $6 million of EBITDA, both depend on a steep ramp. A third quarter that only scrapes into the revenue range while staying in the red would make that fourth-quarter jump look ambitious.
The operating details will tell investors whether the ramp is plausible. The $39 introductory weight management offer pushed about 85% of new patients into multi-month plans. That should improve lifetime value but held back upfront cash. Signs that those cohorts are renewing, alongside customer acquisition costs holding well below their June peak, would support the thesis. Active subscribers slipped to 356,000 last quarter, so a stabilization or rebound there is important. Gross margin near 89%, helped by the in-house pharmacy, should remain a bright spot. Women's health, which management expects to grow its patient base by 300% to 400% by year end, and the expansion of insurance coverage are the growth threads to check. Cash, which fell to $25.1 million from $34.5 million, deserves close attention. Another drop of that size would raise funding questions that no margin metric can offset.
On the risk side, the factors that hurt last quarter remain the swing variables. These include volatile paid media costs, compounded GLP-1 revenue fading faster than branded volume replaces it, and partnership launches slipping. The new Ziosted testosterone collaboration is a long-dated story, with accretion not expected until mid-2027 and startup costs landing this year. Early uptake data would be helpful, but meaningful revenue is not a reasonable expectation yet.
The market has already delivered its verdict on the August cut. Shares have fallen about 29% since the last report, trailing the S&P 500 by 27 points. At $2.29, the stock trades far below its 200-day average of $3.66 and closer to its post-earnings low of $2.06 than its high of $3.71. Sentiment remains bearish but less so than heading into last quarter, which suggests some selling pressure may have run its course. The central question is simple: did LifeMD reach EBITDA profitability while landing inside its revenue range, and does it still stand behind the fourth-quarter numbers? A yes on both would begin rebuilding trust. Any further retreat would confirm the market's skepticism.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-20 | |
| Sep-22 | |
| Sep-15 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-24 | |
| Jun-23 | |
| Jun-22 | |
| Jun-01 | |
| May-18 | |
| May-15 | |
| May-06 | |
| Apr-27 |
