PSEG Misses On Regulatory Lag, Holds Guidance As Rate-Filing Shift And Nuclear Basis Questions Cloud 2027
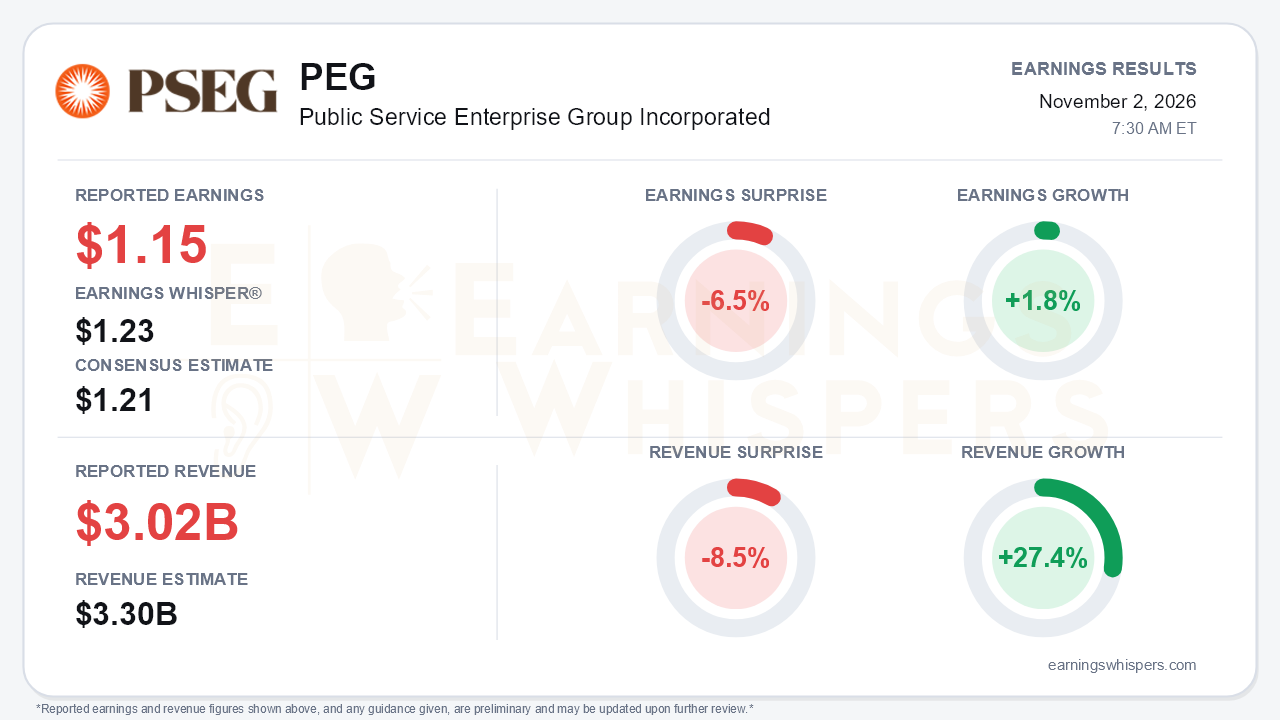
Public Service Enterprise Group (NYSE: PEG) delivered a third quarter that undershot expectations even as management signaled the year remains on track. Non-GAAP operating earnings of $1.15 per share missed the $1.21 consensus by 6.5% and fell further short of the $1.23 Earnings Whisper number, though they still grew 1.8% from $1.13 a year earlier. Revenue of $3.02 billion missed the $3.30 billion consensus by 8.5%. Earnings Whispers' normalized data show 27.4% year-over-year revenue growth, but the company's consolidating statement reports operating revenue of $3.02 billion against $3.23 billion a year ago, with Power & Other revenue down to $532 million from $749 million. Investors should be aware of that discrepancy. Management reaffirmed 2026 non-GAAP guidance of $4.28 to $4.40. That is the central tension: a reaffirmation quarter that came in light, with the softness concentrated in the regulated utility that is supposed to be the dependable engine.
The quality of the quarter deserves scrutiny. PSE&G earnings slipped to $506 million from $515 million despite continued investment in transmission and energy efficiency and steady customer growth. The release attributes the decline to higher depreciation and interest on investments not yet reflected in rates, plus tax timing. The call added that distribution O&M rose $0.10 per share year over year, far above the $0.01 increase in the second quarter. Refinancing costs are also moving the wrong way: August medium-term notes priced at 5.4% and 6.05% replaced 2.25% debt. The upside came from PSEG Power & Other, where non-GAAP earnings rose to $68 million from $50 million. That gain reflected the absence of last year's Hope Creek refueling outage, higher realized prices and more nuclear output. The fleet ran at a 95.5% capacity factor, up from 92% in the second quarter. On a GAAP basis, the picture was much weaker. Net income fell to $0.76 per share from $1.24, driven by a $251 million pre-tax mark-to-market loss and a $21 million trust loss that pushed Power & Other to a $130 million net loss.
What changed most on the call was the language around regulatory recovery. In the second quarter, management said PSE&G would file by year-end 2026 to update base rates. This time it described a proposal to address regulatory lag on capital invested since the last rate case, framed around the governor's affordability agenda and consistent with keeping rates flat. Details were withheld. For a company whose regulated earnings are already being eroded by lag, a potentially less conventional or more modest recovery path is a meaningful shift. Investors will need clarity on it before giving full credit to the 6% to 8% EPS growth target through 2030. Year-to-date non-GAAP EPS of $3.56 implies roughly $0.72 to $0.84 in the fourth quarter. CFO Dan Craig steered toward the midpoint, but the range was not narrowed.
On the power side, bears have legitimate ammunition. The PECO-West Hub basis discount widened to about 30% from roughly 20%. Management said 2027 is hedged above the production tax credit level but declined to quantify 2028 hedges. The RBP auction slipped to March 2027 or later after a partial FERC rejection. The roughly $0.08-per-share RTO adder headwind arrives in January 2027. Large-load inquiries have also stalled at about 11.8 GW since December 2025, mostly from edge computing, which tempers the data-center narrative. The catalyst list is real but mostly prospective:
- Salem upgrades tied to a Constellation deal, already within the five-year plan.
- The governor's Nuclear Task Force and a coming BPU new-nuclear auction.
- A potentially larger PJM transmission open window.
- Bilateral contracting talks that management says are advancing, with nothing yet announced.
The balance sheet gives PSEG room to wait. Liquidity rose to $3.9 billion from $3.4 billion, and cash reached about $830 million, though total debt climbed to $25.6 billion from $24.1 billion.
The market setup is more complicated than the miss implies. Shares hit a 52-week low of $66.15 on September 25. They have since rebounded about 12% to $74.29, but remain 2.1% below the opening price after the prior report and 4.8% below the 200-day moving average. Investor sentiment remained negative but improved meaningfully, rising to -0.28 from -0.48. That suggests some of the skepticism had already eased into the print. AVWAP readings are positive while price and momentum trends are neutral, consistent with a stock that has recovered without yet reclaiming its longer-term trend.
The bottom line is that PSEG kept its 2026 commitments intact, while the details of the quarter made the path beyond 2026 harder to underwrite. Regulated earnings are being squeezed by lag, O&M and higher interest costs. The fix is now framed as a rate-neutral proposal rather than a conventional rate case, and nuclear pricing beyond 2027 faces wider basis and auction delays. Until the February 2027 plan roll-forward and the regulatory filing details arrive, the reaffirmed guidance is a floor of confidence rather than a source of upside.
Read our earnings preview for Public Service Enterprise Group Incorporated: https://www.earningswhispers.com/article/PEG/21356
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-15 | |
| Oct-13 | |
| Oct-08 | |
| Oct-06 | |
| Oct-02 | |
| Sep-29 | |
| Sep-28 | |
| Sep-22 | |
| Sep-21 | |
| Sep-09 | |
| Aug-28 |
