NRG's Summer Quarter Tests Whether Texas Weakness Can Coexist With A Near-Top Full-Year Bar
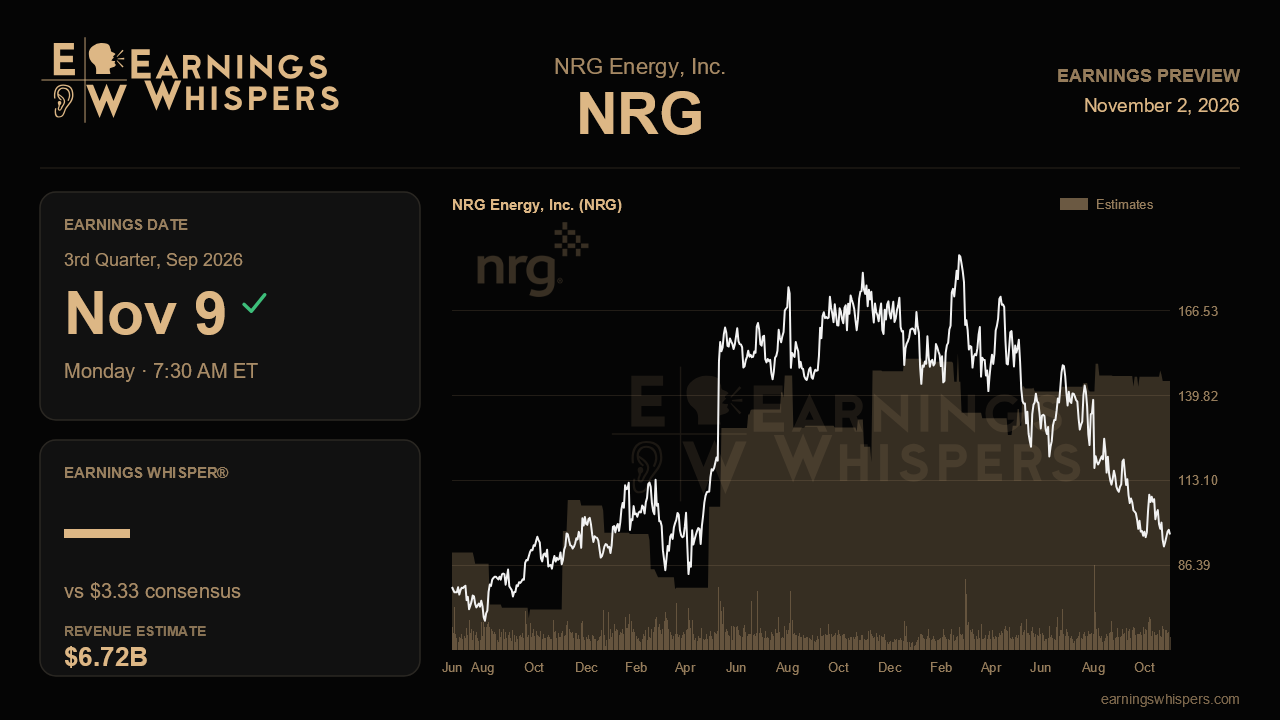
NRG Energy heads into its third-quarter report with a split personality. Last quarter management finally turned years of data-center talk into a concrete 1.2 gigawatt deal with an investment-grade hyperscaler, yet the stock has since lost nearly a third of its value. The report due before the open on November 9 has to show that the strategic upside is not being undermined by the steady erosion in NRG's Texas business, which matters most in the summer quarter.
The Street expects adjusted earnings of $3.33 per share, up about 21% from $2.75 a year ago, on revenue of roughly $6.72 billion, down 12%. That gap is worth noting. Analysts are betting on a quarter where earnings grow while the top line shrinks, so margin and segment profitability will say far more than revenue. Management reaffirmed 2026 EPS guidance of $7.90 to $9.90, and the full-year consensus of $9.70 sits near the top of that range. That is a demanding position given that management admitted in August that the first half was tracking below the midpoint. For the Street's math to work, the third quarter has to carry a lot of the load.
Texas is the swing factor. Second-quarter Texas segment EBITDA fell $131 million year over year, with Houston around-the-clock power averaging $33 per megawatt-hour, well below the $52 NRG used for planning. Management pointed to weak load, soft prices and limited volatility, and noted that forward curves were not responding to the large-load pipeline in the state. A hot summer with even modest scarcity pricing would validate the view that softness was cyclical. Another quarter of subdued ERCOT pricing would raise harder questions about whether reaffirmed guidance is still realistic, or whether the range is being held up only by the East.
That East segment is the main source of growth. The LS Power portfolio and higher PJM capacity revenue drove a 34% jump in second-quarter adjusted EBITDA to $1.2 billion. Two newer drags deserve attention: roughly $70 million of unplanned 2026 cost from Virginia rejoining RGGI, and below-market legacy hedges on the acquired PJM fleet that limit the benefit of stronger power prices into 2027. Investors should look for evidence that these items are tracking as described rather than growing. Smart home, which reached 2.45 million customers last quarter, offers a smaller but steady check on the retail side.
Then there is the hyperscaler project. The economics outlined in August were attractive: about $500 million of annual run-rate EBITDA from a $3.2 billion build, with most cash flow tied to availability payments rather than usage. But final investment decision, land issues and internal approvals were still pending, and management would not commit to a timeline. Any movement toward FID, progress on the expansion option to 2.4 gigawatts, or a capital partner structure that eases the balance sheet would strengthen the story. Funding the project already pushed the three-times leverage target from 2028 to 2029 and trimmed this year's debt reduction, so updates on deleveraging and buybacks will be watched closely.
The market's mood has soured. Sentiment has slipped to 10.4% bullish from 22.0% before the last report, and at $96 the stock trades far below its 200-day moving average near $135 and only about 6% above its post-earnings low of $90.80. That suggests much of the disappointment is already priced in, but it does not guarantee relief. The real test is simple: NRG needs a third quarter strong enough to keep the high end of guidance believable despite Texas, plus enough progress on the data-center deal to show its long-term growth is getting closer.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-28 | |
| Oct-26 | |
| Oct-20 | |
| Oct-19 | |
| Oct-19 | |
| Oct-19 | |
| Oct-15 | |
| Oct-15 | |
| Oct-14 | |
| Oct-12 | |
| Oct-09 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 |
