NRG Smashes Q3 Estimates And Sells $4 Billion Of Plants To Fund Buybacks, But Weak ERCOT Pricing Flattens The 2027 Outlook
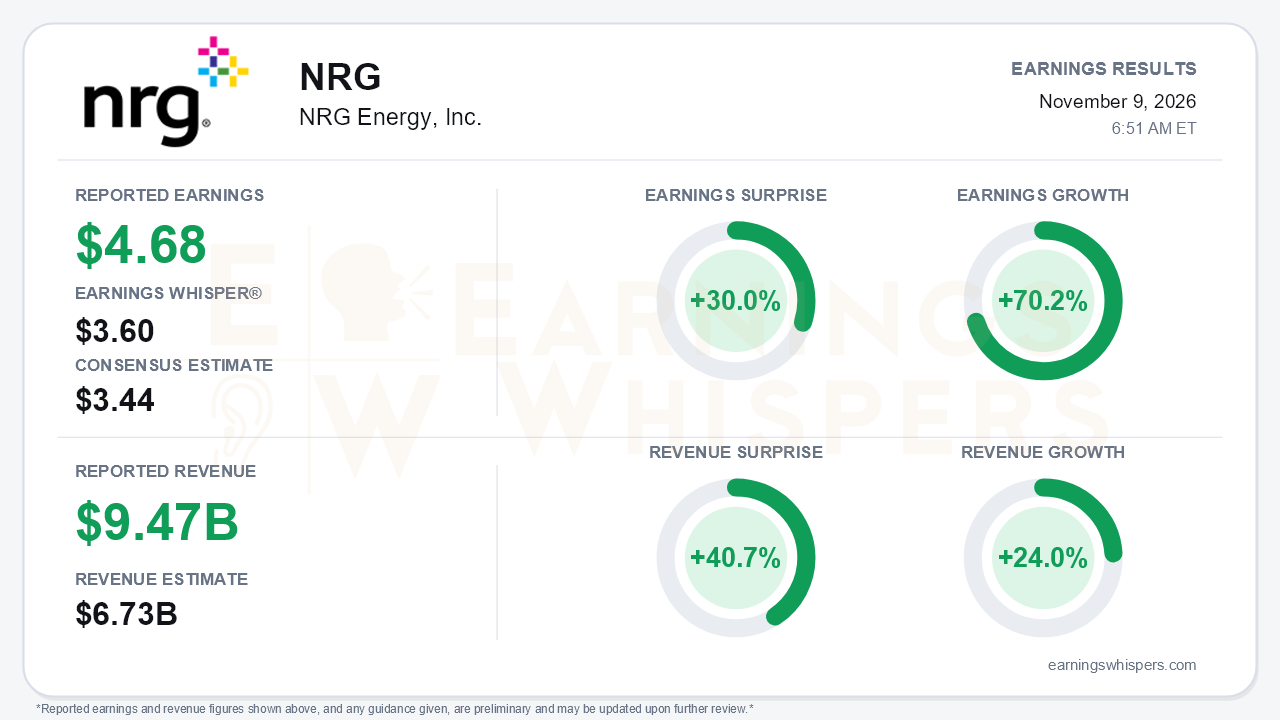
NRG Energy delivered a quarter that would normally reset the narrative. Adjusted EPS of $4.68 beat the $3.44 consensus by 30.0% and cleared the $3.60 Earnings Whisper number. Earnings grew 70.2% year over year, and revenue of $9.466 billion rose 24.0%, topping the $6.73 billion consensus by 40.7%. The growth inflection is real. Management's own comparisons show Q3 adjusted EBITDA of $2.0 billion up roughly two-thirds, against a 34% gain in Q2, when adjusted EPS fell to $1.49, and a decline in Q1. Yet the stock entered the report down 36.9% since the open after the August release. That gap is the central tension: investors are not doubting the quarter so much as the durability of the earnings power behind it.
The quality of the beat deserves scrutiny. Most of the improvement was acquired or weather-driven. East adjusted EBITDA jumped from $107 million to $614 million on the LS Power portfolio, CPower and higher PJM capacity prices. Texas rose $211 million on retail margins and a hot summer, but it was flat for nine months ($1,615 million versus $1,618 million) because a mild winter wiped out the gain. Below EBITDA, the acquisition's costs are heavy. Interest expense climbed to $302 million from $187 million, D&A rose to $510 million from $360 million, and the basic share count increased to 210 million from 193 million. As a result, nine-month adjusted EPS is only $7.68 versus $7.17, despite a $1.07 billion rise in adjusted EBITDA. GAAP EPS of $2.59 trailed the adjusted figure by a wide margin. The gap reflects $155 million of mark-to-market hedge losses tied to falling gas prices and a $172 million charge for terminating acquired hedges, both excluded from adjusted results. Vivint was the cleanest growth story, with EBITDA up 14% to $317 million on more customer additions and higher recurring margin.
The call shifted the story from reaffirmation to capital-return acceleration. NRG agreed to sell six gas plants totaling 4.9 GW to LS Power for $4 billion. The deal was unsolicited and priced at roughly 8x 2027 estimated EBITDA, and NRG keeps the PJM fleet and CPower. The proceeds fund an incremental $1 billion buyback starting before year-end, bringing repurchases to $3 billion across 2026-27, plus $2 billion of debt reduction at closing, with another $1 billion held for contracted growth or further deleveraging. Management sounded notably more assertive, saying it had "never felt more strongly" about the plan. It reaffirmed its 14%-plus EPS and free-cash-flow-per-share growth target through 2030, with or without the sale. The 1.2 GW Texas Bring Your Own Power (BYOP) data center project also advanced. Remaining issues are resolved, a definitive agreement is expected by year-end, and follow-on projects with the same hyperscaler are under discussion.
Bears still have legitimate ammunition. ERCOT prices have averaged about 40% below NRG's 2026 planning assumption. The 2027 outlook absorbs $185 million of net wholesale price pressure and a $100 million RGGI compliance cost, up $30 million from 2026. Legacy LS Power hedges limit 2027 PJM upside. The 2027 adjusted EPS midpoint of $9.05 is only about 1.7% above the 2026 midpoint, and the $5.75 billion EBITDA midpoint sits $285 million below management's normalized opportunity. The 2027 guide also excludes the sale and will be rebased after a closing that requires FERC, HSR and New York approvals. The balance sheet is tighter after the acquisition. Liquidity fell to $6.0 billion from $9.6 billion, cash was just $148 million, and long-term debt rose to $21.8 billion. Finally, the BYOP contract remains unsigned nine months after the original 2026 target.
The market setup is more complicated than the surprise implies. Shares closed the pre-report snapshot at $88.29. That is 34% below the 200-day moving average and only 10.8% above the $79.65 52-week low set on November 5, at the bottom of a range that began at $140 in early August. Investor sentiment stayed positive but weakened, slipping from 0.22 to 0.12. The trend signals are mixed: momentum has turned positive, while price and AVWAP readings remain negative. One practical consequence of the selloff is that repurchases executed near current levels retire more shares per dollar than the original plan assumed.
The bottom line is that NRG beat convincingly and used the quarter to turn non-core plants into buybacks and deleveraging. Management also moved its signature data center deal close to signing. The headline growth, however, is largely acquisition-driven, and 2027 earnings growth is nearly flat while ERCOT pricing stays weak. With the stock near its lows, the debate has shifted from whether NRG can execute to whether it can convert deals and capital returns into per-share growth before pressure in the Texas power market erodes the base.
Read our earnings preview for NRG Energy, Inc.: https://www.earningswhispers.com/article/NRG/22579
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 3 hours | |
| 3 hours | |
| 7 hours | |
| 8 hours |
Nuke Stock Constellation Fueled By Earnings; NRG Hits Gas On Buybacks
NRG +10.32%
Investor's Business Daily
|
| 9 hours | |
| 9 hours | |
| 10 hours | |
| 11 hours | |
| 11 hours |
NRG Energy Signs $4 Billion Asset-Sale Agreement, Posts Higher Quarterly Earnings
NRG +10.32%
The Wall Street Journal
|
| 12 hours | |
| 12 hours | |
| 13 hours | |
| 13 hours | |
| 15 hours |
