Praxis Heads Into Q3 With Launch Costs Rising And Two FDA Decisions Just Ahead
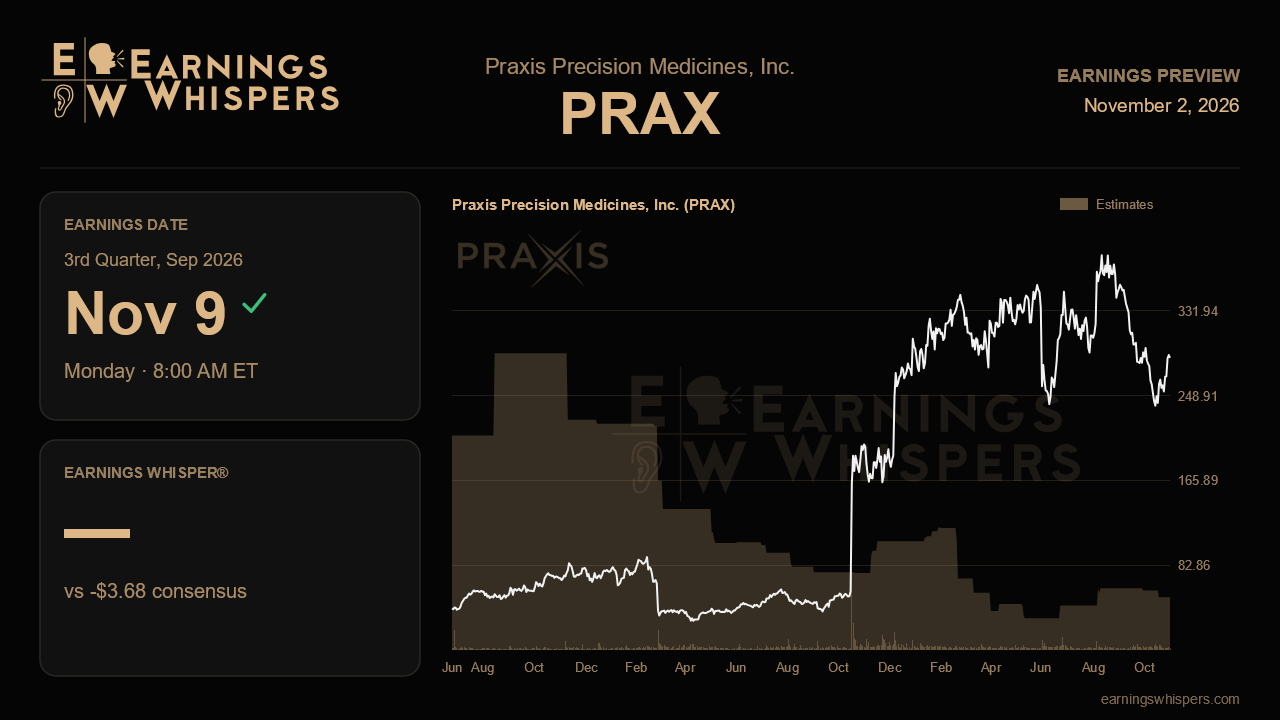
Praxis Precision Medicines reports third-quarter results with its two most important events still ahead of it. The FDA is due to rule on relutrigine by December 27 and on ulexacultamide, or Ulexa, by January 29. Management has said it will give no further regulatory updates until those action dates. That makes this report less about new data and more about whether the company looks ready to launch two drugs, how much that readiness is costing, and whether the vermatrogene setback is being contained.
Wall Street expects a loss of $3.68 per share. That compares with a loss of $3.36 a year ago, a deterioration of roughly 9.5%. It is also notably wider than the $2.87 loss reported last quarter. There is no consensus revenue figure, which fits a company that is still clinical-stage, and no formal financial guidance to measure against. For a pre-launch biotech, though, a wider loss is not a red flag in itself. Management told investors last quarter that general and administrative spending would step up in the second half to support the launches. Second-quarter operating expenses had already reached $96.9 million, with operating cash burn of $78 million, up from $76 million and $55 million a year earlier. The forecast for a wider loss suggests analysts have taken that warning on board.
The narrative from the last call was one of meaningful regulatory de-risking. The FDA completed mid-cycle reviews for both lead drugs without raising any significant efficacy issues. It said it does not plan to hold an advisory committee for either one. A bioresearch monitoring inspection also closed without a single Form 483 observation. On the commercial side, management described a field force of about 300 representatives targeting 13,000 to 15,000 neurologists. It said the relutrigine teams are fully hired, and that payers are now approaching the company rather than the other way around. It also reaffirmed pricing confidence in the $50,000 to $100,000 per year range. Because the regulatory story is now on mute, the evidence for that narrative has to come from operations. That means hiring and infrastructure spending that tracks the plan, and any sign that the payer discussions are taking shape. It also means no new language hinting at further review complications like the major amendment that pushed relutrigine's decision back three months.
The weaker leg of the story is vermatrogene. Power 1 missed its primary endpoint in June. That was a sharp reversal after management had spent prior quarters guiding toward a roughly 30% placebo-adjusted reduction in seizures. Power 2 and Power 3 are being reworked on dose and entry criteria, with a restart targeted for the fourth quarter. Confirming that this timeline is intact would help limit the damage, and any slippage would raise fresh doubts about the program's roughly $4 billion opportunity. Investors will also want to hear that Emerald, which enrolled about 200 patients across more than 50 etiologies, remains on track for a 2027 supplemental filing.
The market has not given Praxis much credit for its regulatory progress. Shares have fallen 18.4% since the last report, against a 1.9% dip in the S&P 500. At $285.93, the stock sits below its 200-day moving average of $314.75 and in the lower half of a wide post-earnings range of $236.80 to $392.70. Sentiment has softened from clearly bearish to only mildly negative, which suggests skepticism is fading even as the share price lags. That gap between a de-risked story and a discounted stock is the core of the setup.
In the end, the per-share loss matters less than the balance sheet behind it. Cash stood at $1.4 billion with a runway into 2028. If Praxis can show that rising launch spending still fits that runway, that commercial readiness is real, and that the vermatrogene restart is on schedule, the improving narrative holds into the December and January decisions. If cash burn accelerates faster than expected, or the trials slip again, the recent selloff may start to look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-27 | |
| Oct-16 | |
| Oct-02 | |
| Sep-03 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-04 | |
| Jul-30 | |
| Jul-07 | |
| Jul-02 | |
| Jun-29 | |
| Jun-22 | |
| Jun-22 |
