NeurAxis Must Show Payer Momentum Can Outrun A Deliberate Rise In Spending
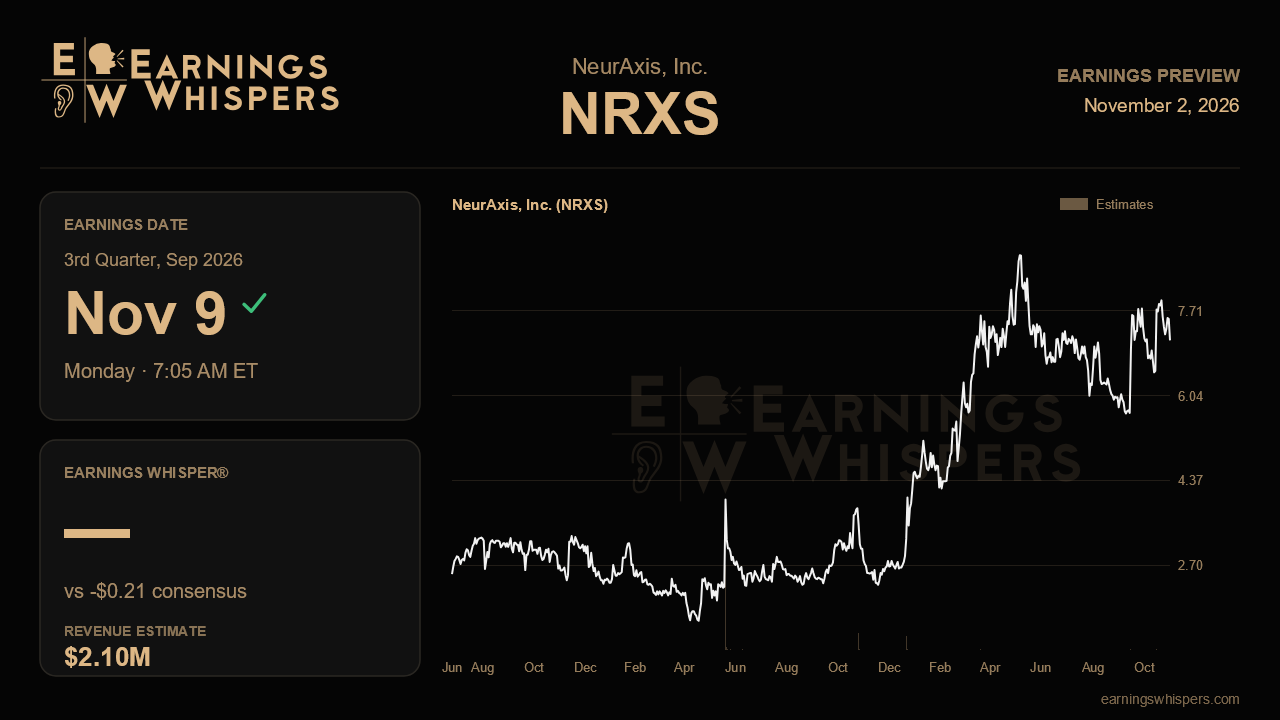
NeurAxis heads into its third-quarter report with a story that has finally started to compound. Revenue growth has climbed from the low 20% range a year ago to more than 100% last quarter as the new Category 1 reimbursement code took hold. Management has chosen this moment to step on the gas with spending. The question for the November 9 release, due before the open, is whether the top line is accelerating fast enough to justify a wider loss and a later path to breakeven.
The Street is looking for revenue of about $2.1 million, up roughly 159% from the $0.8 million posted a year earlier. That would mark another step up in the growth rate, though the comparison flatters a bit because last year's third quarter was soft. Sequentially, the target implies only about 9% growth over the $1.9 million reported in the second quarter. That looks reachable if account productivity holds. The consensus loss of $0.21 per share would be better than the $0.24 loss a year ago but wider than last quarter's $0.19. That pattern fits management's warning that cash burn, which improved to roughly $1.0 million last quarter, would rise in the back half of the year. The company does not provide formal guidance, so the numbers themselves will have to carry the narrative.
The most important evidence will concern payers. Last quarter management sounded noticeably more confident. It described direct talks with medical directors at two large commercial insurers that do not yet cover the therapy, and it expressed high confidence in coverage arriving in the second half of 2026 or early 2027. A signed policy, or a concrete update on timing, would validate the tone shift. Silence would not break the story, but it would push the key catalyst further into the future. Related metrics matter too. The internal prior-authorization approval rate was 31% year to date, slightly below the 32% cited a quarter earlier. Holding or improving that figure would suggest payer friction is still easing. Average selling price near $1,000 per device and gross margin around 86% should stay steady if the shift toward full reimbursement continues.
The Veterans Affairs channel is the newer swing factor. Management upgraded it from a complementary effort to a second meaningful growth platform. That change followed orders and reorders from only three small territories, and it prompted the hiring of 10 contract reps who were due to start selling by mid-September. Little revenue should show up yet. Still, early commentary on facility adoption would show whether this channel can matter in 2027. Meanwhile, bottlenecks flagged last quarter could cap conversion. These include state Medicaid programs that have been slow to load the new code and top hospital accounts that are booking patients months out.
The market has already given NeurAxis some credit. The stock is up nearly 18% since the last report while the S&P 500 slipped about 2%, and at $7.13 it sits above its 200-day moving average. It remains roughly 12% below its post-earnings high of $8.06, however, so this is not a breakout setup. Sentiment readings lean modestly bearish, which suggests skepticism has not vanished, likely because of the going-concern language and preferred dividends paid in stock.
In the end, this report is a test of trade-offs. If revenue keeps climbing, margins hold and management can point to tangible payer progress, a wider loss will look like investment rather than drift. If growth stalls while operating expenses keep rising from last quarter's $3.8 million, the improving narrative will quickly start to look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-27 | |
| Oct-15 | |
| Sep-29 | |
| Sep-16 | |
| Sep-16 | |
| Sep-12 | |
| Sep-08 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Aug-04 | |
| Jul-28 | |
| May-12 | |
| May-12 |
