Uniti's Record Fiber Bookings Face A Skeptical Market As Stock Halves Into Q3
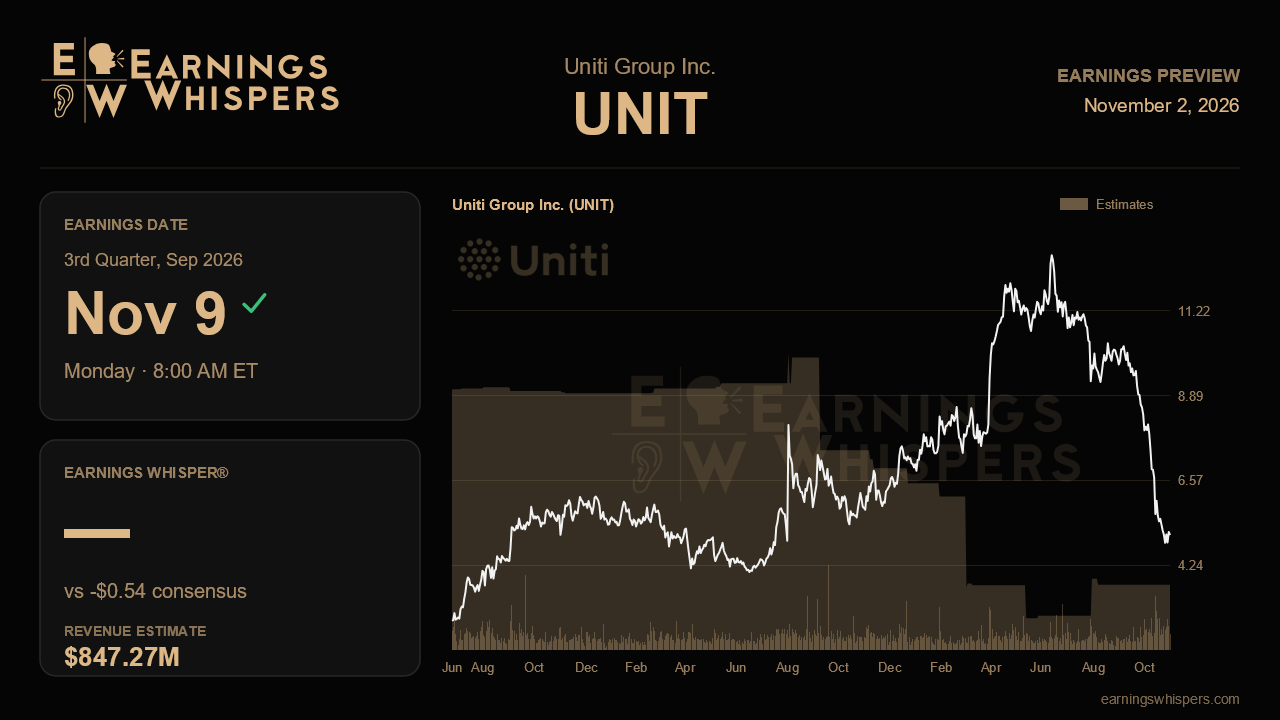
Uniti Group heads into its third-quarter report with an unusual disconnect. Last quarter, management delivered record fiber infrastructure bookings, raised guidance across nearly every segment and sounded more confident about AI-driven demand than at any point this year. The stock has since lost roughly half its value, falling 49.3% while the S&P 500 gained 2.7%. The report due before the open on November 9 has to settle which side has it right: the operating story told on the last call, or a market that appears to have stopped believing it.
The Street expects a loss of $0.54 per share on revenue of $847.3 million. That revenue figure would represent healthy 17.3% growth from a year ago, yet it sits well below the $909.7 million Uniti posted last quarter, so analysts are already allowing for a sequential step down. The expected loss is narrower than the prior quarter's $0.68 but a sharp swing from the $0.16 profit a year earlier. Management lifted its full-year revenue outlook to $3.63 billion to $3.68 billion, and the consensus of $3.63 billion sits right at the bottom of that range. In other words, analysts have not fully embraced the raise. A quarter that keeps Uniti on pace for the midpoint would chip away at that skepticism, while anything pointing toward the low end would suggest the Street was right to hedge.
The heart of the bull case is fiber infrastructure. Second-quarter bookings reached about $2.2 million in monthly recurring revenue, roughly 30% above the prior record, and more than half came from waves and lit services rather than dark fiber. That mix matters because wave revenue is recurring and higher value, whereas large dark fiber deals arrive in lumps. Management pointed to two mega wave packages for a neocloud and a superscaler and a wave funnel of around 1.3 petabytes. Validation this quarter would look like bookings holding near record levels, continued strength in waves, and anchor lease-up yields staying around last quarter's record 37%. A sharp drop in bookings, or evidence that the funnel is converting slowly, would undercut the argument that AI demand is a durable tailwind. Management also flagged that some large dark fiber deals could slip from the fourth quarter into early 2027, so any update on timing will be closely parsed.
The consumer side is where the narrative is most vulnerable. Kinetic fiber ARPU fell 2.6% year over year in the second quarter after rising 5% in the prior two periods, and management guided to another low-single-digit decline in the third quarter, blaming cable convergence bundles, Starlink and retention spending. A decline within that guidance would be acceptable; a deeper drop would cast doubt on the promised return to 2% to 3% growth in the fourth quarter. Investors should also check whether the build engine keeps pace after record homes passed of 141,000 and record net fiber adds of 38,000, since higher capital spending, now guided to about $1.525 billion consolidated, only makes sense if subscriber growth follows. Progress on using the second Kinetic ABS deal to retire up to $500 million of secured debt would help ease balance sheet concerns.
Sentiment has soured markedly, swinging from mildly bullish before the last report to firmly bearish now. The chart tells the same story. At $5.06, shares trade far below the 200-day moving average of $9.47 and only a few percent above the post-earnings low of $4.82, a world away from the $10 to $13 range of the prior quarter. That washed-out setup lowers the bar, but it also signals that investors want proof rather than promises.
Ultimately, the report comes down to whether fiber infrastructure momentum and a stabilizing consumer ARPU outlook can justify heavier spending. If bookings stay strong and management reaffirms its raised targets, the gap between operations and the share price becomes hard to ignore. If ARPU erodes further or deal slippage widens, the market's skepticism will look well founded.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Oct-27 | |
| Oct-13 | |
| Oct-13 | |
| Oct-12 | |
| Oct-07 | |
| Oct-05 | |
| Oct-05 | |
| Oct-01 | |
| Sep-28 | |
| Sep-16 | |
| Sep-15 | |
| Sep-14 | |
| Sep-08 |
