Turning Point Brands Must Show Its Modern Oral Spending Spree Can Start Paying Back
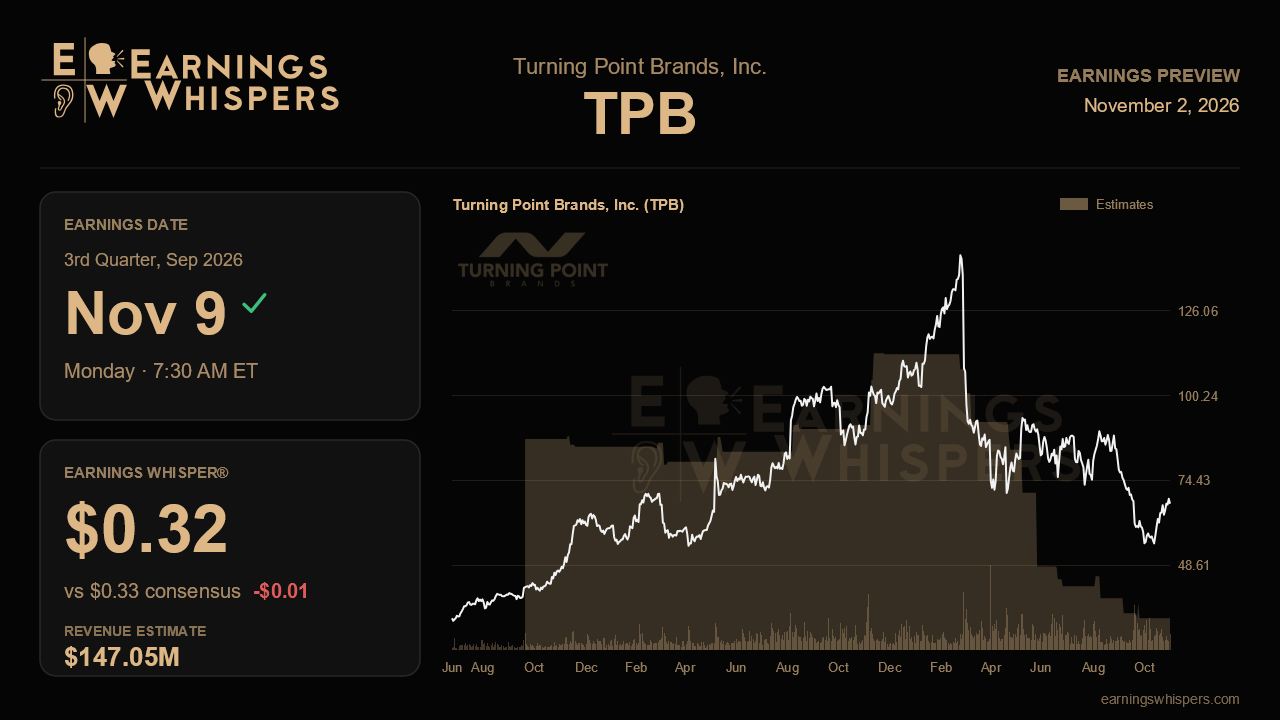
Turning Point Brands enters its third-quarter report with a story that has split in two. Its Modern Oral nicotine pouch business is growing at a pace few staples companies can match, and management has raised its full-year outlook for that segment twice in a row. Yet the cost of chasing that growth pushed adjusted EBITDA margin down to 11% last quarter, and the stock has since fallen about 22% while the broader market was roughly flat. The question for the November 9 report, due before the open, is whether the spending is beginning to show leverage or whether margins still have further to fall.
The Street is looking for non-GAAP earnings of $0.33 per share on revenue of $147.1 million. Sales would be up 23.6% from a year ago, which is strong growth, but only about $4 million above the $143 million reported last quarter. That modest sequential step is worth noticing, because Modern Oral alone added $16 million in net sales from the first quarter to the second. A soft consolidated figure would suggest either that pouch growth is cooling or that ZigZag and Stoker's are dragging harder. On earnings, the year-ago figure of $1.13 makes a straight comparison unhelpful, but the jump from last quarter's $0.08 implies that analysts expect spending to ease relative to sales. The whisper number of $0.32 sits a penny below consensus, a small gap that points to mild caution rather than real doubt.
Management's own targets set useful markers. Modern Oral net sales guidance of $260 million to $270 million, after $120 million in the first half, implies roughly $70 million to $75 million per quarter for the rest of the year. A third-quarter result near or above the top of that pace would support the case for a third straight raise. Coming in flat with the second quarter's $68 million would suggest the earlier raises were front-loaded. Adjusted EBITDA guidance, held at $70 million to $90 million even as revenue estimates rose, implies about $29 million to $49 million for the second half after roughly $41 million through June. Anything near the second quarter's $15 million would put the low end of that range in play and would likely matter more to the stock than any revenue beat.
Several of last quarter's newer catalysts deserve updates. The sales force was on pace to grow by about half this year, and management argued that future growth would not need matching increases in SG&A, which jumped $21 million in a single quarter to $77 million. Evidence that SG&A is leveling off while pouch sales keep rising would be the clearest sign that this argument holds. Investors should also look for progress on the phased European rollout, the in-store UFC co-branding, and the US manufacturing plant slated for a year-end launch, pending regulatory approval, with a goal of about 70% gross margin at scale. Any slip in that timeline would push back the most direct fix for margins. Stoker's gross margin, down 600 basis points on heavier chain discounting, and ZigZag's stabilization are smaller items, but together they show whether the legacy businesses can keep funding the pouch push.
Sentiment remains bearish, though slightly less so than before the last report, which fits a market that has already marked the shares down. At $67.31, the stock trades well below its 200-day moving average of $86.81 and is closer to the bottom of its post-earnings range of $54.17 to $91.94. That leaves room for relief if the numbers cooperate. It also shows how little benefit of the doubt investors are giving on profitability.
Growth is not what is in doubt. Unless pouch momentum stalls sharply, the report will turn on whether third-quarter EBITDA shows that the margin trough is behind the company. Without that, investors will have little reason to look past the cost of the growth.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| Oct-26 | |
| Oct-07 | |
| Sep-21 | |
| Sep-21 | |
| Sep-15 | |
| Sep-04 | |
| Sep-04 | |
| Aug-31 | |
| Aug-20 | |
| Aug-18 | |
| Aug-12 | |
| Aug-04 | |
| Aug-04 |
