Target Hospitality Must Show Its Data Center Ramp Is Reaching The Income Statement
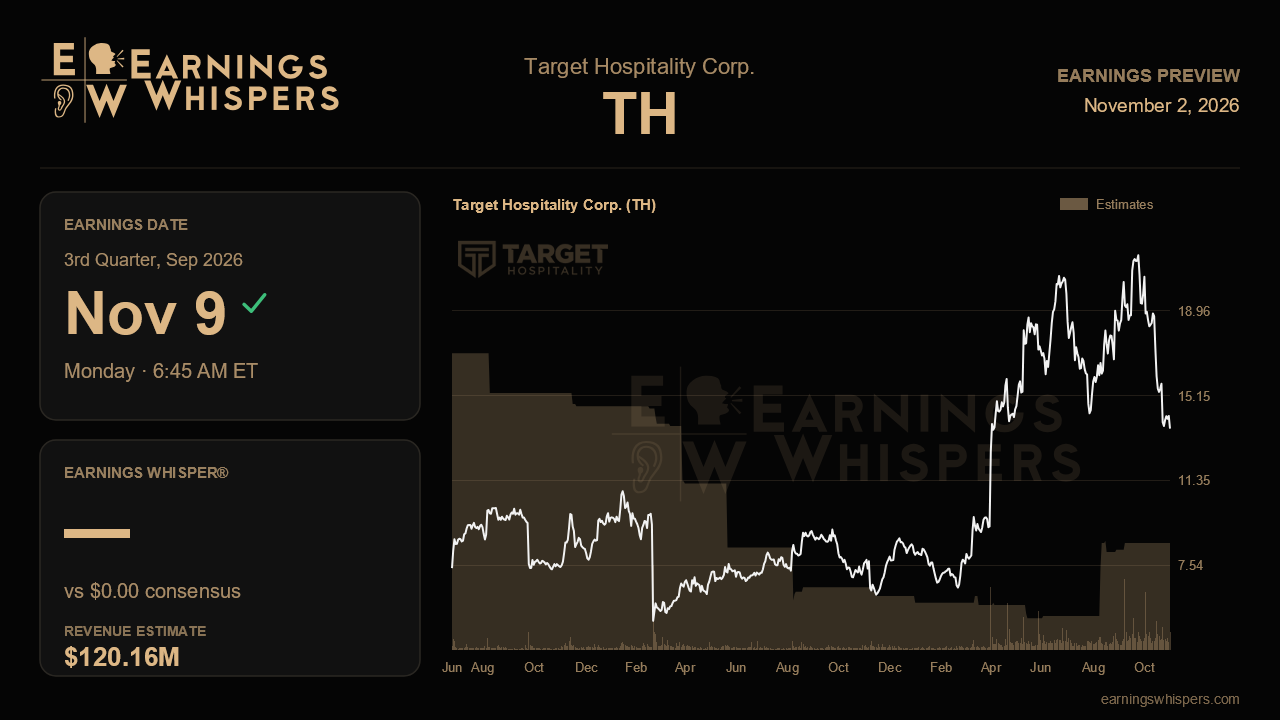
Target Hospitality heads into its third-quarter report with an unusual disconnect. Management has raised its full-year outlook three times in a row, nearly quadrupled its borrowing capacity and lifted its 2027 exit targets to levels that would reshape the company. Yet the stock has fallen 12% since the last report, trailing the S&P 500 by almost 10 percentage points. The quarter's job is to show that the big contracts signed this year are converting into revenue and margin on schedule, not just into capital spending.
The Street is looking for revenue of about $120.2 million, up 20.9% from a year ago and a sharp step up from the $85.5 million posted last quarter. Consensus calls for breakeven earnings per share, compared with a loss of 9 cents in the second quarter and a 1-cent loss a year earlier. That sequential leap matters because the company's raised guidance of $410 million to $420 million in 2026 revenue depends on a heavily back-loaded second half. Full-year consensus of roughly $376 million still sits below the bottom of that range, suggesting some estimates have not caught up with the latest raise. A quarterly figure well above $120 million would help close that gap; anything near the second-quarter pace would raise doubts about the trajectory.
The core of the story is the workforce hub business tied to large AI data center construction. That segment generated about $36 million last quarter, up 142% from a year earlier, with average utilized beds topping 4,000, and management now expects it to exceed half of consolidated revenue for the year. Segment margins near 53.5% were running ahead of plan, and consolidated adjusted EBITDA margins expanded by more than 700 basis points from the first quarter. Validation this time would mean further gains in utilized beds, margins holding at or above that level as new communities open, and progress toward the adjusted EBITDA guide of $85 million to $95 million. Investors should also look for the definitive agreements management said it was finalizing. The tone shifted last quarter from advanced discussions to finalizing multiple deals, so a report without new awards, or at least concrete updates on the Uintah County, Wyoming project and expansion into the Rockies and Midwest, would make that language look premature.
The offsets are well understood but still relevant. The legacy HFS South business has stalled at around $33 million a quarter, and management is weighing redeploying that capacity, which could be a useful source of beds for new hubs or a sign of further erosion. The government segment is absorbing $5 million to $7 million of transitional costs spread across the second and third quarters, so some margin noise there is expected. Capital spending guidance has ballooned to $490 million to $510 million, and net leverage, just 0.6x last quarter, is expected to rise before falling below 3x by the end of 2027. The more than $100 million in customer advances helped fund that build, and continued strength in operating cash flow would ease concerns about the balance sheet.
Sentiment has warmed modestly, edging up to 14.6% bullish from 10.8% ahead of the prior report, but the price action tells a more skeptical story. At $13.67, shares sit below the 200-day moving average of $14.73 and near the bottom of a post-earnings range that stretched from $13.01 to $21.76, having surrendered most of the gains that followed the last report. That positioning lowers the bar for a relief move if execution holds, but it also signals that the market wants proof rather than promises.
The verdict likely hinges on whether the third quarter delivers the revenue step up the guidance implies while keeping workforce hub margins intact. If that happens alongside fresh contract wins, the guidance raises look earned. If revenue lags while spending climbs, the market's recent doubts will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 15 hours | |
| Sep-14 | |
| Sep-10 | |
| Sep-08 | |
| Sep-08 | |
| Aug-26 | |
| Aug-26 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Aug-07 | |
| Aug-05 | |
| Aug-03 | |
| Jul-27 |
