TG Therapeutics Tests Briumvi Momentum Against Seasonal Lull As Stock Nears Breakout
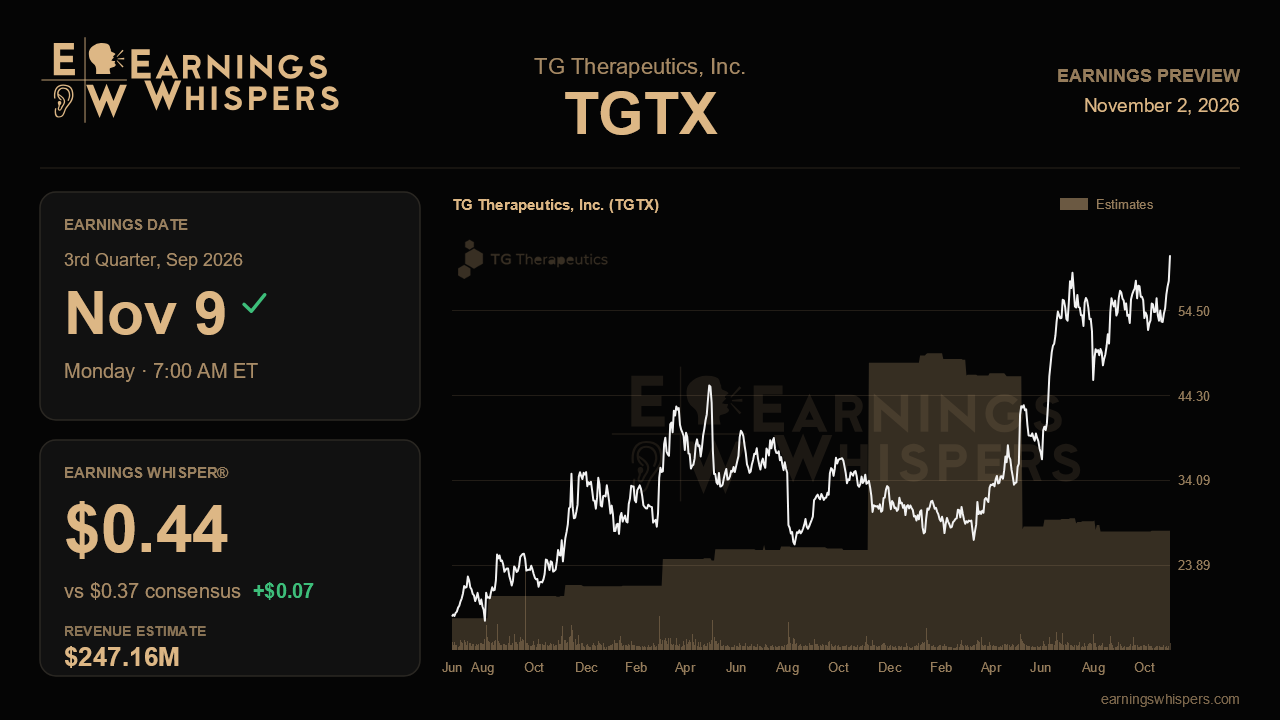
TG Therapeutics heads into its third-quarter report with a peculiar challenge: management has already told investors that this quarter should look sluggish, yet the stock has rallied as if the opposite were true. Last quarter, the company said seasonal patterns would keep sales roughly flat from the second quarter to the third, with the fourth quarter carrying most of the second-half growth. The market has since bid the shares up nearly 20%. The question on November 9 is whether a deliberately muted quarter can still show enough underlying strength in Briumvi, its multiple sclerosis infusion, to justify that confidence.
The Street expects earnings of $0.37 per share on revenue of $247.2 million, before the open. That revenue figure would represent growth of roughly 53% from a year ago, but only about 3% above the $240.3 million reported last quarter. In other words, analysts are penciling in slightly better than the flat sequential result management described. The earnings whisper of $0.44 sits meaningfully above consensus, suggesting the more aggressive crowd expects either stronger sales or lighter expenses. The projected 85% drop in year-over-year EPS looks alarming but mostly reflects an unusually large $2.43 figure in the year-ago quarter rather than any deterioration in the business.
Guidance frames the bar. TG has raised its full-year outlook twice this year, lifting global revenue guidance to about $950 million and U.S. Briumvi guidance to $890 million to $905 million, up from the $825 million to $850 million originally set. Consensus for the year, at roughly $947.5 million, sits essentially on management's number, so the Street is not demanding a beat-and-raise to stay on track. Simple math helps here: with $423 million of U.S. sales booked in the first half, and management targeting an exit run rate above $250 million a quarter, a third-quarter U.S. figure anywhere near the $228 million posted last quarter keeps the plan intact. A clear step down would raise questions about whether the fourth quarter has to do too much heavy lifting. Another guidance increase, even a modest one, would signal that seasonality is milder than feared.
Profitability is the bigger swing factor for the EPS line. Last quarter's $0.05 was weighed down by about $55 million of manufacturing charges tied to the subcutaneous formulation and a secondary supply source, out of roughly $100 million expected for the full year. That leaves around $45 million to land in the back half, and how much hits this quarter could easily move results by several cents per share. Operating expense guidance also crept up to $350 million to $400 million on direct-to-consumer advertising and pipeline spending. Steady gross margins near 83% overall would be reassuring; any slippage would be harder to explain away.
Beyond the numbers, management pointed to rising share among newly treated patients and better-than-expected persistence as its strongest leading indicators. Commentary that confirms both trends, along with early read-throughs from the expanded consumer campaign, would validate the narrative. Investors may also look for the promised second-half update on Azercel, the cell therapy program now enrolling in myasthenia gravis and other autoimmune conditions, and for progress toward a mid-2027 launch of the simplified single-dose initiation regimen.
Sentiment has warmed considerably, with the bearish reading easing to 9.4% from 25.9% last quarter, and the stock at $61.18 is within about 1% of its post-earnings high, above the prior quarter's peak and far above its 200-day average of $43.74. That positioning leaves less room for a soft print. Ultimately, the report hinges on one thing: whether Briumvi demand holds firm through a seasonally weak quarter, keeping the $250 million exit rate and the path to a $1 billion U.S. year in 2027 credible.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 11 hours | |
| Oct-31 | |
| Oct-30 | |
| Oct-23 | |
| Oct-23 | |
| Oct-21 | |
| Oct-18 | |
| Oct-12 | |
| Oct-08 | |
| Sep-22 |
Dow Jones Futures: Nasdaq Hits New High; Sandisk, Micron Trigger Buy Signals
TGTX
Investor's Business Daily
|
| Sep-17 | |
| Sep-16 |
TG Therapeutics Makes A Bullish Move Amid Ongoing Roche Rivalry
TGTX +5.30%
Investor's Business Daily
|
| Sep-10 | |
| Sep-03 |
