WhiteHorse Finance Must Show Income Can Again Cover Its $0.25 Payout
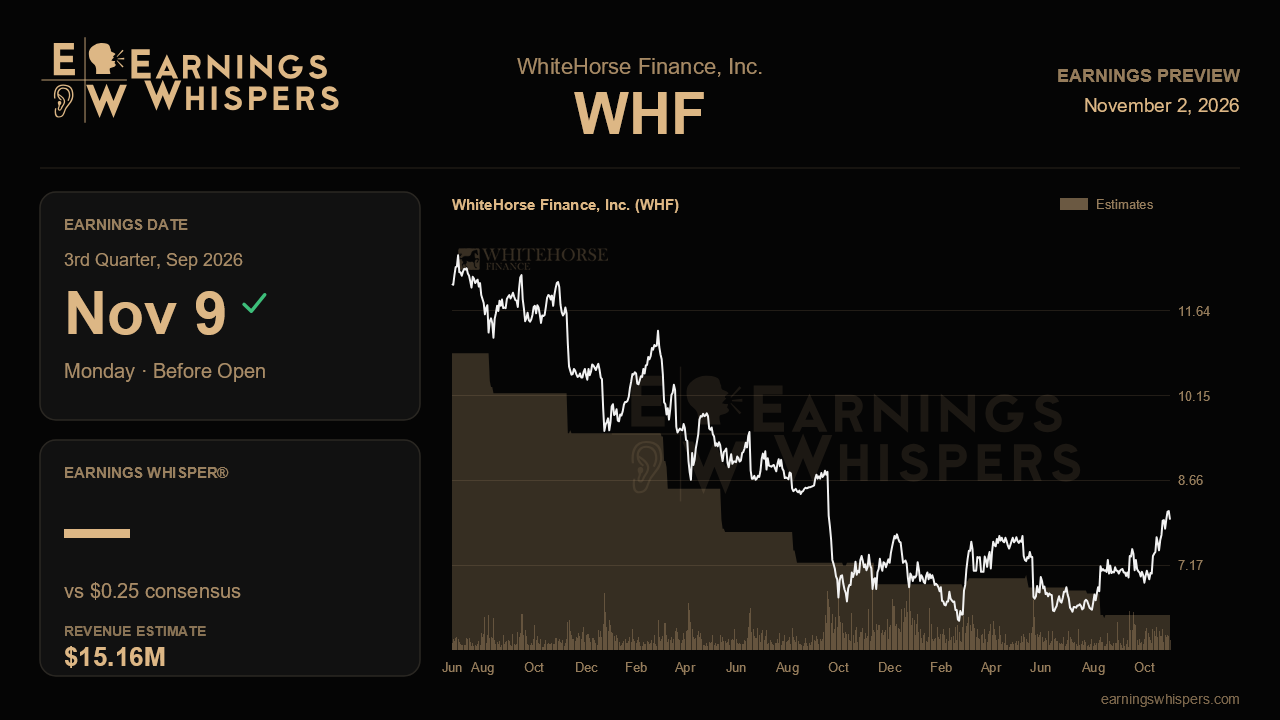
WhiteHorse Finance heads into its next report with a story that has improved on paper but not yet in the income statement. Last quarter, net asset value per share rose for the first time in several periods and portfolio marks swung to a solid gain, helped by a large markup on the Chase/Starco equity stake. Yet the recurring earnings engine kept shrinking, and net investment income fell to about $0.22 a share, roughly three cents short of the $0.25 base distribution. The upcoming release is essentially a test of whether that gap was a low point or a trend.
The Street is betting on a recovery. Consensus calls for EPS of $0.25 on revenue of $15.2 million, up from $0.22 and $14.4 million last quarter. Measured against a year ago, though, this is still a contracting business: EPS is expected to slip about 3.9% and revenue to fall roughly 14.3% from $17.7 million. In other words, analysts expect sequential repair, not growth, and their number lands exactly on the distribution. That makes the threshold unusually clean. A print at or above $0.25 would suggest the payout is earned again, while another shortfall would revive questions about dividend coverage just a year after the base distribution was reset from $0.385.
Management handed investors the ingredients for that rebound. The Outward Hound restructuring, completed after last quarter closed, put WhiteHorse in majority control and returned the term loan to accrual, which should add directly to interest income. The incentive fee waiver, reducing the rate to 17.5% from 20%, was extended through this quarter, lending further support. The harder pieces are the ones that drove the recent slide: joint venture income, which fell to $3.2 million from $3.8 million two quarters earlier, fee income that dwindled to just $0.1 million, and a portfolio yield that drifted down to 8.8%. If the revenue increase comes mostly from Outward Hound alone while those lines keep eroding, the improvement may prove thin.
The bigger constraint is capacity. Management said only about $10 million of room remained on the balance sheet and the joint venture was fully utilized, with leverage at target and buybacks paused. That matters because new lending conditions look attractive, with spreads roughly 50 basis points wider, lower leverage on new deals and stronger lender protections. WhiteHorse simply cannot lean into that environment without recycling capital. Here the equitized workouts become central. Management pointed to possible liquidity events at Chase and Naviga at values bankers suggested exceed current marks, plus a potential PlayMonster sale later. Any concrete progress, along with an update on the non-accrual book, still at 3.6% of fair value, and the Camarillo and New Cycle sale processes, would help show how the freed cash could rebuild income. Clarity on how the $85 million of unsecured notes flagged last quarter was handled, and at what cost, also bears on future earnings power.
The market has already moved ahead of the evidence. Shares have climbed 17.6% since the last report while the S&P 500 slipped 2.4%, a 20-point outperformance. At $7.97, the stock sits well above its 200-day average near $7.01 and within about 3% of its post-earnings high of $8.19, putting a breakout in view. Sentiment remains slightly bearish but has softened noticeably from the prior quarter. Even after the run, the stock trades at a steep discount to last reported NAV of $11.77, which reflects lingering doubt about earnings quality.
The core question is whether net investment income can return to covering the $0.25 distribution on a recurring basis rather than with one-time help. Hitting consensus with Outward Hound and the fee waiver doing the work would validate last quarter's turn, but a durable rerating likely requires signs that monetizations are close enough to restart deployment. Without that, the rally rests largely on marks rather than earnings.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-22 | |
| Oct-14 | |
| Oct-09 | |
| Sep-21 | |
| Aug-10 | |
| Aug-10 | |
| Jul-29 | |
| Jul-28 | |
| Jun-29 | |
| May-07 | |
| May-07 | |
| Apr-23 | |
| Mar-02 | |
| Mar-02 |
