Ameresco's Record Data Center Backlog Meets A Skeptical Market As Cash Conversion Takes Center Stage
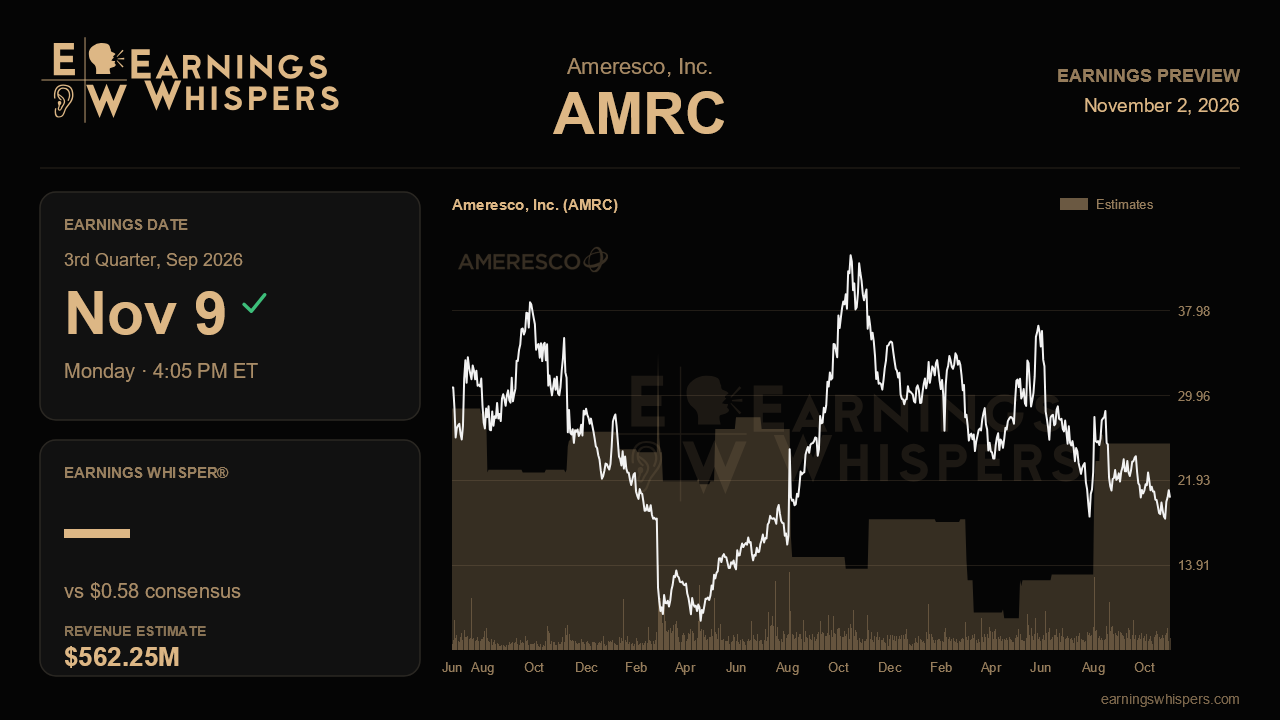
Three months ago, Ameresco delivered what management called a transformational quarter: a record $1.8 billion of new awards, $1.2 billion of it tied to data centers, an awarded backlog that jumped 65% to $4.4 billion, and a raised earnings outlook. The market's response since then has been brutal. The shares have fallen 36.4% while the S&P 500 has barely moved, leaving the stock at $20.31, well below its 200-day moving average of $26.53 and only about 11% above its post-report low of $18.27. That gap between narrative and price is what makes the third-quarter report, due after the close on November 9, so consequential.
The Street expects earnings of $0.58 per share on revenue of $562.3 million. That implies EPS growth of roughly 66% from $0.35 a year ago, set against revenue growth of a far more modest 6.9%. The mismatch matters. Much of the expected earnings lift reflects margin improvement and a new accounting policy for transferable tax credits, which management said now delivers a tax benefit rate of 25% to 40%. Investors should therefore separate operating progress from tax mechanics when judging any beat. The quarter also carries real weight for the full year: $0.58 would represent nearly half of the $1.25 midpoint of management's reaffirmed $1.15 to $1.35 EPS range. Consensus of $1.24 on revenue of $2.10 billion sits almost exactly at the midpoint of guidance on both lines, so the Street is neither stretching nor hedging. A soft third quarter would quickly push the year toward the low end.
Margins are the first operational test. Gross margin leapt to 17.7% in the second quarter from 14.1% in the first, a step-up of about 360 basis points that helped justify the guidance raise. Holding something close to that level would suggest the improvement reflects project mix and the growing contribution of higher-margin recurring businesses, where energy asset revenue rose 21% and operations and maintenance revenue climbed 29%. A slide back toward the mid-teens would make last quarter look like an outlier and undercut confidence in the earnings trajectory.
Cash is the second, and perhaps more pressing, test. Adjusted operating cash flow weakened last quarter on working capital and billing timing after a healthy first quarter, and management named cash conversion a key second-half priority. For a capital-intensive developer financing a growing fleet of owned assets, including the Napanee battery storage project and the Greek solar portfolio, evidence that working capital is reversing would ease a significant concern. Another quarter of absorption would invite harder questions about the balance sheet, even with $471 million of new financing and the $400 million HASI joint venture in hand.
The data center story needs maintenance rather than fireworks this quarter. Management was clear that awards take six to 24 months to become signed contracts and up to three years to build, so meaningful revenue arrives in 2028 to 2030. What would validate the thesis now is progress on converting awards into contracts, early movement on long-lead equipment orders, and any update on the roughly five additional opportunities management hinted could follow, with current awards potentially growing toward $2 billion. Silence on conversion, or signs of permitting, gas-supply or equipment delays, would feed the skepticism already priced into the stock.
Sentiment remains mildly bearish, though slightly less so than before the last report, suggesting expectations are subdued rather than hostile. With the shares near the bottom of their range, the bar for a positive reaction may be lower than the strong underlying numbers imply. The deciding issue is whether Ameresco can show that last quarter's margin and backlog gains are durable and, crucially, that they are starting to turn into cash.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-14 | |
| Oct-13 | |
| Oct-08 | |
| Oct-07 | |
| Sep-21 | |
| Sep-03 | |
| Aug-31 | |
| Aug-25 | |
| Aug-19 | |
| Aug-13 | |
| Aug-04 | |
| Aug-04 |
