Bain Capital Specialty Finance Faces A Dividend Verdict As Credit Stress Tests Its Payout
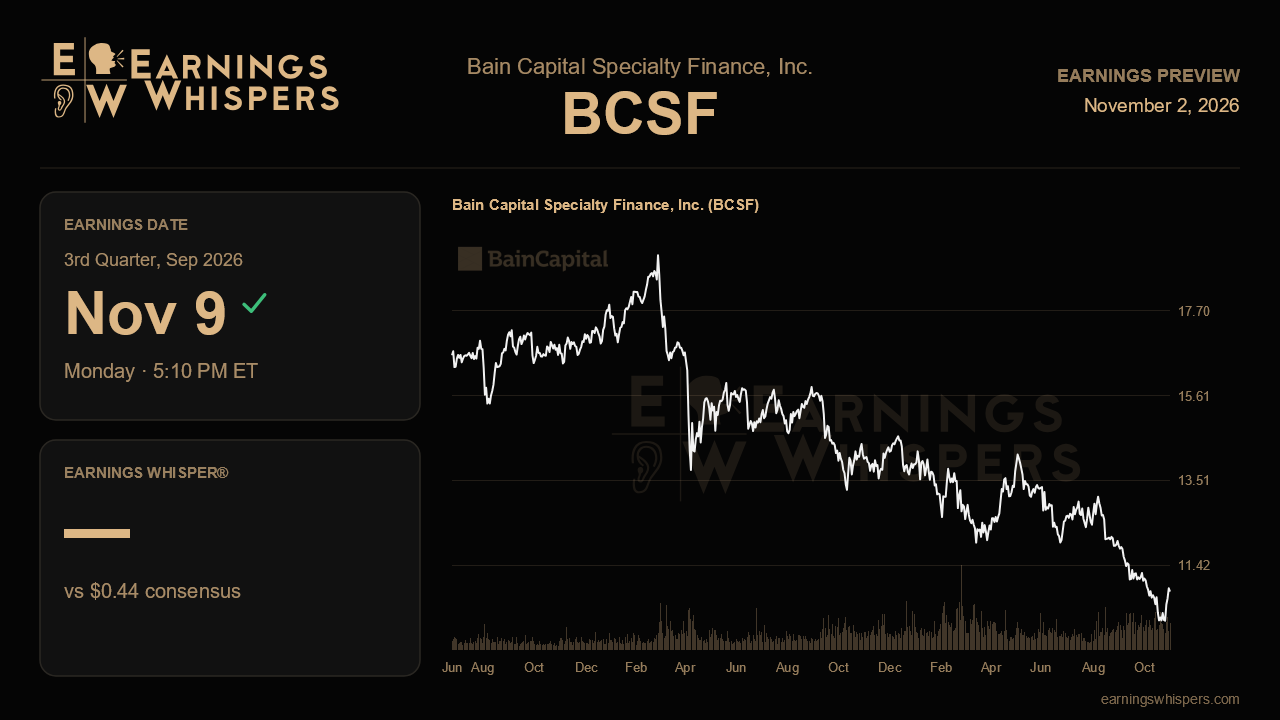
The number that matters most when Bain Capital Specialty Finance reports after the close on November 9 may not be earnings per share at all. Last quarter, management dropped its familiar assurance that the $0.42 quarterly dividend could be maintained and said instead that it would reevaluate the payout in the coming quarters. At the same time, non-accrual loans more than tripled. For a business development company whose shareholders own it largely for income, that combination turns this report into a referendum on the dividend and on how deep the credit problems run.
The Street is looking for net investment income of $0.44 per share, matching last quarter and down about 2.2% from $0.45 a year ago. That is a flat-to-slightly-shrinking profile, not a collapse, and at that level the $0.42 dividend would still be covered at roughly 105%. No formal guidance accompanied the last report, so the consensus effectively assumes the income base has stopped eroding. That is a meaningful assumption. Total investment income has declined for four straight quarters, falling to $62.3 million from $67.2 million a year earlier, as joint venture income softened and newly troubled loans stopped paying. Portfolio yield at fair value has slipped to 10.4% from 11.2% over the same span. Holding $0.44 requires those pressures to level off.
Credit is the swing factor. Non-accruals jumped to 2.2% of the portfolio at fair value and 3.2% at cost after two companies were added, compared with a stable 0.6% to 0.8% range over the prior three quarters. The watchlist also crept up to 6% from 5%. If those figures stabilize or the two new problem loans are resolved without further markdowns, last quarter can be framed as a contained setback. Another increase, especially with additional names migrating from the watchlist, would suggest a broader deterioration and further pressure on net asset value, which has fallen for four consecutive quarters to $16.65 per share, a cumulative decline of roughly $0.75.
There are offsetting positives worth tracking. New origination spreads widened to about 570 basis points, and management described a meaningful pickup in deal activity late in the quarter, with M&A and buyout volume expected to improve. Liquidity rose to $806 million, the revolving credit facility was extended to 2031 with the credit adjustment spread removed, and the company planned to retire unsecured notes maturing in October, which should trim funding costs. Evidence that new loans at wider spreads are offsetting the yield drag would support the income outlook. The constraint is leverage, already at the upper end of the target range at 1.22 times net, which limits how aggressively the company can grow into that better lending environment.
The market has delivered a harsh verdict in advance. Shares have dropped 17.8% since the last report, trailing the S&P 500 by more than 15 percentage points, and at $10.77 they sit well below the 200-day moving average of $12.46 and not far above the post-earnings low of $10.00. That price is roughly 65% of the last reported net asset value, a discount implying investors expect further credit losses or a dividend cut. Sentiment has swung from marginally bullish ahead of the previous report to firmly bearish now. Such pessimism lowers the bar for relief, but it does not make relief likely on its own.
Ultimately, the report hinges on whether management can show that credit losses have plateaued and that the income base supports the payout. Spillover income has been drawn down to about $1.26 per share, giving the board some cushion, but cushions are not permanent. A stable non-accrual rate, steady net asset value and a clear statement on the dividend would go a long way toward rebuilding confidence. Further credit slippage paired with a reduced payout would confirm the market's darkest read.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-26 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Jul-23 | |
| May-12 | |
| May-11 | |
| May-11 | |
| May-04 | |
| May-01 | |
| Apr-28 | |
| Feb-27 | |
| Feb-27 | |
| Feb-26 |
