Credicorp Brings Raised Targets Into An El Nino Provisioning Test As Shares Hug Lows
Three months ago Credicorp delivered one of its most confident outlooks in years. It lifted its medium-term return on equity target to about 22%, pushed 2026 loan growth guidance to roughly 12%, upgraded fee income to the high teens, and steered net interest margin toward the top of its range. The market has not bought it. Shares have fallen 6.6% since that report, trailing the S&P 500 by about four percentage points. The third-quarter release on November 9 is the first real chance to show that the upgrades can outrun a newly introduced El Nino provisioning bill.
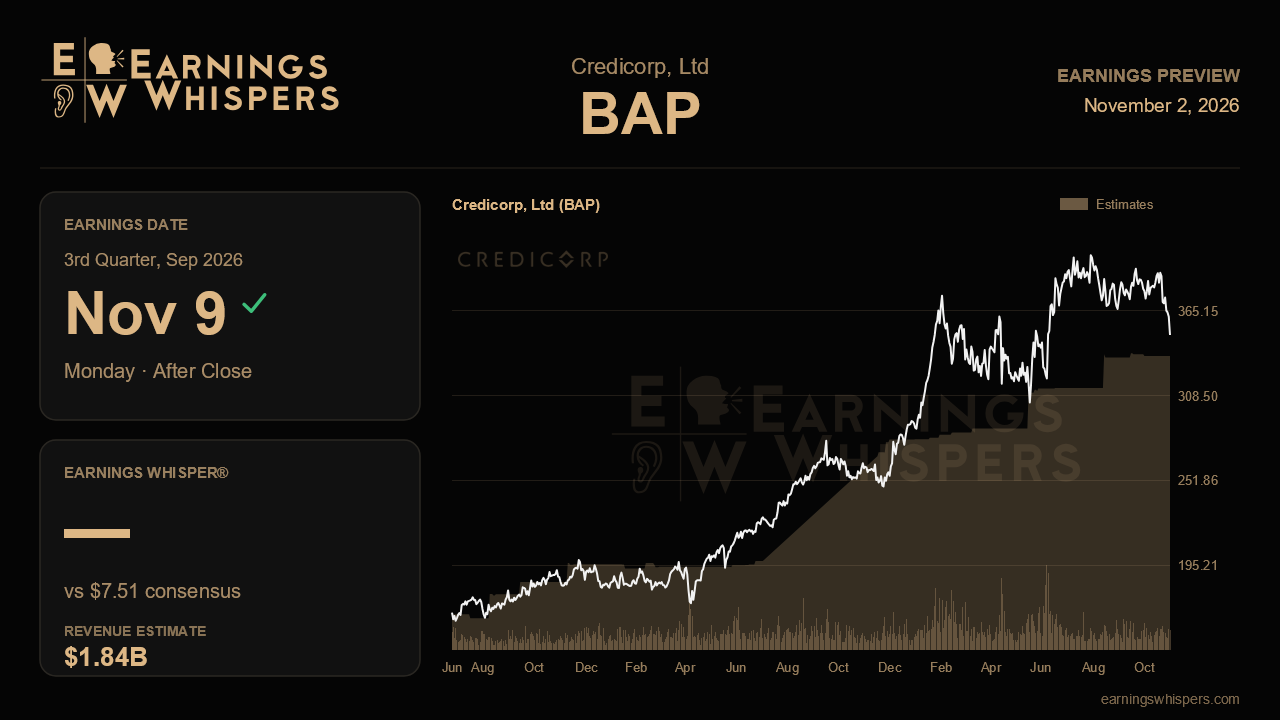
The Street expects earnings of $7.51 per share, up 21.7% from $6.17 a year ago and modestly above the $7.29 posted last quarter. That is strong growth for a bank of this scale. Consensus revenue of $1.84 billion implies an 8.6% year-over-year decline and a sharp drop from $2.17 billion in the second quarter. That figure is hard to square with double-digit loan growth and accelerating fees. Investors are better served judging the quarter on loan volumes, margins, fees and cost of risk than on the headline top line.
The guidance progression is the core of the bull case, and it raises the bar. Loan growth guidance has climbed from about 6.5% a year ago to 8.5% and now 12%, while consolidated loans grew 13.1% in the second quarter after 8.2% in the first. Confirmation would mean loans holding near that pace, with wholesale lending continuing to recover on the back of strong private investment and business confidence at its highest since 2013. Fees need to be tracking toward high-teens growth, and margins should stay firm under management's higher-for-longer rate view. Yape, the digital platform whose loan book quadrupled to S/1.8 billion and now contributes nearly 9% of risk-adjusted revenue, should keep gaining share of the earnings mix. Any slippage in these lines would suggest last quarter's raise was a peak rather than a new floor.
The swing factor is credit. Credicorp booked about S/106 million of extra El Nino provisions in the second quarter, lifting cost of risk to 1.9% from 1.3%. Roughly 9% of loans are directly exposed, and the heaviest impact is expected in early 2027. Management promised a further reassessment in September or October, so the third-quarter numbers or accompanying commentary should reveal whether the climate risk is staying contained or growing. A cost of risk that rises but stays within guidance would be consistent with the plan. A large second top-up, or warnings that the severe scenario of slower 2027 loan and fee growth is becoming more likely, would challenge the improved tone. Softer insurance underwriting and the handoff of the CFO role to Ignacio Belaunde add smaller sources of noise.
Sentiment has cooled to 35.7% bullish from 46.5% ahead of the prior report, and the chart reflects that caution. At $348.96, the stock sits below its 200-day moving average of $358.89 and barely above its post-earnings low of $346.54, well off the $395.32 high. Good operating news paired with a discounted share price can be a constructive setup, though a stock pinned near support is also vulnerable if the provisioning picture darkens.
With an investor day on November 17, management may hold back strategic detail. The central question for this report is simpler: can loan growth, fees and margins deliver enough earnings power to keep the full-year ROE target of about 19.5% pointed upward while El Nino provisions rise? If yes, the upgraded narrative holds and the stock's recent discount looks overdone. If credit costs start eating the upside, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-27 | |
| Oct-19 | |
| Sep-16 | |
| Aug-27 | |
| Aug-26 | |
| Aug-14 | |
| Aug-14 | |
| Aug-10 | |
| Jul-31 | |
| Jul-23 | |
| Jul-06 | |
| May-19 | |
| May-15 | |
| May-15 |
