Adeia Misses Badly And Cuts 2026 Revenue Outlook As Big Media Deals Slip, Putting Q4 Credibility On The Line
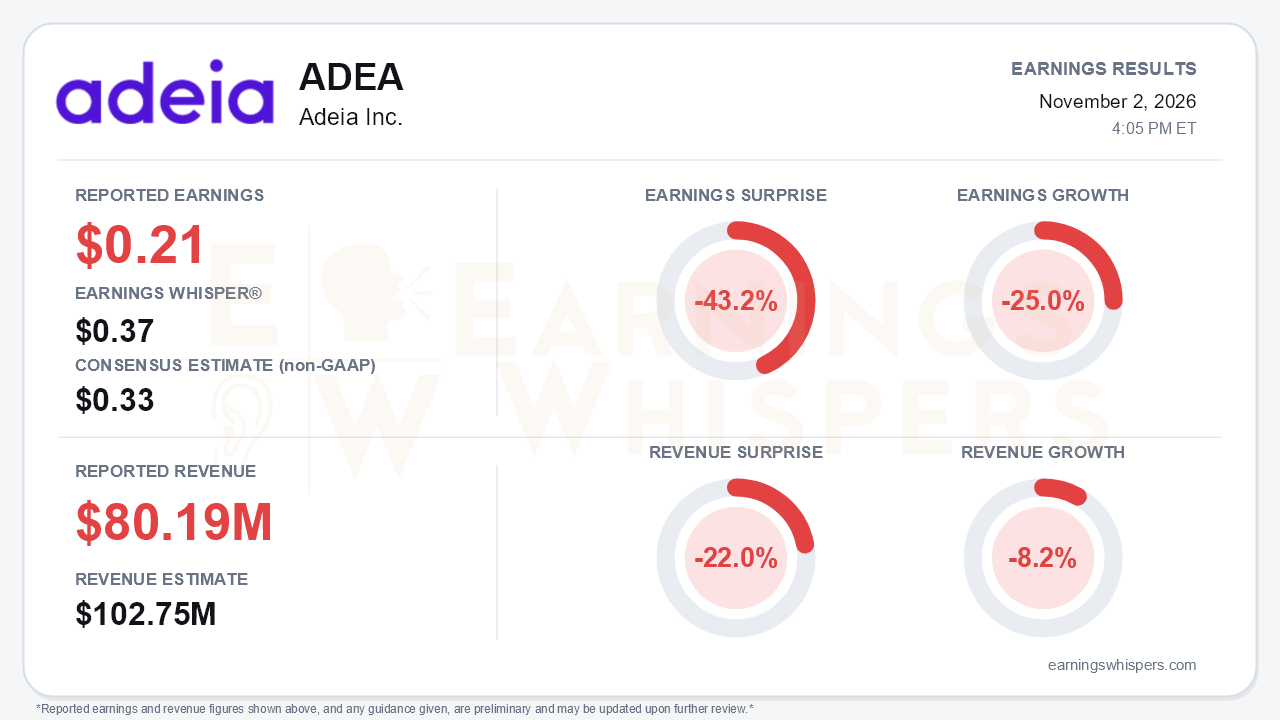
Adeia's third quarter was a clear miss on both lines and came with lower guidance. Non-GAAP EPS of $0.21 fell 43.2% short of the $0.33 consensus and well below the $0.37 Earnings Whisper. Revenue of $80.19 million missed the $102.75 million consensus by 22.0%. Earnings fell 25.0% from a year ago, and revenue fell 8.2%. The miss itself matters less than what it says about timing and credibility. Management cut its full-year 2026 revenue range by $20 million at both ends, to $375-$415 million, because a handful of large, complex media deals slipped. That range had been held steady through the prior three calls, and in the second quarter management had said its internal forecast matched consensus and that the fourth quarter would ramp.
The trajectory is the problem. Quarterly revenue has stepped down from $104.8 million in Q1 to $96.1 million in Q2 and $80.2 million in Q3. Nine-month revenue of $281.1 million is still ahead of last year's $260.7 million, but the third quarter turned that growth negative on a year-over-year basis. Profitability fell faster than revenue because costs kept climbing. Total GAAP operating expenses rose to $71.1 million from $60.3 million a year ago, with litigation expense up to $7.2 million. Adjusted EBITDA fell to $36.9 million, a 46% margin, compared with 59% in Q2 and 60% in Q1. On a GAAP basis, EPS shrank to $0.02 from $0.08. Cash generation was weak too: operating cash flow was just $5.1 million, against $54.6 million in Q2, and the company bought back no stock in the quarter.
The operating picture is not uniformly weak. Deal activity held up, with eight license agreements signed, compared with six in Q2. Four of those were with new customers. The quarter included multi-year renewals with Charter, the largest U.S. Pay-TV provider, and with TCL. Adeia also signed a long-term e-commerce license with Fanatics, building on the Q2 RPX consortium deal, plus new social media and consumer electronics licensees. Recurring revenue was roughly $76 million of the quarter's $80 million. Semiconductor revenue edged up to about $15 million. Still, the call produced no raised metrics. Non-pay-TV recurring revenue growth slowed to 48% from 54% in Q2.
The guidance cut deserves scrutiny on both sides of the ledger. Management lowered non-GAAP operating expense guidance to $176-$180 million from $184-$192 million, which allowed it to hold its roughly 55% adjusted EBITDA margin target despite lower revenue. Part of that reduction, however, reflects court delays pushing litigation spending out, not structural savings. EchoStar/DISH emerged from bankruptcy in October, which unfreezes that litigation and could move costs into 2027. Management insists the slippage is a matter of "when, not if" and says it is targeting the $415 million high end. Based on nine-month revenue of $281.1 million, that would require roughly $134 million in the fourth quarter, far above any quarter this year. The widened range is a candid acknowledgment that year-end deal timing could easily disappoint again. Analyst pushback on the call about credibility showed that investors are no longer extending the benefit of the doubt.
The longer-term story was preserved rather than advanced. Management reaffirmed the $600 million long-term revenue target, which was raised from $500 million only last quarter. It also framed hybrid bonding as a 2027-2029 driver: logic licensing in 2027-28, and memory renewals with the top three manufacturers in 2028-29, aligned with 16- and 20-layer HBM adoption. New CEO Dipti Vachani, formerly of Arm, brings semiconductor credibility. But her arrival also opens a transition and strategy-review period, and the semiconductor upside sits years out while the media licensing engine is stumbling now.
The market had already turned skeptical before the report. As of October 30, shares at $21.44 were down 13.5% from the open after the August report. They were 16.2% below the 200-day moving average and 33.4% below the $32.20 inter-earnings high, which was set on the first trading day after the prior release. That post-report spike has been fully unwound. The stock sat just 5.5% above its October 16 low of $20.33. Investor sentiment remained negative but improved modestly, from -0.17 to -0.09. That suggests some stabilization in expectations rather than real optimism, and it leaves room for disappointment given the size of this miss. Price and AVWAP trend readings remain negative.
The bottom line is that Adeia delivered a deep miss and broke a guidance range it had defended all year. It is now asking investors to trust an outsized fourth quarter and a 2027-2029 hybrid-bonding ramp under a brand-new CEO. Healthy deal counts, marquee renewals and a reaffirmed $600 million target keep the long-term thesis intact. However, falling quarterly revenue, a 14-point EBITDA margin drop from Q1, thin cash flow and partly deferred cost savings give bears legitimate ammunition. Until delayed deals actually close, credibility is the stock's binding constraint.
Read our earnings preview for Adeia Inc.: https://www.earningswhispers.com/article/ADEA/21360
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 4 hours | |
| Oct-26 | |
| Oct-22 | |
| Oct-19 | |
| Oct-15 | |
| Oct-11 | |
| Oct-05 | |
| Sep-28 | |
| Sep-16 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 |
