Emergent BioSolutions Narrowly Beats On EPS, But A Second Straight Revenue And EBITDA Guidance Cut Defines The Quarter
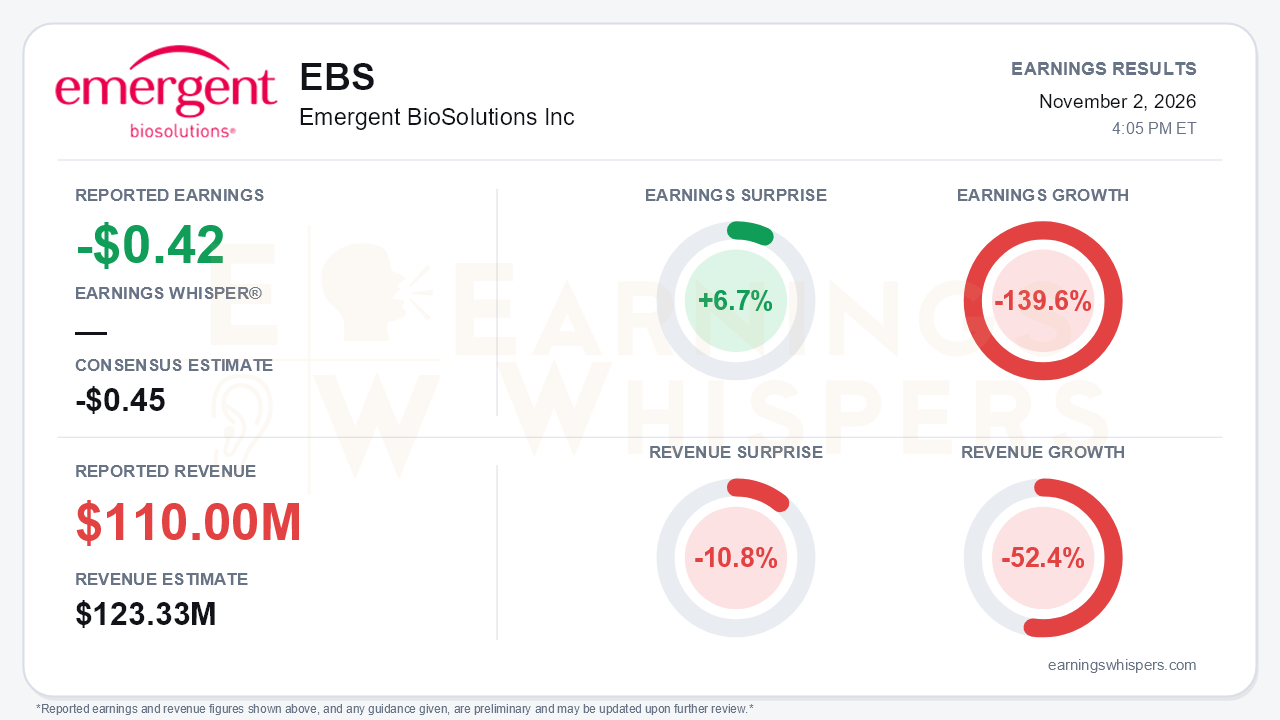
Emergent BioSolutions (NYSE: EBS) cleared a low bar on earnings and missed on almost everything else that matters. The company posted a loss of $0.42 per share on Earnings Whispers' normalized basis, which was 6.7% better than the -$0.45 consensus. Revenue was $110.0 million, missing the $123.33 million consensus by 10.8% and falling 52.4% from a year ago. Earnings declined 139.6% year over year, a swing from a solidly profitable third quarter in 2025 to a loss this year. The modest EPS beat is not the story. Management cut full-year revenue and adjusted EBITDA guidance for the second consecutive quarter, and the turnaround narrative now rests almost entirely on cost cuts and balance-sheet repair rather than top-line stabilization.
The quality of the beat deserves scrutiny. On a GAAP basis, Emergent lost $0.64 per diluted share, compared with earnings of $0.91 a year earlier. The company's own adjusted loss was $0.36. That measure now excludes stock-based compensation, a methodology change made this year, so the figures do not line up neatly. Investors should not mistake the narrower-than-feared loss for operating strength. Adjusted EBITDA was a $4.6 million loss, down from a $92.6 million profit a year earlier. Adjusted gross margin fell to 28% from 62%. In the MCM segment, segment adjusted gross margin dropped to 39% from 74% as lower volumes reduced absorption of fixed manufacturing costs. SG&A also rose 20%, partly because of severance tied to the August restructuring. Management described Q3 revenue as in line with guidance, but it landed at the very bottom of the $110–$130 million range.
The call made clear that the weakness is spreading across both businesses. Naloxone revenue fell 42% on unfavorable price-volume mix in U.S. public interest channels for OTC NARCAN. Management now expects commercial NARCAN to track toward the low end of a 20–25% annual decline. That is a sharp reversal from the 'flat to slightly up' outlook given earlier in the year. On the MCM side:
- Smallpox MCM fell 68%.
- BAT sales collapsed 87%.
- Anthrax MCM rose by $23.7 million on CYFENDUS timing, a partial offset.
Management now expects full-year MCM revenue to decline, abandoning the 'flat to slightly down' stance it held since the start of the year. Some U.S. government and international deliveries could slip into 2027. Revenue guidance has fallen in stages, from $720–$760 million originally, to $645–$675 million, and now to $600–$645 million. Adjusted EBITDA guidance has fallen from $155–$175 million to $110–$140 million.
The call preserved some genuine positives. The company raised adjusted gross margin guidance by 300 basis points to 45–47%, restoring the original range. Management credited manufacturing efficiency, mix, and NARCAN pricing that was relatively stable compared with Q2. Other developments support the cost and balance-sheet story:
- $40 million in annualized restructuring savings begin in Q4.
- All six anticipated U.S. government contract modifications were executed, including a roughly $24 million CYFENDUS award.
- A new Government of Canada standing offer creates a multi-year pathway for NARCAN.
Deleveraging also continued. Emergent repurchased $75 million of senior notes for about $68 million, gross debt fell to roughly $514 million from $693 million a year ago, and cash rose to $176 million from $140 million at Q2. Bears have legitimate ammunition here too. Net leverage climbed to 2.4x from 1.9x as EBITDA shrank faster than debt. Year-to-date operating cash flow of $122 million was helped by a $62.6 million inventory drawdown, a source that cannot repeat indefinitely. CFO Rich Lindahl's retirement at year-end adds transition risk at a delicate point in the turnaround.
The market setup is more complicated than the EPS surprise implies. Shares closed at $6.81 before the report, up 14.5% from the open after the August release. The stock had rebounded 56% from a 52-week low of $4.36 set on August 10, though it has slipped 11% from its October 5 high of $7.65. Even so, the stock sits 15.3% below its 200-day moving average of $8.04. That suggests the August rally was a recovery from capitulation rather than a rerating. Investor sentiment weakened meaningfully into the print, moving from roughly neutral at -0.04 to -0.18. The trend readings are mixed, with AVWAP positive while momentum remains negative.
The bottom line is that Emergent delivered a cosmetic EPS beat wrapped around a deteriorating revenue base. Two consecutive guidance cuts now span both NARCAN and the core biodefense franchise. Margin guidance, restructuring savings, and debt reduction give the turnaround a credible cost-side foundation. But management's tone has shifted from a 'pivotal growth year' to 'much work ahead,' and investors will need evidence that MCM delivery timing is merely deferred, not lost, before the rebound from August's lows can be trusted.
Read our earnings preview for Emergent BioSolutions Inc: https://www.earningswhispers.com/article/EBS/21387
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-16 | |
| Oct-16 | |
| Oct-15 | |
| Oct-06 | |
| Oct-05 | |
| Sep-15 | |
| Sep-03 | |
| Sep-01 | |
| Aug-31 | |
| Aug-31 | |
| Aug-11 |
