Goosehead's Core Growth Faces Its Real Test As Contingent Windfall Fades From View
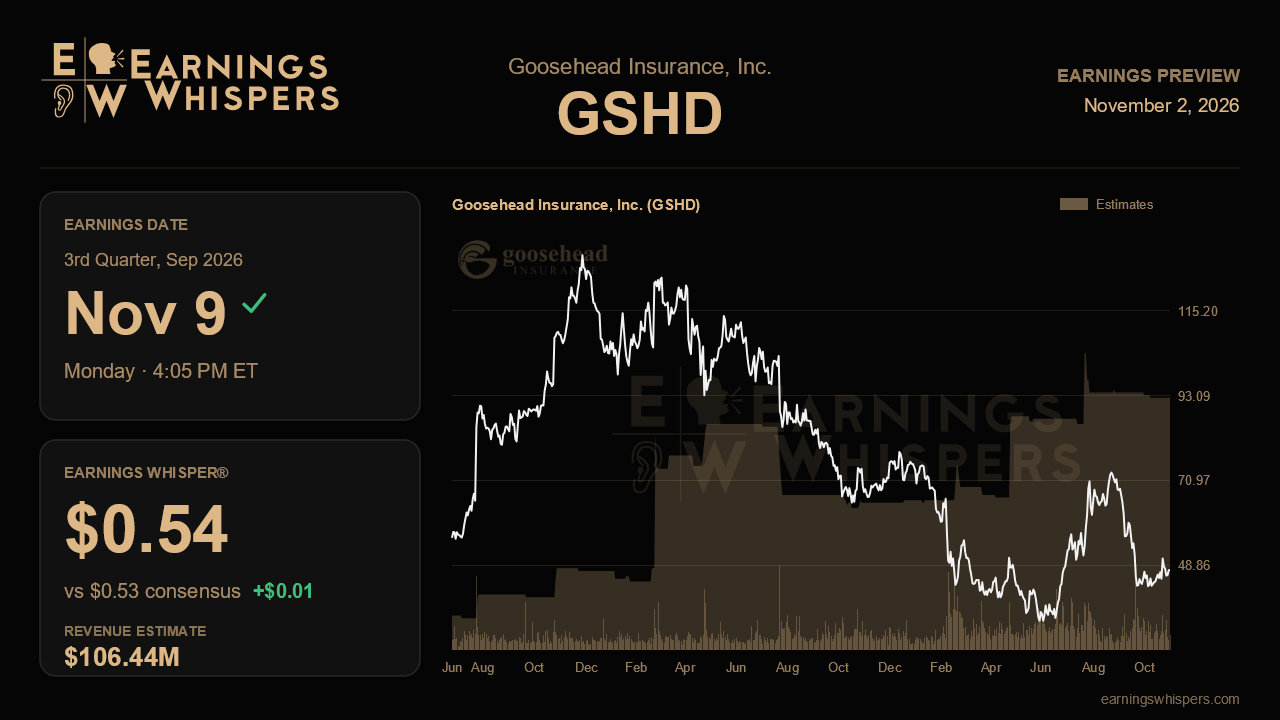
Goosehead Insurance heads into its third-quarter report with an awkward split between what the business says and what the stock says. Last quarter delivered the most confident call of the past year, with nearly every operating metric accelerating and full-year revenue guidance moving higher. Yet the shares have fallen 8.2% since then while the S&P 500 gained 2.2%, and the stock now sits at $47.61, below its 200-day moving average of $50.84 and much closer to the $42.85 low of its post-earnings range than the $74.42 high. The market appears to be questioning whether the quality of last quarter's beat matches its size.
When the company reports after the close on November 9, Wall Street expects adjusted earnings of $0.53 per share on revenue of $106.4 million. That revenue figure would represent roughly 17.7% growth from the year-ago $90.4 million, a strong pace, and earnings would sit well above the $0.29 posted a year earlier. The Earnings Whisper of $0.54 is only a penny above consensus, so the bar has not been meaningfully lifted by the more optimistic crowd. Notably, revenue is expected to slip from the second quarter's $113.4 million, which makes sense given how heavily that quarter leaned on contingent commissions.
That contingent dependence is the crux. Second-quarter contingents nearly tripled to $16.3 million, and they explain essentially all of the guidance raise. Management lifted its contingent outlook to 70 to 100 basis points of total written premium and nudged the low end of its full-year revenue growth range up to 12%, but left its core revenue expectation untouched. Core revenue grew only 10% in the quarter, or 16% excluding a prior-year recovery, and the first half ran at about 12%. The company's story requires core growth to accelerate in the back half, against tougher comparisons from 2025. Full-year consensus of $418.27 million sits comfortably inside the $409.14 million to $434.71 million guidance range, a bit below the midpoint, which leaves room for a beat but also signals the Street is not banking on the high end.
What would validate the narrative is evidence that the leading indicators are flowing into core revenue. Written premium growth accelerated to 14% and policies in force to 15% last quarter, while new business commissions rose 27%, the second straight quarter above 20%. Retention reached 86%, its best level since the hard market began, and management sees no structural barrier to returning toward 89%. Another uptick in retention would be powerful, since renewal economics are what make this franchise model compound. Investors should also look for continued producer growth per franchise, further scaling in enterprise sales, which supplied about a fifth of new business commissions, and early traction from Digital Agent 2.0 and the fast-ramping Planet Home embedded franchise. Any sign that recruiting benefited from compensation changes at a captive competitor would add a fresh tailwind.
The challenges are equally clear. Management has guided compensation and G&A growth to the high teens or low 20s, which means margins outside contingents will likely compress modestly. If core revenue fails to accelerate, that spending looks less like investment and more like drag. A service technology contract termination charge could also muddy the quarter, and the pending handoff from Mark Miller to Mark Jones Jr. at year end, alongside a new CFO, adds a layer of transition scrutiny.
Sentiment has swung from mildly bullish before the last report to roughly 30% bearish now, a meaningful shift that lowers the emotional hurdle even as the operational one remains. The deciding question is simple: can Goosehead show core revenue accelerating in the second half without contingents doing the heavy lifting? A clear yes would make the recent selloff look premature; another contingent-led quarter would keep skeptics in charge.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-15 | |
| Oct-15 | |
| Oct-06 | |
| Sep-29 | |
| Sep-24 | |
| Aug-27 | |
| Jul-23 | |
| Jul-22 | |
| Jul-22 | |
| Jul-22 | |
| Jul-20 | |
| Jul-15 | |
| Jul-10 | |
| Jun-15 |
