Ethos Crushes Q3 Estimates And Raises Guidance Again, But Third-Party Mix Shift Keeps Compressing Margins
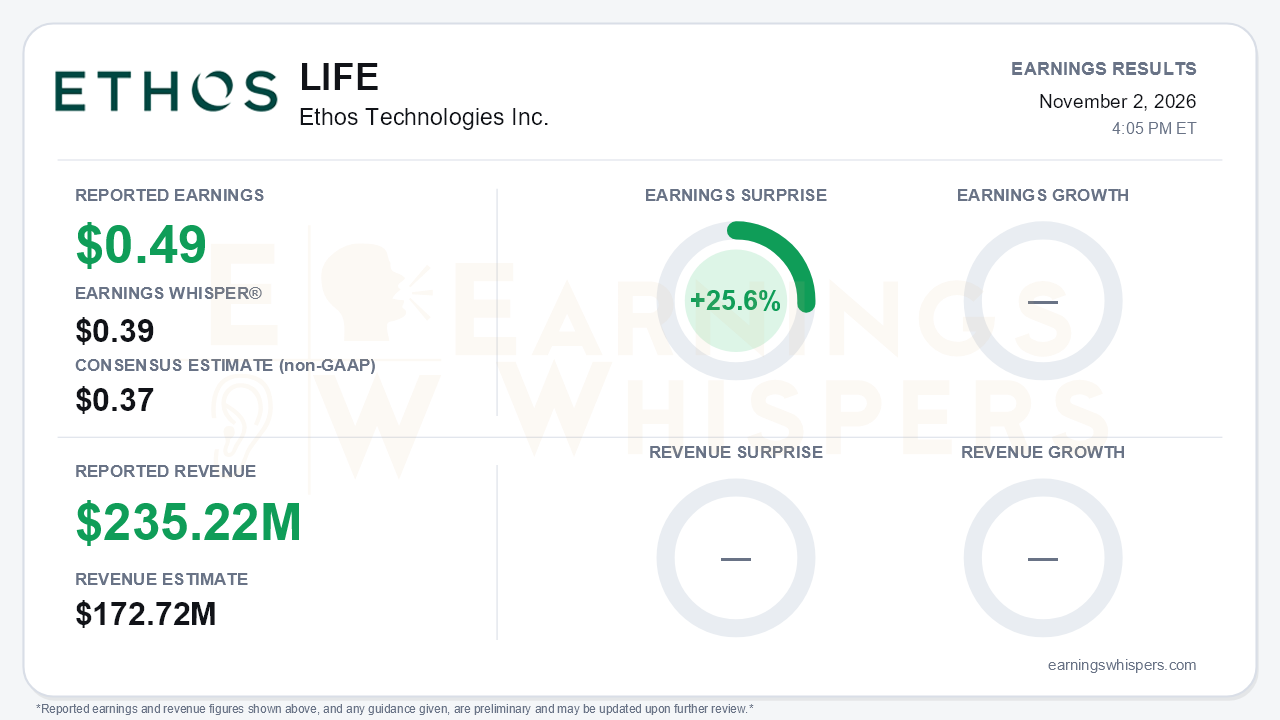
Ethos Technologies (NASDAQ: LIFE) delivered another blowout quarter, reporting third-quarter non-GAAP earnings of $0.49 per share on revenue of $235.22 million. That beat the $0.37 consensus by 25.6% and cleared the $0.39 Earnings Whisper number, while revenue topped the $172.72 million consensus by 36.2%. The beat was even wider against the company's own outlook. Revenue exceeded the midpoint of the $160-164 million guide from the second-quarter call by roughly 45%, and adjusted EBITDA of $34.9 million beat its $23-25 million guide by a similar margin. Management also raised full-year guidance for the third straight call. The central tension is that Ethos is growing much faster than anyone modeled, but each incremental dollar is arriving at a lower margin.
The quality of the quarter deserves scrutiny beneath the headline. Revenue grew 151% year over year, and the mix tilted sharply. Third-party channel revenue rose 209% to $116.4 million, while direct channel revenue grew 112% to $118.8 million. Gross margin held at 98%. Contribution margin, however, fell to 28%, down from 33% in the second quarter and 39% a year ago. Adjusted EBITDA margin slid to 15% from 19% last quarter and 20% in the year-ago period. On a GAAP basis, net income was just $4.7 million, or $0.07 per share, compared with $15.9 million a year earlier. Stock-based compensation of $29.2 million accounts for most of the gap between GAAP and non-GAAP profit. That expense surged after the IPO, and investors focused on GAAP results should not ignore it.
The call made clear that the margin slide is a mix story rather than a pricing collapse, though that distinction offers only partial comfort. Third-party growth has accelerated in every quarter: 27%, then 42%, 90% and now 209%. Both new 2025 and 2026 agency cohorts and tenured agencies contributed. That channel carries lower economics, and third-party mix rose about 10 points. Heavier brand spending on TV, radio and social added to the pressure. The result is a contribution margin below the mid-30s run-rate management guided to on the first-quarter call. Bears have other legitimate ammunition as well:
- Return on ad spend declined modestly year over year, after holding or improving in the first two quarters.
- Direct channel growth has decelerated from 136% to 131% to 112%.
- Average revenue per unit fell for another quarter, to $1,655 from $1,758, on the whole-life mix.
The offsets are substantial. Policies activated reached 142,111, up from 107,847 in the second quarter and 88,373 in the first. G&A plus R&D fell to about 13% of revenue from roughly 19% a year ago. Operating cash flow of $40.7 million exceeded adjusted EBITDA, and cash and investments climbed to about $290 million. Management also highlighted that its vertically integrated stack kept production running during a carrier partner's July systems outage, and it pitches that resilience to carriers. Investors should note one balance-sheet caveat: commissions receivable keep swelling, to roughly $433 million in total, so a growing share of reported revenue is collected over time.
Guidance is where the setup gets more complicated. Full-year revenue guidance is now $838-842 million, implying 117% growth. That figure has climbed steadily from $510-514 million at the start of the year. Adjusted EBITDA guidance rose to $134-136 million. Yet the fourth-quarter outlook of $220-224 million sits below the $235 million just reported, and the EBITDA guide of $30-32 million implies a margin near 14%. Given how badly the company's own third-quarter guide understated results, the sequential dip may reflect conservatism. Still, it signals no margin recovery near term. Unlike prior quarters, no new products or partners were announced, the AI-agent channel is not yet producing material origination, and no shares have been repurchased under the new $100 million authorization. Management's tone was its most emphatic yet, with talk of 'absolute confidence,' and a 2027 preview is due in February.
The market had already been rewarding the growth story. Shares rose 58.8% from the opening price after the August report to $43.39 heading into this release. That put the stock just 3.6% below its 52-week high of $44.99, set October 23, and about 97% above its 200-day moving average. The stock had rallied roughly 81% off its inter-earnings low of $23.95, reached the day after the last report. Investor sentiment improved sharply, from -0.35 to roughly -0.02, but it remains essentially neutral rather than enthusiastic. Momentum and AVWAP trend readings are positive, consistent with the price action. With the stock entering the report near the top of its range, a clean beat was arguably the minimum requirement.
The bottom line is that Ethos produced another quarter of hypergrowth, a large beat and a meaningful guidance raise, and it is converting that growth into real cash. The cost is visible in a contribution margin that has now fallen below management's own framework, along with softer ad efficiency, slowing direct growth and a sequentially lower fourth-quarter guide. With shares near their highs, the next leg likely depends less on whether Ethos can grow and more on whether management's February 2027 outlook shows that third-party scale can stabilize margins.
Read our earnings preview for Ethos Technologies Inc.: https://www.earningswhispers.com/article/LIFE/21408
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Oct-28 | |
| Oct-26 | |
| Oct-12 | |
| Oct-01 | |
| Sep-29 | |
| Sep-17 |
Ethos Technologies Highlights Why Key Sell Rules Also Apply To New IPOs
LIFE -5.58%
Investor's Business Daily
|
| Aug-19 | |
| Aug-13 | |
| Aug-04 | |
| Aug-03 | |
| Jul-31 | |
| Jul-21 | |
| Jul-14 |
