Ichor's Margin-Driven Beat Clears The Bar Easily, But Supply Limits And Cash Burn Keep The Revenue Story Short Of Clean
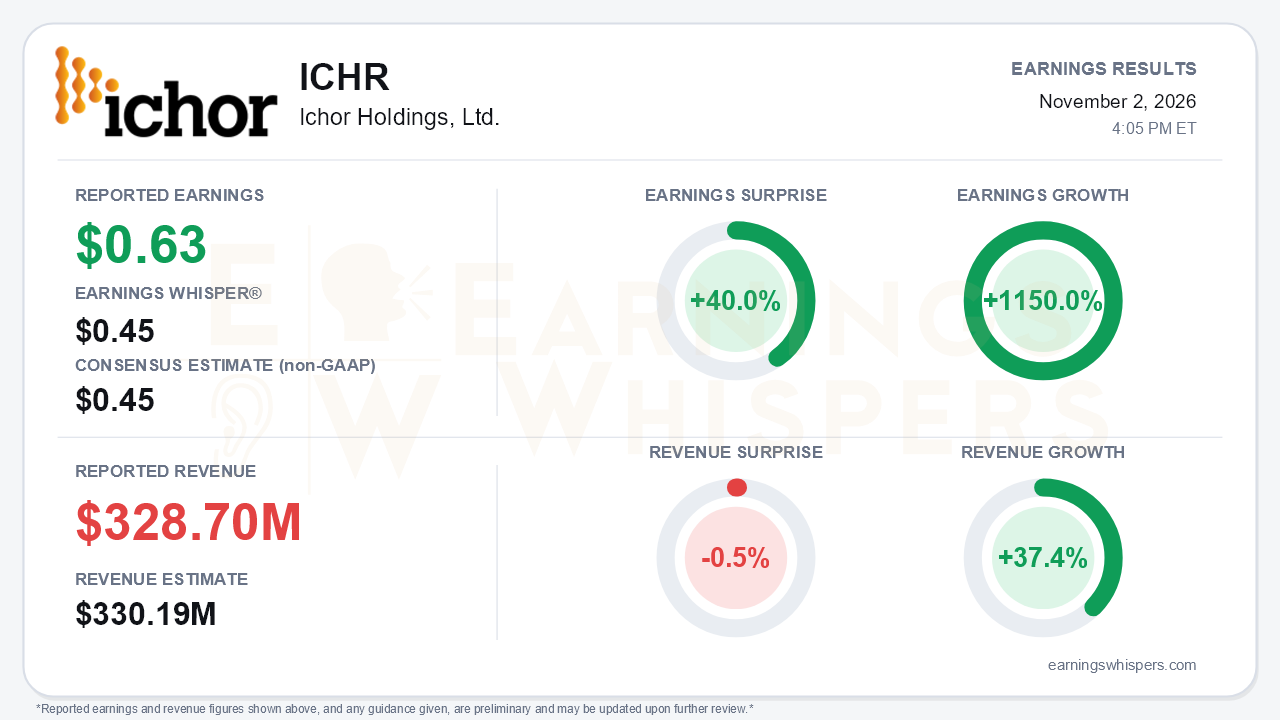
Ichor Holdings delivered the kind of earnings leverage its turnaround thesis promised. Non-GAAP EPS of $0.63 beat both the $0.45 consensus and the $0.45 Earnings Whisper number by 40.0%, and it cleared management's own $0.40-$0.50 guidance range at the top. Earnings grew 1150.0% year over year, a swing from a $0.42 non-GAAP loss a year ago. On a GAAP basis the company earned $0.55, against a $0.67 loss. Revenue rose 37.4% to $328.7 million but missed the $330.19 million consensus by 0.5%. That split is the central tension of the quarter. Profitability is running ahead of plan, while the top line is now being capped by sub-tier supply constraints that management said were not a factor three months ago.
The quality of the beat holds up better than most. Non-GAAP gross margin reached 16.0%, up from 14.1% in Q2, 12.8% in Q1 and 11.7% in the Q4 2025 trough. That reached management's Q4 target a quarter early and beat the 14.5%-15.5% guide. Incremental flow-through was 33%. Non-GAAP operating margin widened to 8.6% from 5.5%, helped by a sequential decline in GAAP R&D and SG&A spending. Adjusted EBITDA rose to $33.9 million from roughly $21 million. Proprietary content exited the quarter above 30%, versus 25% in Q2. That metric matters because it is the structural lever behind the margin story, alongside the consolidation into volume manufacturing sites. The weak spot is cash. Operating cash use widened to $28.8 million, and free cash flow was negative $39.5 million, as inventory rose $39.5 million and receivables rose $36.0 million. Cash fell $43 million to $213.5 million. That balance is still comfortable only because of the $195.4 million equity raise in Q2, which also lifted the diluted share count to 38.2 million from 34.3 million a year ago.
The call sharpened both sides of the story. On the margin side, management raised its incremental gross margin model to 25%-30% from 20%-25%. It guided Q4 non-GAAP gross margin to about 16.5% and non-GAAP EPS to $0.65-$0.75. The early 2027 framework calls for sequential revenue growth every quarter and earnings growth more than double revenue growth. A lower tax rate also helps: about 15% in Q4 and 15%-20% for 2027, versus 20%-25% previously. Investors should recognize that the tax benefit is not operational. On the revenue side, the Q4 guide of $345-$365 million implies about 8% sequential growth at the midpoint. That falls short of the more-than-10% and at-least-$350 million framing from the Q2 call. Second-half growth over the first half slipped to 24% at the midpoint from "at least 25%." Roughly $10 million was removed. About half came from commercial space launch push-outs, and half from valve and mass-flow-controller shortages limiting high-end etch and deposition shipments.
Those constraints are partly a high-class problem. Management described demand visibility extending well into 2027, with customers backstopping inventory more broadly than in past cycles. A lithography customer is expected to step up modestly in Q4 and sharply in Q1 2027. Ichor also won components on six new tool platforms outside the gas panel, and external component sales are expected to rise about 250% from Q1 to Q4, albeit from a small base. Still, bears have legitimate ammunition. The investment burden is rising:
- Capex is running near 4% of revenue against a 3% target.
- 2027 operating expenses are guided up about 15%, versus roughly 6% in 2026.
- Incremental gross margin is guided back to about 25% in Q4 as gas panel mix rises.
- The company added 320 hires in Q3, with manufacturing headcount up 40% year to date.
- The long-term 20% gross margin target was not raised.
The market setup is far more punishing than the fundamentals. Shares were $38.90 heading into the report, down 48.9% from the $76.18 open after the August release. They sat 35.9% below the 200-day moving average and just 5.1% above the inter-earnings low of $37.00 set October 22. Investor sentiment remained positive but weakened noticeably, sliding to 0.12 from 0.28. Trend readings were mixed: sequential growth and momentum were positive, while price and AVWAP trends remained negative. The stock has been priced for disappointment while earnings have kept compounding.
The bottom line is that Ichor's quarter strengthened the earnings case even as it weakened the revenue case at the margin. Margins, proprietary content and earnings guidance all moved up. Revenue guidance, cash generation and the supply chain moved the wrong way. With the stock near its lows, the key question is whether the component constraints are timing issues or a ceiling on 2027 growth, and whether the working-capital build converts to cash once the ramp matures.
Read our earnings preview for Ichor Holdings, Ltd.: https://www.earningswhispers.com/article/ICHR/21402
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-07 | |
| Sep-28 | |
| Aug-04 | |
| Aug-03 | |
| Aug-03 | |
| Jul-13 | |
| Jun-04 | |
| May-13 | |
| May-09 | |
| May-06 | |
| May-04 |
