Harmonic's Breakout Quarter And Third Guidance Raise Run Into A Bookings And Cash-Flow Test
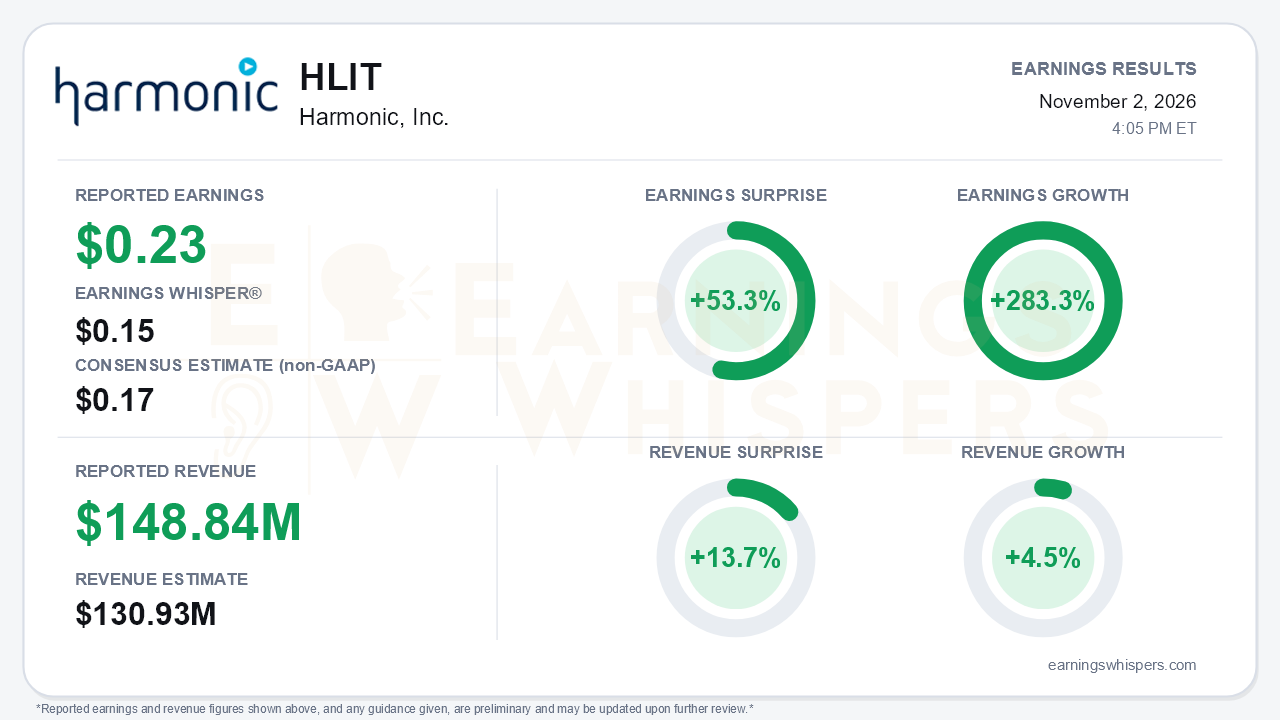
Harmonic delivered the kind of quarter that usually resets a narrative. Non-GAAP earnings of $0.23 per share beat the $0.17 consensus by 53.3% and cleared the $0.15 Earnings Whisper number. Revenue of $148.84 million topped the $130.93 million consensus by 13.7% and blew through management's own $125-135 million guide. Earnings grew 283.3% year over year. On the Earnings Whispers normalized basis, revenue grew 4.5%. The press release, which restates prior periods to exclude the Video business sold to MediaKind in June, shows continuing-operations revenue up 64% from $90.5 million. That gap appears to reflect the different prior-year bases, and the 64% figure better captures the pure-play broadband trajectory. Management then raised full-year guidance for the third straight time. The central tension is that the forward indicators softened just as the income statement hit its stride.
The composition of the beat matters more than its size. Rest-of-Market revenue rose to $68.7 million from $49.4 million in Q2, more than doubling year over year to a record 46% of sales. Revenue from the top two customers actually slipped sequentially, to $80.1 million from $84.1 million. Every dollar of sequential growth therefore came from diversification. That directly answers the long-standing concentration critique, although the top two still account for 54% of revenue and there are four 10%-plus customers. Profitability has transformed from a year ago:
- Non-GAAP gross margin was 52.1%, up from 46.9% a year earlier.
- Non-GAAP operating margin reached 22.2%, up from 11.1%.
- Both measures dipped modestly from Q2's 53.0% and 23.5%.
- Operating expenses ran above guidance on incentive accruals, earnouts and an R&D reclassification.
On a GAAP basis, continuing operations earned $0.16 per share. Total GAAP EPS was $0.13 after a discontinued-operations loss.
The guidance trajectory is the strongest part of the bull argument. Full-year revenue guidance has climbed from $440-480 million in February to $545-555 million now, roughly 20% above the original midpoint. Non-GAAP EPS guidance of $0.80-0.84 compares with an initial $0.46-0.63. Full-year gross margin guidance rose to 52.1-52.4% despite memory cost pressure. Commercially, the cOS footprint expanded to 167 customers and about 53 million devices, up from 161 and 48.2 million. Harmonic also added nine new customers, including regional tier-1s Liberty Latin America and TDC Denmark. Management framed an expanded opportunity around three growth engines and a TAM above $7 billion by 2030. That framework rests on several building blocks:
- the cOS SensAI launch, with intelligence targeted at about 10% of revenue in three years;
- Recon, co-developed with Comcast;
- a fiber-management tuck-in acquisition;
- a 50G PON solution slated for 2027.
Bears have legitimate ammunition, however.
- Book-to-bill fell to 0.7 from 1.1 in Q2. Bookings were $105.9 million against $144.3 million.
- Rest-of-Market book-to-bill slowed to about 1.0 from above 1.5.
- Backlog and deferred revenue fell to $534 million from a record $587.6 million, though that is still up 58% year over year.
- Free cash flow was negative $5.1 million, following negative $7 million in Q2. Inventory roughly doubled from year-end to $94.8 million, inventory days rose to 120 and DSO climbed to 71.
Management attributes the softness to seasonality and a deliberate inventory build. Q4 guidance of $141-151 million is roughly flat sequentially at the midpoint, which fits a business digesting backlog rather than accelerating further. Component inflation is also broadening beyond memory into silicon and PCBs heading into 2027. That will test pricing power if pass-through lags.
The market had already leaned toward the skeptical reading. Shares closed at $10.23 on October 30, down 29.4% from the $14.48 open after the August report, despite that quarter's guidance raise. The stock sat 11.6% below its 200-day moving average of $11.58. It was 32.1% below the inter-earnings high of $15.06, set the day after the last report, and only 5.6% above the October 15 low of $9.69. Investor sentiment slipped from neutral to modestly negative at -0.15. Price and AVWAP trend readings are negative, while momentum is positive. Expectations heading into the print were clearly subdued. That gives an upside-heavy report room to surprise a crowd focused on bookings and cash conversion.
The bottom line is that Harmonic's earnings power and customer diversification have improved faster than almost anyone projected at the start of the year. A third raise backed by Rest-of-Market strength is hard to dismiss. The quality of forward visibility now deserves scrutiny, however. A 0.7 book-to-bill, shrinking backlog, two quarters of negative free cash flow and rising cost inflation give the stock's steep decline a fundamental basis. Q4 bookings, together with inventory and receivables starting to unwind, will determine whether this quarter marks a durable step-up or a peak in the shipment cycle.
Read our earnings preview for Harmonic, Inc.: https://www.earningswhispers.com/article/HLIT/21395
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| Oct-26 | |
| Oct-20 | |
| Oct-12 | |
| Oct-08 | |
| Sep-30 | |
| Sep-24 | |
| Sep-10 | |
| Sep-08 | |
| Aug-27 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 |
