Syndax Misses On EPS But Revuforj Rebound And Higher Niktimvo Margin Guide Sharpen The Commercial Story As Pipeline Setbacks Hang Over The Stock
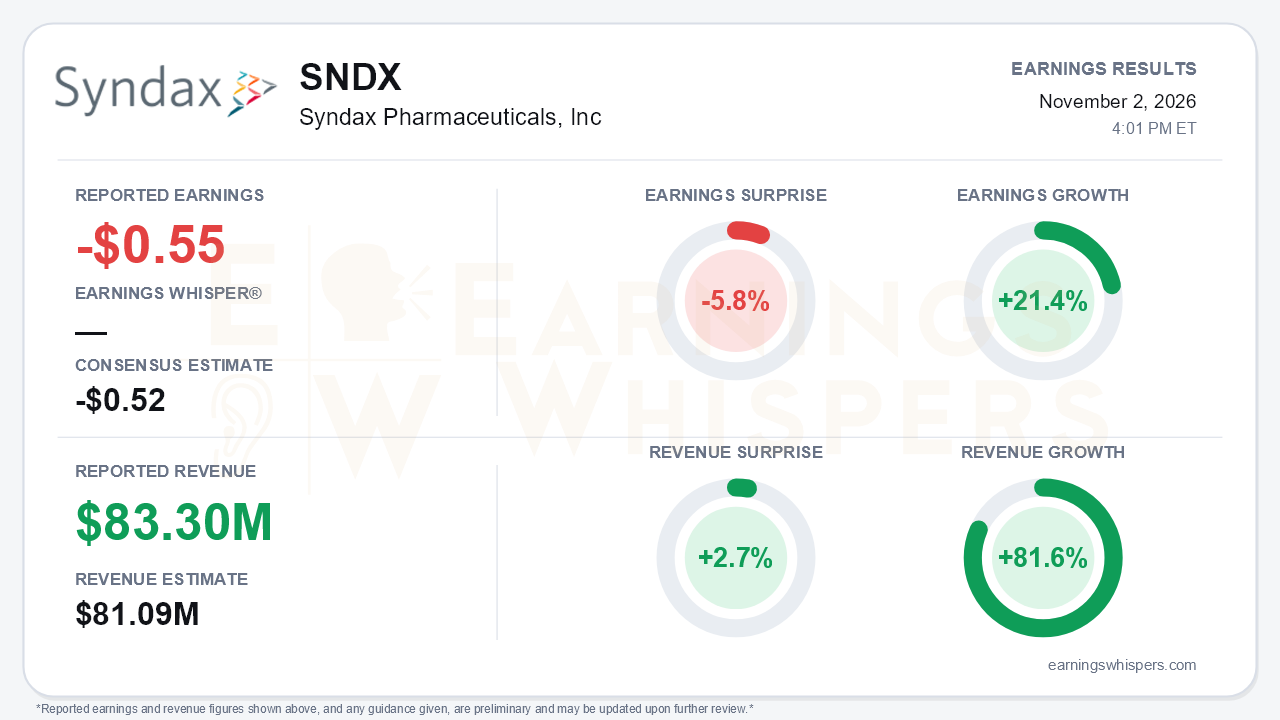
Syndax Pharmaceuticals posted a third-quarter loss of $0.55 per share, 5.8% worse than the -$0.52 consensus. Revenue of $83.3 million beat the $81.09 million estimate by 2.7% and rose 81.6% year over year. The loss still narrowed from $0.70 a year ago, which Earnings Whispers calculates as 21.4% earnings growth. That is the central tension. The commercial engine is doing almost everything investors could ask, but costs below the revenue line absorbed the upside, and a string of pipeline and timing disappointments has overwhelmed the sales story in the share price.
The quality of the EPS miss deserves scrutiny. It did not come from weak sales. Cost of product sales jumped to $14.0 million from $2.1 million a year earlier. That single quarter exceeded the roughly $5.8 million booked across the first half of 2026 combined, and the release offers no explanation. Royalty interest expense climbed to $11.8 million from $8.3 million, and new convertible-note interest added $1.2 million. Research and development rose to $67.5 million from $56.3 million as frontline revumenib trials scaled. Selling, general and administrative spending fell modestly as 2025 launch costs rolled off. Operating loss improved to $41.9 million from $57.4 million, but the gains were thinner at the bottom line. Cash ended at $551.1 million, down from about $575 million after the second-quarter convertible raise. Stockholders' equity has also slipped to a $17.2 million deficit. Management reiterated roughly $400 million in full-year cash operating expenses and said existing resources will carry the company to profitability.
The call preserved a credible growth story.
- **Revuforj sales:** Net revenue reached $60.7 million, up from $54.7 million in Q2, $48.9 million in Q1 and $44.2 million in Q4.
- **New patient starts:** Starts rebounded about 20% sequentially to roughly 300, after a Q2 dip to about 250 that management had called an anomaly.
- **Post-transplant resumption:** About 60% of R/R KMT2Ar patients who go to transplant now resume therapy afterward. That is up from about 50% in Q2 and about 45% in Q1.
- **New NPM1 driver:** Management disclosed that roughly 40% of NPM1m patients proceed to transplant and about half of those resume therapy. NPM1 now accounts for more than 35% of Revuforj revenue.
That post-transplant dynamic matters because it extends duration of therapy. However, total prescriptions grew 13% sequentially, slower than new starts and down from 15% in Q2. Management also deferred most of the post-transplant tailwind to 2027.
Niktimvo was arguably the bigger upside surprise.
- **Sales:** Net sales of $67.4 million rose 12% sequentially, accelerating from 9% in Q2. The drug is now annualizing above $260 million.
- **Collaboration revenue:** Syndax's share was $22.6 million, up from $18.1 million in Q2. That implies a margin of about 34%.
- **Margin guidance:** Management lifted its contribution-margin guidance to the low-to-mid 30% range from 25%-30%.
The caveat is that the Q3 margin included a one-time benefit, so the run-rate gain is smaller than the headline figure suggests.
Bears have legitimate ammunition on the pipeline side.
- **IPF failure:** The MAXPIRe Phase 2 trial of axatilimab in idiopathic pulmonary fibrosis missed its primary endpoint in October. The program, framed on the Q2 call as a potential multi-billion-dollar opportunity, is being abandoned. The press release disclosed the failure, but the call's prepared remarks did not address it.
- **cGVHD delay:** The frontline axatilimab-plus-ruxolitinib cGVHD readout slipped to Q1 2027 from Q4 2026.
- **CFO change:** CFO Keith Goldan is retiring, with Aaron Ondrey taking over November 9.
- **Frontline timing:** Management declined to give enrollment or readout timing for the pivotal EVOLVE-2 and REVEAL-ND frontline trials.
- **Competition:** Competing menin data from J&J and Sumitomo may surface at ASH.
The offset is a dense fourth-quarter revumenib slate. It includes frontline BEAT AML, SAVE and intensive-chemotherapy combinations, INTERCEPT MRD data, post-transplant maintenance results and a NUP98r publication. The myelofibrosis proof-of-principle trial and the SNDX-4321 IND are also due by year-end.
The market has treated the stock harshly. As of October 30, shares were at $13.65, down 21.1% from the $17.31 open after the August report. That leaves the stock 32.6% below its $20.24 200-day moving average and 35% below the September 2 high of $21.00. The stock is just 6.7% above the 52-week low of $12.80 set October 19, which reflects the IPF failure. Investor sentiment entered the report negative and was essentially unchanged, edging to -0.35 from -0.34. The Earnings Whispers trend readings lean negative on price and AVWAP, while sequential growth stands out as positive. That mix echoes the gap between improving sales and a falling stock.
The bottom line is that Syndax delivered a cleaner commercial quarter than the EPS miss implies. Revuforj new starts recovered, transplant-driven duration is broadening across both indications, and Niktimvo margin guidance moved higher. But a sharp cost-of-sales jump and rising financing costs ate the revenue upside, and the IPF failure plus the cGVHD delay removed near-term pipeline optionality. Management also offered little visibility on frontline timing. With shares hugging their lows and sentiment still negative, the ASH data and competitive readouts will likely matter more to the stock than this quarter's beat on sales.
Read our earnings preview for Syndax Pharmaceuticals, Inc: https://www.earningswhispers.com/article/SNDX/21433
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 5 hours | |
| 5 hours | |
| Oct-30 | |
| Oct-30 | |
| Oct-26 | |
| Oct-26 | |
| Oct-15 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-12 | |
| Oct-12 | |
| Oct-02 | |
| Sep-04 |
