Offerpad Misses Every Q3 Guidepost And Pushes Breakeven To Mid-2027 As Cash Thins Behind A 605-Home Inventory Bet
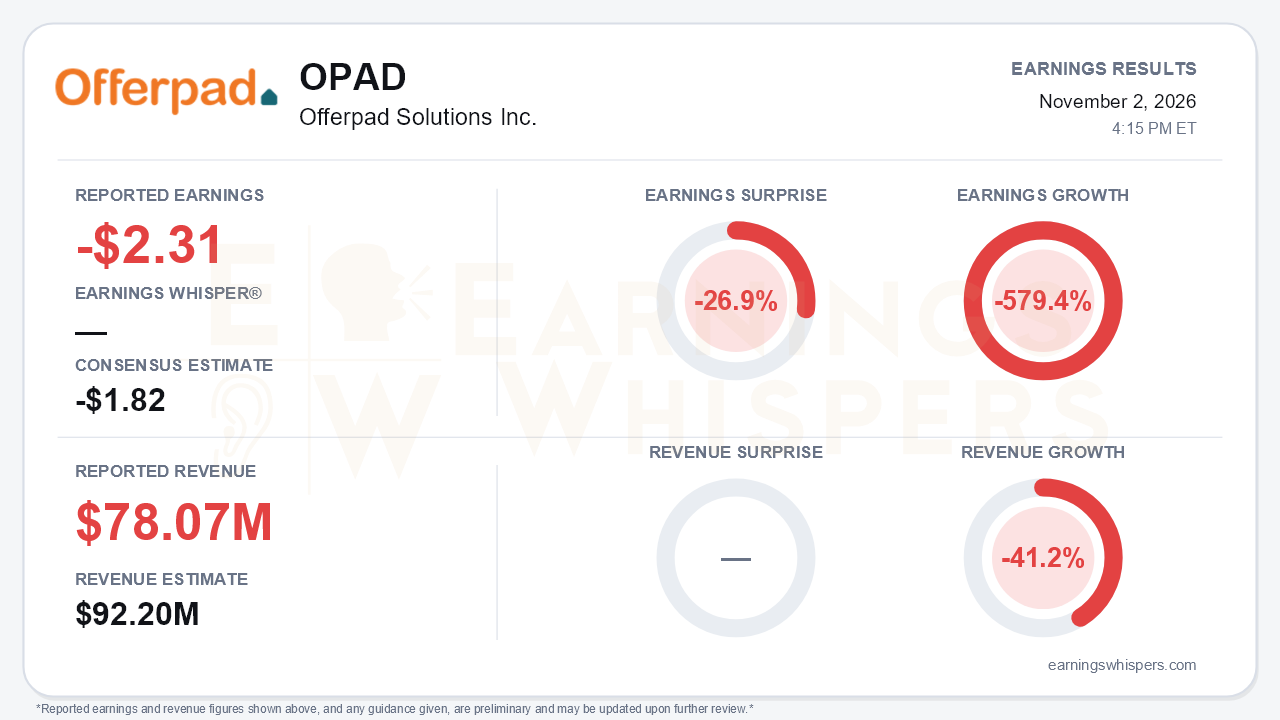
Offerpad Solutions (NYSE: OPAD) delivered a broad miss for the September quarter. The company reported a loss of $2.31 per share against a consensus estimate of -$1.82, a 26.9% shortfall. Revenue of $78.07 million fell 41.2% year over year and missed the $92.2 million consensus by 15.3%. Earnings Whispers' normalized figures show earnings down 579.4% year over year. The company's GAAP presentation reads differently: net loss was essentially flat at $11.5 million versus $11.6 million, and diluted loss per share narrowed to $2.30 from $3.71 on a sharply higher share count. The more consequential problem is not the year-over-year comparison. It is that Offerpad missed its own guidance on every major line and moved its profitability target out by roughly two quarters. That is the central story of the quarter.
The guidance misses were wide. Revenue came in well below the $90-100 million guide, and the 324 transactions fell short of the 350-400 forecast. The Adjusted EBITDA loss widened to $7.5 million from $6.2 million in Q2, when management had guided to a narrower loss. That reversed a steady improvement from -$6.9 million in Q4 FY25 and -$6.7 million in Q1. Gross margin slipped to 8.3% from 9.2%. General and administrative expense rose to $6.6 million from $5.1 million a year earlier, and interest expense climbed sequentially to $2.2 million from $1.4 million as inventory debt ballooned.
Beneath the miss, some unit economics held up. Contribution profit after interest was $12,900 per transaction, slightly below Q2's $13,500 but roughly double the $6,400 of a year ago. Per home sold, the figure was $19,800 versus $8,200. Total transactions rose for a second straight quarter, from 263 in Q1 to 295 in Q2 and 324 in Q3. Fee-based Brokerage and Cash Offer Marketplace channels made up about 35% of closings, and brokerage listing signings more than doubled sequentially. The business is not broken at the per-deal level. It is too small to cover its cost base, and it is now carrying far more inventory risk.
That inventory build is the quarter's defining decision. Offerpad bought 605 homes in Q3, up from 268 in Q2, but sold only 210. Real estate inventory swelled to $231 million from $94 million at year-end, and nine-month operating cash flow was a $159 million outflow. Unrestricted cash fell to $12.1 million, down from $33.1 million in Q2 and $41 million in Q1. Management points to roughly $55 million of equity in inventory, aged homes at just 2.6% of the book, and about $251 million of undrawn financing capacity. Most of that capacity, however, is uncommitted. The timing was unfortunate. Mortgage rates jumped from about 6.7% to 7.4% or higher late in the quarter, and the call flagged softening in Charlotte, Raleigh and Florida plus builder-incentive pressure in Houston and Dallas.
The tone change was striking. On the Q2 call, management described the buying engine as back on and the company as playing offense. This call focused on converting inventory to cash, tighter acquisition criteria, and cost cuts. Several other developments add to the caution:
- The CFO departed, and Andrew Pieper is serving as interim CFO.
- The earlier stance that no incremental capital was needed softened into openness to strategic capital partnerships, which raises the prospect of dilution or more expensive funding.
- The goal of reaching about 1,000 transactions per quarter by the end of 2026 was effectively abandoned.
Management did offer credible offsets. It identified another $8-10 million in annualized operating expense cuts, which it says lowers the breakeven threshold to roughly 800-850 transactions per quarter. Underwriting spreads have roughly doubled. For Q4, Offerpad guided to 400-475 transactions and $100-120 million in revenue, with 200 homes already sold or under contract, and it expects Adjusted EBITDA to improve sequentially. That outlook assumes no rate relief. Earnings Whispers notes the revenue guide sits below estimates. And even the high end of the transaction guide is well short of the new breakeven range.
The market had largely anticipated trouble. Shares were at $2.17 heading into the report, down 37.8% from the $3.49 opening after the August release. They had given back the entire post-report spike to $5.10 and finished just 2.4% above an inter-earnings low set on October 30. The stock sits 10.5% below its 200-day moving average. Investor sentiment turned slightly more negative, moving from -0.033 to -0.057, a modest shift that leaves expectations subdued rather than capitulatory. The trend signals are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Offerpad has bet its near-term future on selling a large, fresh inventory into a higher-rate market with a thin cash cushion. The better per-transaction economics and the lower breakeven target preserve a plausible path to profitability. But the company missed its own guidance, delayed breakeven, changed CFOs, and softened its capital stance all in one quarter, which gives bears legitimate ammunition. Q4 execution on dispositions and cash recovery will matter far more than the headline EPS figure.
Read our earnings preview for Offerpad Solutions Inc.: https://www.earningswhispers.com/article/OPAD/21418
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-08 | |
| Sep-08 | |
| Sep-02 | |
| Aug-18 | |
| Aug-04 | |
| Aug-03 | |
| Jul-15 | |
| Jun-04 | |
| May-11 | |
| May-01 | |
| Apr-30 | |
| Apr-29 |
