James River Must Show Casualty Rate Slide Has Bottomed As Premiums Keep Shrinking
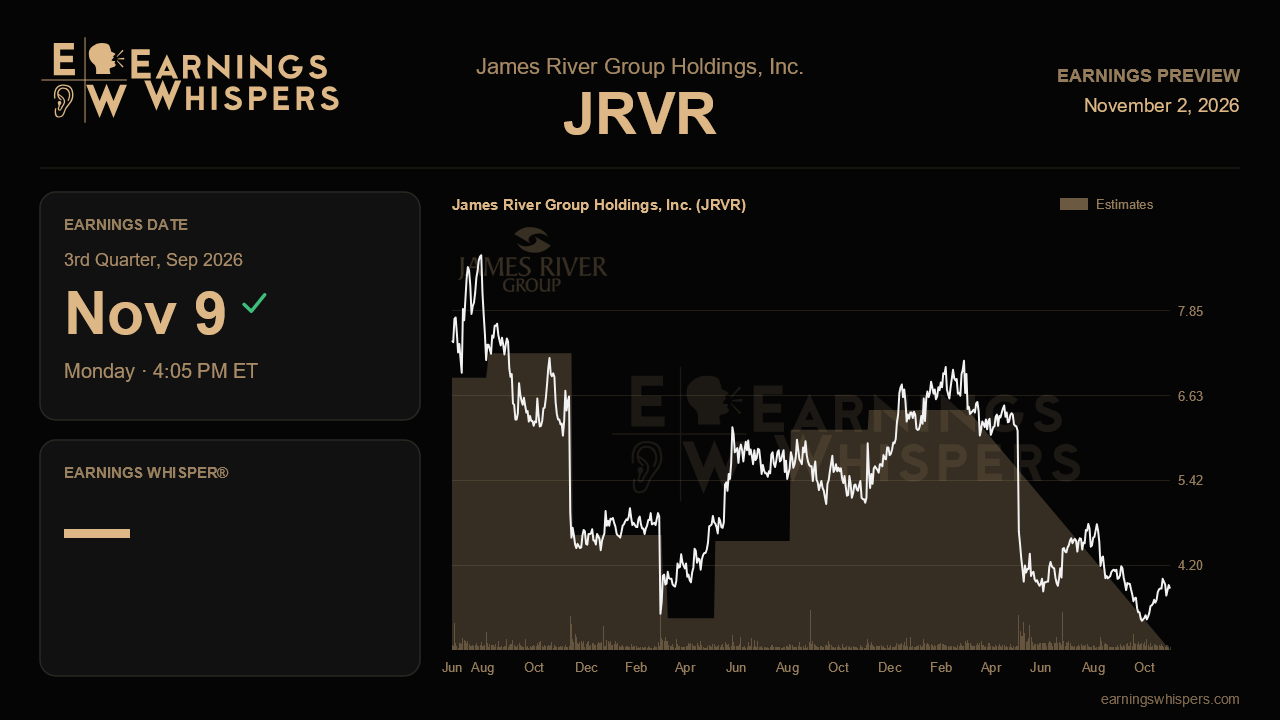
James River heads into its third-quarter report with a split personality that the market has not yet resolved. Its core excess and surplus lines business is underwriting profitably and expenses keep falling, yet the top line keeps contracting, rate increases have faded sharply, and competitive pressure that once centered on property has spread into general casualty, the company's bread and butter. The November 9 release, due after the close, is less about a single earnings number than about whether management's more defensive posture from last quarter marked a pause or the start of a longer squeeze.
The bar starts from a modest base. Second-quarter earnings came in at $0.20 per share on revenue of $161.3 million, down from $0.32 and $172.7 million in the year-ago third quarter. Street estimates for the quarter are not meaningfully usable, and the company has offered no formal guidance, so the year-ago figures are the most sensible yardstick. Matching $0.32 would require either a cleaner loss quarter or a bigger contribution from the lower tax rate that followed last November's redomicile, which brought the effective rate down to roughly 22% from above 30%. Revenue will almost certainly trail last year given the deliberate shrinkage underway.
The most important number may be E&S casualty rate change. It slid to about 3% in the second quarter from high single digits in the first quarter and a 9% average for 2025. Another step down toward flat would suggest pricing power is gone just as roughly 30 Southeast managing general agents are loosening terms on assault and battery coverage. Stabilization near 3% would support the view that James River is holding discipline while rivals chase volume. Closely tied is the E&S combined ratio, which improved to 92.8% last quarter. Keeping it in the low 90s while rate decelerates would validate the underwriting story; slippage back toward the mid-90s would suggest loss trends are beginning to outrun pricing. Reserve development deserves scrutiny too, since the top-up adverse development cover is now exhausted after the final $7.5 million cession. Recent accident years have developed favorably, and any adverse charge would now hit earnings without that backstop.
On growth, management has visibly retreated from its early 2026 talk of meaningful profitable expansion and low-to-mid-teens returns on tangible equity. The new message is that growth would show up first in submissions and policy counts before reaching premium. That gives investors a specific test: submissions have been rising about 4%, and policy count gains alongside a less severe drop in average account premium, which fell nearly 23% last quarter, would show the smaller-account mix shift is building a base rather than simply masking erosion. Cost cuts, with G&A down 9% year to date and the specialty admitted segment sharply downsized, should keep helping, as should higher net retention of 55%, though retaining more premium also means keeping more risk.
The stock has been punished since the last report, falling 7.9% against a 2.4% decline for the S&P 500. At $3.87 it sits well below its 200-day moving average of $5.01 and in the lower half of its post-earnings range of $3.36 to $4.46, a band that has shifted down from the prior quarter's $3.76 to $5.27. Sentiment remains bearish but noticeably less so than heading into the last report, which hints that some of the disappointment may already be priced in.
The central question is whether underwriting margins can hold as rate momentum fades and casualty competition intensifies. If James River shows steady E&S profitability, clean reserves and early policy count growth, the softening narrative becomes a story of disciplined shrinkage. If rate keeps falling and margins follow, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-22 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-31 | |
| Jun-08 | |
| May-19 | |
| May-04 | |
| May-04 | |
| May-04 | |
| May-01 | |
| Apr-06 | |
| Mar-04 | |
| Mar-03 |
