IHeartMedia's Q3 Must Prove Its $800 Million EBITDA Target Still Holds After 52% Plunge
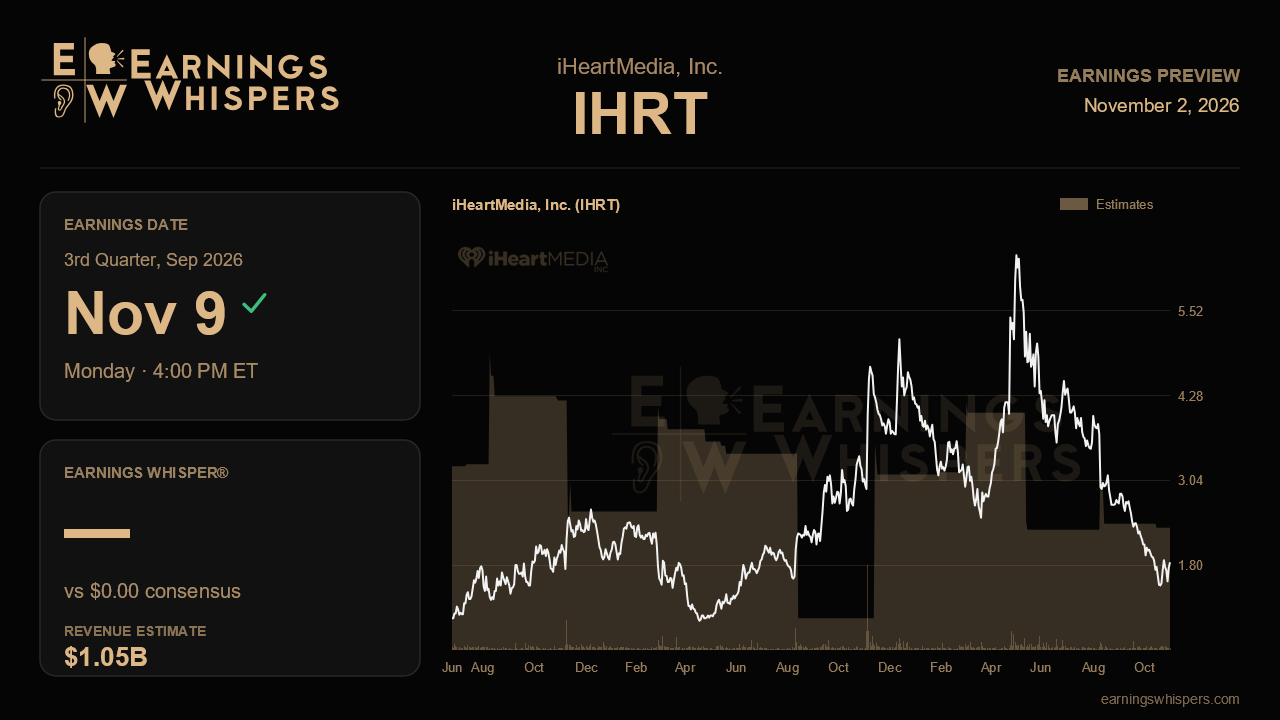
iHeartMedia heads into its third-quarter report with a revenue number that looks almost pre-written and a full-year promise that looks increasingly hard to keep. Management has reaffirmed its $800 million adjusted EBITDA and $200 million free cash flow targets on four straight calls. Yet the stock has lost more than half its value since the last report. The market is plainly skeptical that the back half of the year can deliver what the company says it will, and this quarter is the last checkpoint before the critical fourth quarter.
The Street is looking for revenue of about $1.05 billion, up 5.3% from $997.0 million a year ago, with earnings per share expected to land around breakeven against $0.63 in the year-ago period. That revenue figure sits squarely on management's own guidance of roughly $1.05 billion, which translated to growth in the mid-single digits. Analysts had been at $1.07 billion before the company spoke, so consensus has already been marked down to the company's outlook rather than sitting above it. That makes a clean revenue match the minimum requirement. A shortfall would be more damaging than usual, because the guide was itself a step up from the low-single-digit forecasts of earlier quarters and was one of the few clearly upbeat signals from the last call.
The real story lies beneath the top line. Last quarter showed two very different businesses. The Digital Audio Group grew 12.4% to $364 million, beating its own forecast, and has now out-earned the broadcast-heavy Multi-Platform Group for six consecutive quarters. Podcasting, though still growing about 21%, has slowed from roughly 27% in the first quarter, and management guided to around 20% for the third quarter. Holding that line would show the deceleration is simply the math of a bigger base. A further step down would suggest the new distribution deals with Netflix, TikTok and the just-announced Disney and Hulu video podcast partnership are not yet moving the needle as hoped.
The Multi-Platform Group remains the pressure point. Revenue slipped 1.6% last quarter, below the flat forecast, and segment EBITDA fell to $59 million from $96 million, extending a slide that has run for several quarters. Management blamed Middle East tensions and high fuel prices for softer ad demand. The company also said non-cash co-marketing expenses, which have weighed on segment profit, should ease in the second half, and broadcast inventory is being made available through Amazon, Google and Yahoo ad-buying platforms, with Amazon slated to go live this half. Any sign that broadcast EBITDA is stabilizing, or that programmatic access is lifting radio pricing, would directly address the market's biggest worry.
Sentiment has turned a bit more bearish than it was ahead of the last report, and the price action is stark. At $1.84, the shares trade well below the 200-day moving average of $3.42 and toward the lower end of a post-earnings range spanning $1.38 to $4.06, a far cry from the $3.39 to $5.36 band of the prior quarter. Expectations are clearly depressed, which lowers the bar for a relief rally but also signals deep doubt about the full-year targets.
That is the crux. As an analyst pointed out last quarter, hitting $800 million implies a fourth quarter bigger than the $315 million posted in the 2022 midterm period, dependent on improving ad markets and heavy political spending. If management reaffirms the target with evidence of firming broadcast trends and strong political bookings, the narrative survives. If it trims the outlook or leans harder on macro caveats, the selloff will look less like overreaction and more like foresight.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-27 | |
| Oct-20 | |
| Oct-19 | |
| Oct-13 | |
| Oct-02 | |
| Sep-17 | |
| Aug-20 | |
| Aug-19 | |
| Aug-12 | |
| Aug-11 | |
| Aug-10 | |
| Aug-07 | |
| Aug-07 | |
| Jul-22 |
