Intercorp Heads Into Q3 Facing An El Nino Provisioning Test After A 20% Slide
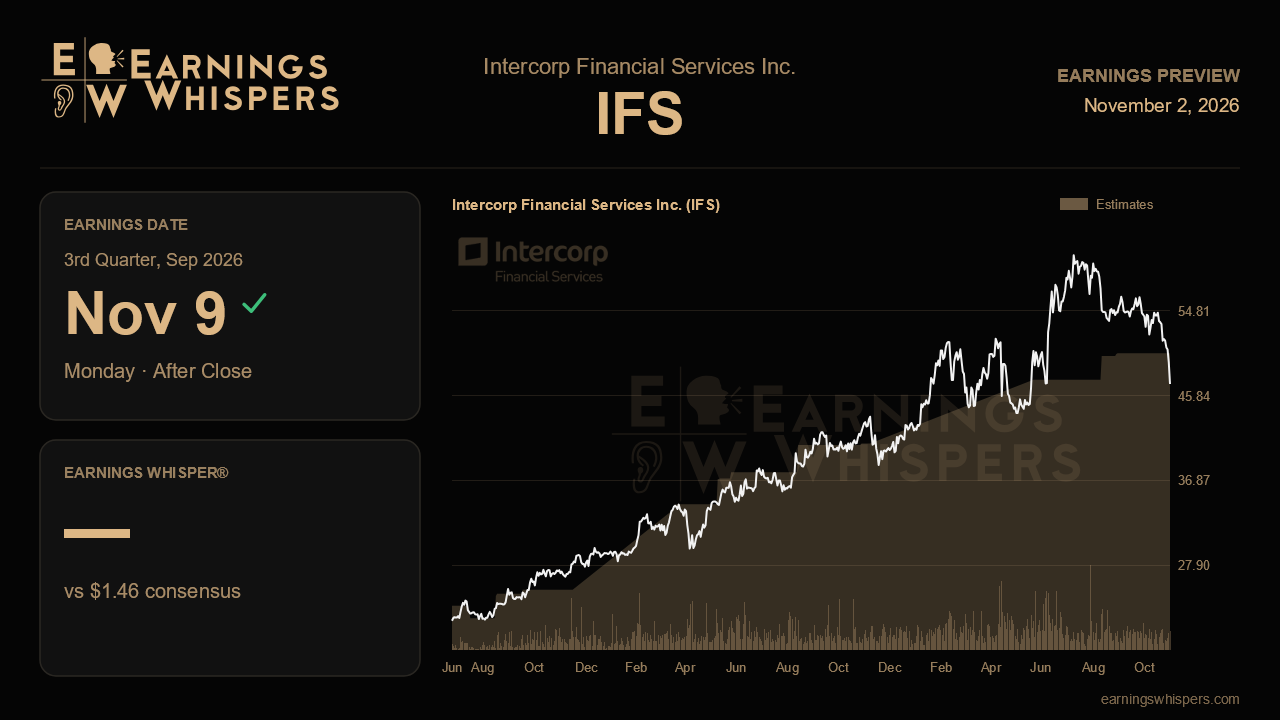
Intercorp Financial Services enters its third-quarter report with an odd split between franchise and stock. The Peruvian lender's loan book is shifting toward higher-yielding segments at an accelerating clip, and its wealth and insurance engines keep setting records. Yet the shares have fallen about 20% since the last report while the S&P 500 slipped only 2.4%. The likely reason is the weather. Last quarter management put El Niño front and center, noting that the odds of a strong-to-extraordinary event late in 2026 had jumped from near zero to roughly 80%, and it flagged forward-looking provisions in the third and fourth quarters. This is the first report where that cost should start showing up.
Wall Street expects earnings of $1.46 per share, about 30% above the $1.12 earned a year ago. That is strong annual growth, but it also sits below the $1.53 posted last quarter, so the consensus already assumes some sequential softening. That makes sense given the setup. Cost of risk rose to 2.1% in the second quarter from an unusually low 1.4% in the first, and management said it should drift toward 2.5% or higher over time as the riskier, higher-yielding mix builds and provisions are booked up front under IFRS. Add a possible El Niño reserve on top, and a dip in profit would not by itself break the story.
Guidance frames the bar. Management kept its full-year targets unchanged at an ROE above 17%, high-single-digit loan growth and a cost-to-income ratio near 37%, even though first-half ROE ran at 18.9%. That conservatism leaves room to absorb a provisioning hit and still land within the range. The real question is the size of the cushion. If third-quarter ROE stays comfortably in the high teens after reserving for El Niño, the guidance will look sandbagged. If it slides toward 17%, the market may conclude that management's caution was warranted, and that the fourth quarter carries more risk.
Margin is the other swing factor. Cost of funds rose 20 basis points to 3.0% last quarter, ending a run of steady improvement, because of inflation-linked funding, the full effect of a bond issue and extra liquidity held through the election period. Management offered two encouraging signals: loan yields were stable for the first time, and net interest margin had already partly recovered in July. A clear sequential margin improvement would confirm that the funding squeeze was temporary, especially as election-period liquidity buffers unwind. With inflation sticky at 4.1% and no further rate cuts expected, a flat or weaker margin would suggest the pressure is more structural.
Growth needs to hold up too. Higher-yielding loans grew 12% from a year earlier last quarter, consumer loans reaccelerated to 9%, and small business lending rose 31%. A new market-friendly government, business confidence at a one-year high and a central bank forecast for stronger domestic demand all support continued momentum. Investors should look for consumer and small business growth to stay at or above those rates, for primary retail customers to keep climbing, and for Intelligo's assets under management to push past roughly $10 billion. Early delinquency trends in consumer and small business books will matter as much as volume.
Sentiment has soured sharply, moving from mildly bullish before the last report to firmly bearish now. The stock trades at $47.06, below its 200-day moving average near $51.80 and just above its post-earnings low of $46.74, so it is testing the bottom of its range. That positioning lowers the bar somewhat. Ultimately, the report turns on one question: can Intercorp absorb the El Niño provisioning and funding pressure while still producing high-teens returns? If it can, the selloff looks overdone. If credit costs jump faster than margin recovers, the cautious guidance will look like a warning rather than a cushion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-15 | |
| Sep-29 | |
| Sep-01 | |
| Aug-12 | |
| Jul-13 | |
| May-12 | |
| Apr-24 | |
| Apr-15 | |
| Feb-17 | |
| Feb-13 | |
| Jan-26 | |
| Jan-20 | |
| Dec-17 | |
| Dec-12 |
