Vertex Misses On EPS As Crinetics And Launch Spending Outpace A Revenue Beat, With CF Growth Cooling Ahead Of Povetacicept Decision
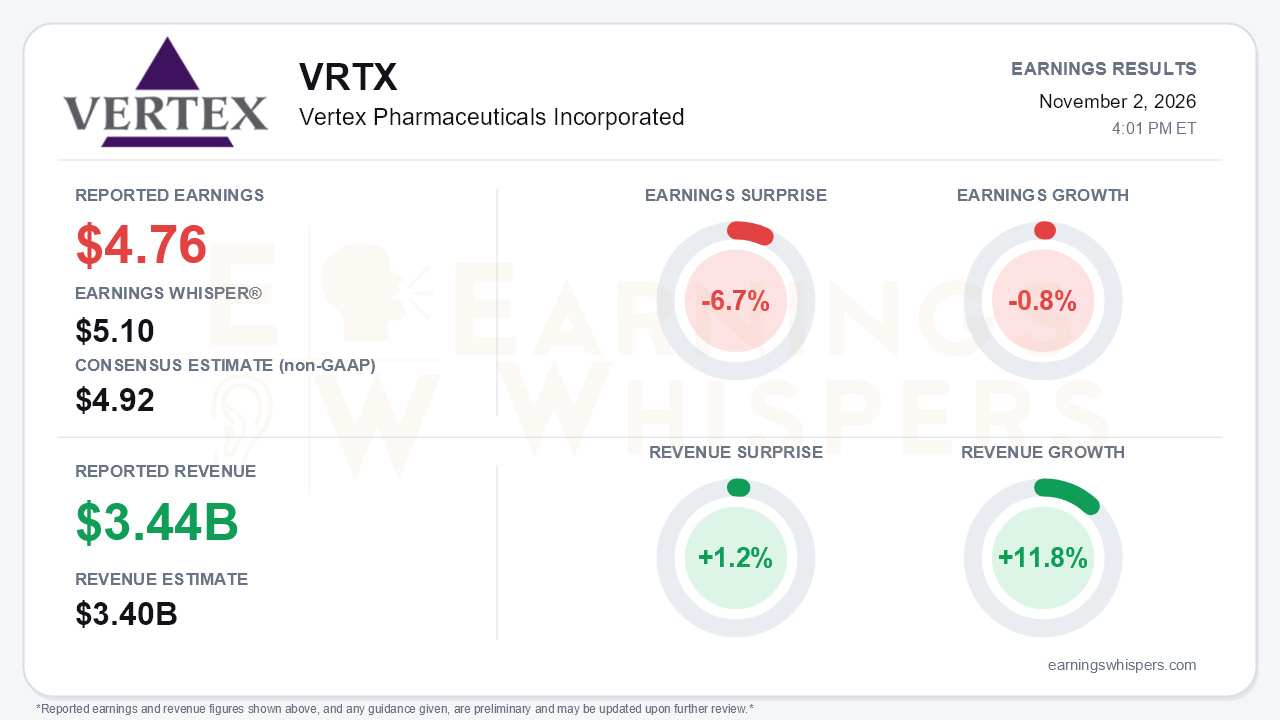
Vertex Pharmaceuticals delivered a top-line beat and a bottom-line miss in the third quarter. Non-GAAP earnings of $4.76 per share fell 6.7% short of the $4.92 consensus and well below the $5.10 Earnings Whisper number, and were down 0.8% from a year ago. Revenue of $3.441 billion rose 11.8% and beat the $3.40 billion consensus by 1.2%. Revenue is still growing at a double-digit clip, but Vertex is spending heavily to build its next franchises, and that spending is currently absorbing all of the incremental profit. The miss was not a demand problem. It was a cost and capital-structure problem the company chose deliberately.
The income statement shows how the gains were absorbed. Combined non-GAAP R&D, AIPR&D and SG&A rose to $1.53 billion from $1.28 billion. Non-GAAP SG&A alone jumped to $556 million from $369 million, driven by the renal field force for povetacicept, the addition of Crinetics, and the JOURNAVX launch. Interest expense climbed to $36 million from $3.3 million after Vertex took on a $4.5 billion term loan. Interest income also declined as cash was used for the roughly $9.0 billion net Crinetics purchase. As a result, non-GAAP operating income grew only marginally, to $1.41 billion from $1.38 billion, and non-GAAP net income was flat at $1.2 billion. GAAP results were far weaker: diluted EPS fell to $2.56 from $4.20 because of about $500 million in Crinetics compensation and transaction charges. Those charges are excluded from the non-GAAP figures but are a real cash and dilution cost of the deal.
The operating trends beneath the headline are mixed. The diversification story is gaining traction:
- CASGEVY revenue reached $99 million, up 30% sequentially from $76 million in Q2 and $43 million in Q1.
- JOURNAVX prescriptions topped 750,000, up more than 40% quarter over quarter, and the drug is now the most prescribed branded oral pain medicine in the U.S.
- PALSONIFY contributed $10 million in September after the deal closed. The call cited roughly $24 million for the full quarter, presumably including pre-close Crinetics sales. It holds more than 40% share among new and switching patients.
The core is cooling, however. Global CF growth slowed to 8% from 11% in Q2, and U.S. CF growth fell to 5% from 9%. TRIKAFTA revenue declined to $2.44 billion as patients converted to ALYFTREK, which reached $706 million. JOURNAVX's revenue growth of 18% sequentially lagged its prescription growth. The gap reflects a one-time Medicare Part D net-price reset and an extended patient support program. Management has also pushed gross-to-net normalization again, to mid-2027. It had previously targeted end of 2026 and then the first half of 2027.
Guidance deserves the same scrutiny. Full-year revenue guidance rose to $13.15-$13.25 billion from $13.1-$13.2 billion. Per the call, the entire increase reflects the $40-$50 million PALSONIFY contribution, and underlying assumptions were left unchanged. Non-GAAP operating expense guidance rose more sharply, to about $6.0 billion from $5.65-$5.75 billion. Gross margin held flat at roughly 85.6% non-GAAP. Management maintained its full-year outlook of slightly below 86% and reaffirmed the target of $500 million or more from CASGEVY and JOURNAVX combined.
The forward catalysts are substantial and near-term. The headline event is povetacicept's November 30 PDUFA date in IgA nephropathy. The renal field force is fully hired, and the RAINIER interim data have been published in NEJM. Risks surfaced on the call as well. These include an anonymous citizen petition challenging the label's IgG monitoring and dose-hold requirements, and investor questions about continuous manufacturing for the biologic. Later milestones include:
- inaxaplin AMPLITUDE interim data in early 2027;
- completion of enrollment in the atumelnant CAH Phase 3 in Q1 2027;
- gMG proof-of-concept data in the first half of 2027;
- suzetrigine DPN Phase 3 results in mid-2027.
On the softer side, the VX-828 data did not by themselves justify advancement, so the next-generation CF decision now waits on VX-581 and VX-272. Vertex also announced a CFO transition effective January 1, and the call noted that cash had fallen to about $9.8 billion from $13.6 billion at Q2.
The market setup heading into the report was demanding. Shares were up 18.6% since the open after the August report, closed within 1% of a 52-week high of $563.80 set on October 30, and sat about 16.7% above the 200-day moving average. Investor sentiment improved from near neutral (0.04) to modestly positive (0.17), a meaningful but not euphoric shift. The Earnings Whispers price, momentum and AVWAP readings were all positive. A stock priced near its highs with rising expectations, a whisper number above consensus, and an approval decision weeks away leaves little room for an earnings miss. That is true even when the miss stems from investment rather than erosion.
The bottom line is that Vertex's quarter was strategically coherent but financially unflattering. Revenue diversification is advancing, and povetacicept could add a fifth franchise within weeks. Meanwhile, slowing CF growth, a guidance raise driven entirely by the acquisition, rising costs, and another JOURNAVX pricing delay give bears legitimate ammunition. With the stock near its highs, the November 30 decision now carries much of the investment case.
Read our earnings preview for Vertex Pharmaceuticals Incorporated: https://www.earningswhispers.com/article/VRTX/21446
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-01 | |
| Oct-27 | |
| Oct-26 | |
| Oct-23 | |
| Oct-23 |
How Halozyme, Up 80% This Year, Is Rivaling Merck And Hitting New Highs
VRTX
Investor's Business Daily
|
| Oct-21 | |
| Oct-20 | |
| Oct-13 | |
| Oct-09 | |
| Oct-09 | |
| Oct-08 |
