Hyperfine's Third Quarter Must Prove The Second-Half Ramp Behind Its 2026 Target Is Real
Hyperfine heads into its third-quarter report with a simple but unforgiving piece of arithmetic hanging over it. The portable MRI maker booked $7.8 million in revenue in the first half of 2026, yet it continues to stand by a full-year target of $20 million to $22 million. That leaves roughly $12 million to $14 million to be generated in the back half, and the September quarter is the first real chance to show that the ramp management has been promising is actually underway rather than being pushed toward a crowded December.
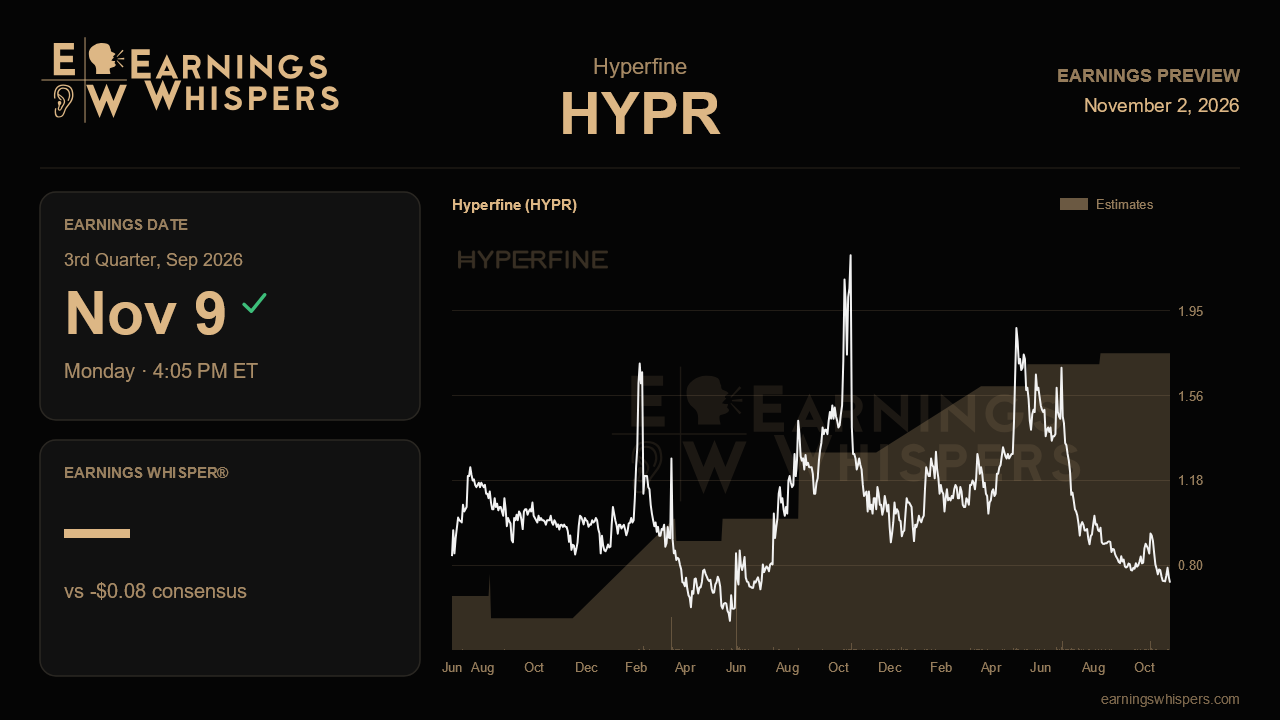
On the bottom line, Wall Street expects a loss of 8 cents a share, an improvement of about 27% from the 11-cent loss a year earlier and a penny better than the second quarter. A narrower loss fits the cost story management has been telling. Cash burn fell 9% in the first half to $16.6 million, and the company's $26 million to $28 million burn guide implies a leaner second half still. The full-year revenue consensus of about $20.5 million sits near the low end of management's range, which suggests analysts believe the company can get there but are not betting on much upside. That positioning matters: hitting the bottom of guidance would likely be read as survival, not success.
The second-quarter call gave the third quarter a specific job. Revenue was flat sequentially at $3.9 million and still well below the $5.3 million peak of late 2025, which had been inflated by a one-time multi-unit upgrade. Management pointed to several reasons the second half should look different: hospital system budget cycles that reset in July, a first placement inside one of the largest national integrated delivery networks in early July, the first two Model 2 sales in Europe and the UK, a debut deployment in India, and inclusion on France's UniHA purchasing list. If those proof points are real commercial engines, the September quarter should show a clear step up from $3.9 million and ideally evidence of follow-on orders within that national network. A result near the year-ago $3.4 million or another flat print would make the implied fourth quarter look heroic and invite questions about whether the guide survives.
Beyond the top line, the details will help separate durable momentum from timing luck. Gross margin has held above 50% for four straight quarters, and keeping it inside the 50% to 55% guided band while international and office mix grows would support the view that scale is coming without discounting. The contrast imaging study was about 75% enrolled last quarter, up from roughly 20% at the start of the year, and confirmation that the FDA submission remains on track for year-end would keep a meaningful product catalyst alive. Updates on the office channel, which had passed a dozen sites, and on the neurosurgery operating room pilots will indicate whether newer use cases are moving toward revenue.
The market has not been patient. Shares have fallen 26% since the last report, roughly 24 points worse than the S&P 500, and at $0.72 the stock is trading well below its 200-day moving average of $1.13 and just above its post-earnings low of $0.70. The trading range has also shifted decisively lower from the prior quarter's band of $0.88 to $1.75. That weakness carries practical weight, since the company leaned on $10.6 million of at-the-market stock sales last quarter, and raising capital at sub-dollar prices is far more dilutive. Curiously, sentiment readings have warmed considerably, climbing to 48% bullish from under 12% heading into the prior report, which hints that some investors see the selloff as overdone.
Ultimately, this report comes down to whether Hyperfine can turn a growing list of first placements into recurring, multi-unit demand fast enough to make its reaffirmed guidance credible. A visible sequential revenue jump, steady margins and continued burn discipline would validate the company's shift from talking about inflection to proving execution. Anything that leaves the full-year target dependent on an outsized fourth quarter would challenge that narrative at a moment when the share price leaves little margin for error.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-22 | |
| Oct-08 | |
| Oct-08 | |
| Oct-08 | |
| Sep-28 | |
| Sep-15 | |
| Aug-31 | |
| Aug-26 | |
| Aug-20 | |
| Aug-07 | |
| Aug-06 | |
| Aug-05 | |
| Jul-30 | |
| Jul-23 |
