NHI's First Quarter Without NHC Rent Tests Its Senior Housing Growth Pivot
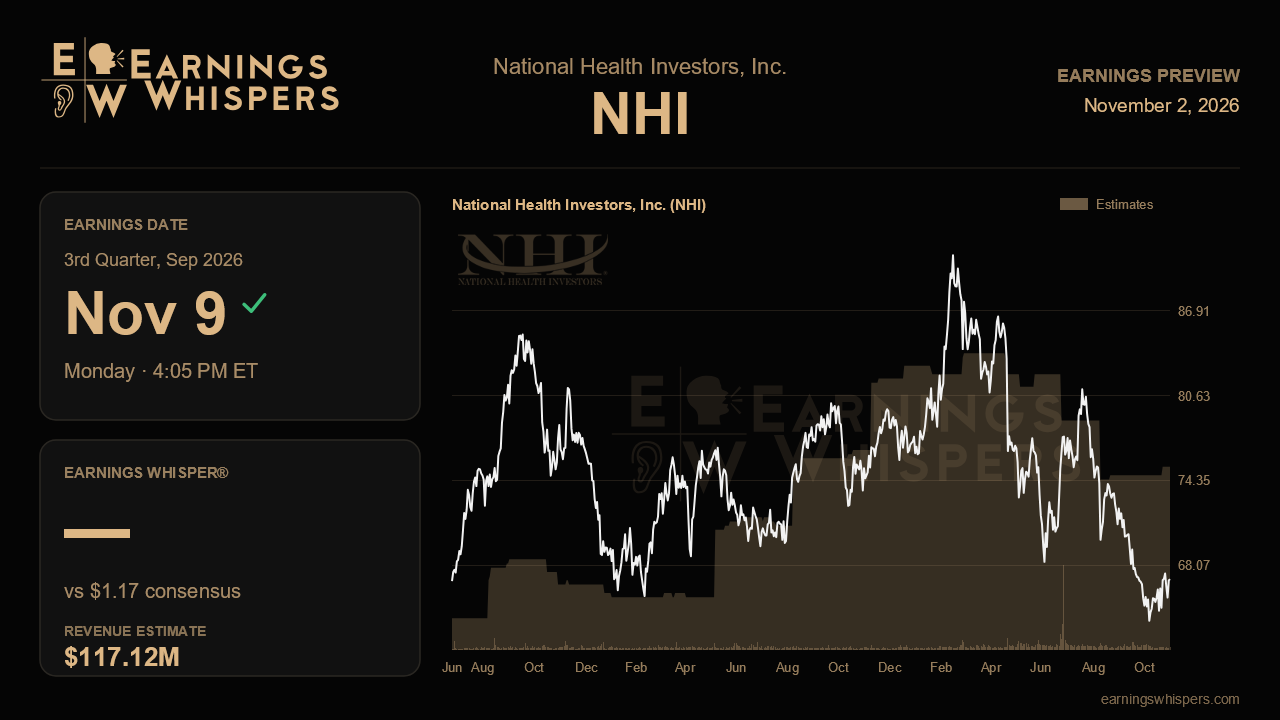
National Health Investors has spent the past year telling investors that a smaller, cleaner, more private-pay portfolio will eventually earn more than the one it replaced. The third-quarter report, due after the close on November 9, is the first full period since the $560 million NHC portfolio sale closed on July 1. That makes it the first clean look at what the company earns after giving up a large block of reliable triple-net rent, and at whether its growing senior housing operating platform can begin to close the gap.
The Street expects normalized FFO of $1.17 per share, down 11.4% from $1.32 a year ago and slightly below the $1.19 posted last quarter. Revenue is projected at $117.1 million, up about 30% from a year earlier. That gap between rising sales and falling per-share earnings is the pivot in miniature. Operating senior housing properties are reported on a gross basis, which inflates revenue, while the NHC sale removes high-margin rent and the expanding platform carries heavier overhead. Reported GAAP earnings will also be distorted by the roughly $541.6 million gain on the NHC sale, so the FFO figure is the one that matters. The more uncomfortable detail is guidance. Management reaffirmed 2026 FFO of $4.74 to $4.79 per share, yet the full-year consensus sits at $4.87, above the top of that range. Either analysts are leaning on faster redeployment than the company has committed to, or estimates still have room to drift lower. A quarter near $1.17 would help reconcile the two; anything weaker would put pressure on the full-year number.
The operating story centers on same-store performance. Management cut its same-store operating portfolio growth outlook twice this year, from an original 13% to 16% down to 1% to 3%, and merely reaffirmed that reduced range last quarter. Hitting even the lower target requires a back-end loaded second half with growth of roughly 8% to 9%. The legacy Holiday-operated pool is the biggest obstacle, with year-over-year NOI declines worsening for three straight quarters to 6.3%, and one building with offline units dragging occupancy until year-end. A further sequential improvement on top of last quarter's 18.9% rebound would validate the turnaround narrative. Another step down in the Holiday pool, or no update on the strategic solution for a subset of those properties that management targeted to complete this year, would challenge it.
Capital deployment is the second test. Leverage fell to 4.1 times net debt to EBITDA, liquidity is about $792 million, and management raised its acquisition ambition to $500 million to $700 million a year, more than the prior framing. Signed letters of intent totaled $127.3 million, mostly senior housing, but initial yields have compressed to about 6.8% from roughly 8% a year ago. The roughly $334 million earmarked for tax-deferred 1031 reinvestment carries a deadline, and a shortfall raises the possibility of a special dividend, which would return cash but shrink the earnings base. Investors should look for closed deals, a fuller pipeline, and evidence that G&A, which jumped 44% last quarter partly on CFO transition costs, is settling down.
The market has not given management the benefit of the doubt. Shares are down 8.2% since the last report, trailing the S&P 500 by nearly six points, and at $67.04 they sit well below the 200-day moving average of $76.40, nearer the bottom of their post-earnings range and beneath last quarter's low. Sentiment has edged from mildly bearish to mildly bullish, but the price action points to a skeptical audience.
Ultimately, this report needs to show that the senior housing engine is accelerating fast enough to replace NHC income. Credible second-half same-store momentum, visible progress on reinvestment, and comfort with the full-year FFO range would keep the pivot thesis intact; continued Holiday deterioration and slow deployment would make the dilution look less temporary.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-07 | |
| Oct-01 | |
| Sep-14 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-27 | |
| Jul-15 | |
| Jun-23 | |
| May-04 | |
| May-04 | |
| May-04 | |
| May-04 |
