Upwork Squeezes Out Higher Margins And A Guidance Raise, But A Shrinking Marketplace Remains The Core Problem
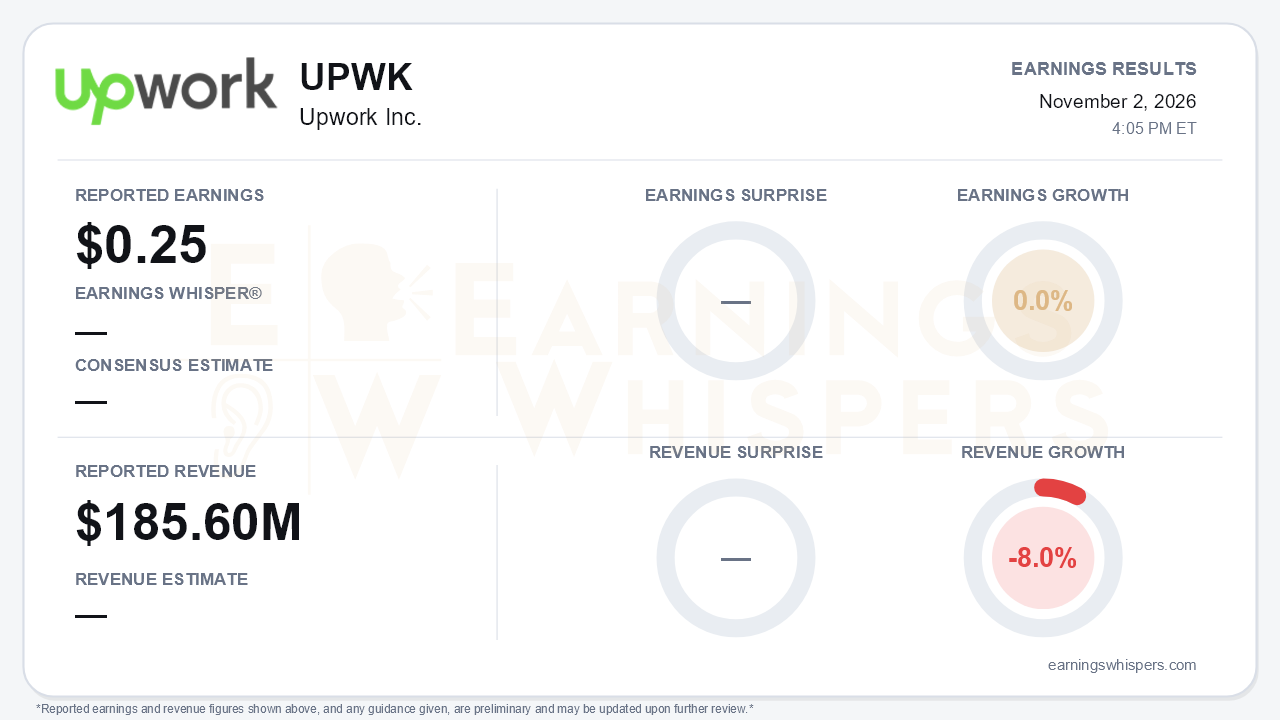
Upwork's third quarter showed a company getting more profit out of a smaller business. Reported EPS was $0.25 on revenue of $185.6 million. On Earnings Whispers' basis, earnings were flat year over year (0.0%) and revenue fell 8.0%. The release itself shows GAAP diluted EPS of $0.25 against $0.21 a year ago, and non-GAAP diluted EPS of $0.40 against $0.36, so the earnings picture looks somewhat better or flat depending on the measure. No consensus figures were supplied. The more useful benchmark is Upwork's own outlook. Revenue and adjusted EBITDA of $63.8 million both cleared the $176-184 million and $50-54 million ranges given in August. Full-year guidance moved up as well. Underneath those wins, though, the marketplace kept shrinking, and that is the central tension.
The quality of the beat deserves scrutiny. Gross services volume (GSV) fell 10.1% year over year to $914.1 million and slid sequentially from $966 million. Active clients dropped 10% to 717,000, down from 763,000 in Q2 and 785,000 at the end of 2025. Gross margin slipped about 115 basis points to 76%. The 481-basis-point jump in adjusted EBITDA margin to 34.4% came almost entirely from cost reduction:
- Operating expenses fell 15%.
- R&D dropped from $47.5 million to $34.9 million after the May restructuring.
- Stock-based compensation was more than halved to $9.2 million.
The share count also shrank meaningfully, to 128.3 million diluted shares from 139.7 million, which flatters per-share results. Free cash flow of $53.9 million recovered sharply from $35.9 million in Q2 but was still down 22% from a year ago, as capitalized software spending rose.
The call preserved some legitimate positives inside the core business:
- **Take rate.** It kept climbing, from 19.0% in Q4 2025 to 20.0% this quarter.
- **Spend per client.** GSV per active client rose 8% year over year to $5,418, an acceleration from 5% growth in Q2.
- **Business Plus.** The SMB offering reached 8% of GSV, well ahead of the 5% goal.
- **AI work.** GSV from AI-skilled freelancers grew 55%.
The pattern is consistent: fewer clients, but higher-value ones paying more. The problem is the pace of decline at the low end. Management attributed it to low-value work rotating to AI tools and continued Google SEO pressure, and said those headwinds should persist through the first half of 2027. Business Plus growth also decelerated, to 132% from 174%.
The forward-looking developments cut both ways. On the positive side:
- **WorkMotion.** The acquisition, an EOR provider growing roughly 20%, deepens the Lifted enterprise push. It lifted Lifted's 2026 GSV growth target to more than 30%, from about 25%.
- **Lifted momentum.** The unit signed three new logos and accelerated enterprise migrations.
- **New AI channels.** The MCP server already shows more than $3 million in annualized Connects revenue, and MCP-originated GSV rose more than 150% month over month in October. Upwork Now gives AI agents and clients real-time access to available freelancers.
These are early-stage options, not yet needle-movers. Bears have legitimate ammunition on several fronts:
- **Q4 guidance.** Revenue of $169-177 million implies a decline both sequentially and year over year. The adjusted EBITDA margin midpoint of about 31% is a step down from 34.4%.
- **Quality of the raise.** The revenue raise is roughly offset by about $4 million of WorkMotion contribution and a lower-margin managed-services project leaving the platform.
- **Distance from original guidance.** Full-year revenue of $742-750 million remains far below the $835-850 million originally guided.
- **2027 margins.** Management expects 3-4 points of EBITDA margin dilution next year from Lifted mix and integration costs.
- **Visibility and leadership.** Management cited limited GSV visibility for 2027, and CFO Erica Gessert departs January 1, with Chief Business Officer Peter Sanborn succeeding her.
The balance sheet changed meaningfully too. Upwork used $361 million to retire its convertible notes, leaving it debt-free but with a much smaller cash and securities cushion than at year-end.
The market setup was already skeptical. Investor sentiment stood at a clearly negative -0.54 following the August report. Shares opened at $8.04 the day after that release, well below the 200-day moving average now sitting at $10.66. That suggests investors had largely priced in the marketplace erosion before this report. Updated sentiment and price data were not available, so it is not yet clear whether the guidance raise and new AI channels shifted that stance. The fundamental evidence argues for caution rather than a reset. Margin expansion driven by cost cuts is about to reverse, and the volume declines have not yet bottomed.
The bottom line is that Upwork delivered a cleaner quarter than its revenue decline suggests. It beat its own targets, raised full-year guidance, and showed real progress in take rate, high-value clients and AI-driven channels. The core marketplace is still shrinking, however, and Q4 points lower again. Next year brings margin dilution, a new CFO and limited visibility. Until GSV and active clients stabilize, the profitability story is doing the work that the growth story cannot.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 5 hours | |
| 7 hours | |
| 8 hours | |
| Oct-12 | |
| Oct-08 | |
| Aug-26 | |
| Aug-20 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Aug-10 | |
| Jul-21 | |
| Jul-14 |
