Onto Innovation's Record Backlog Faces A Skeptical Market After A One-Third Slide
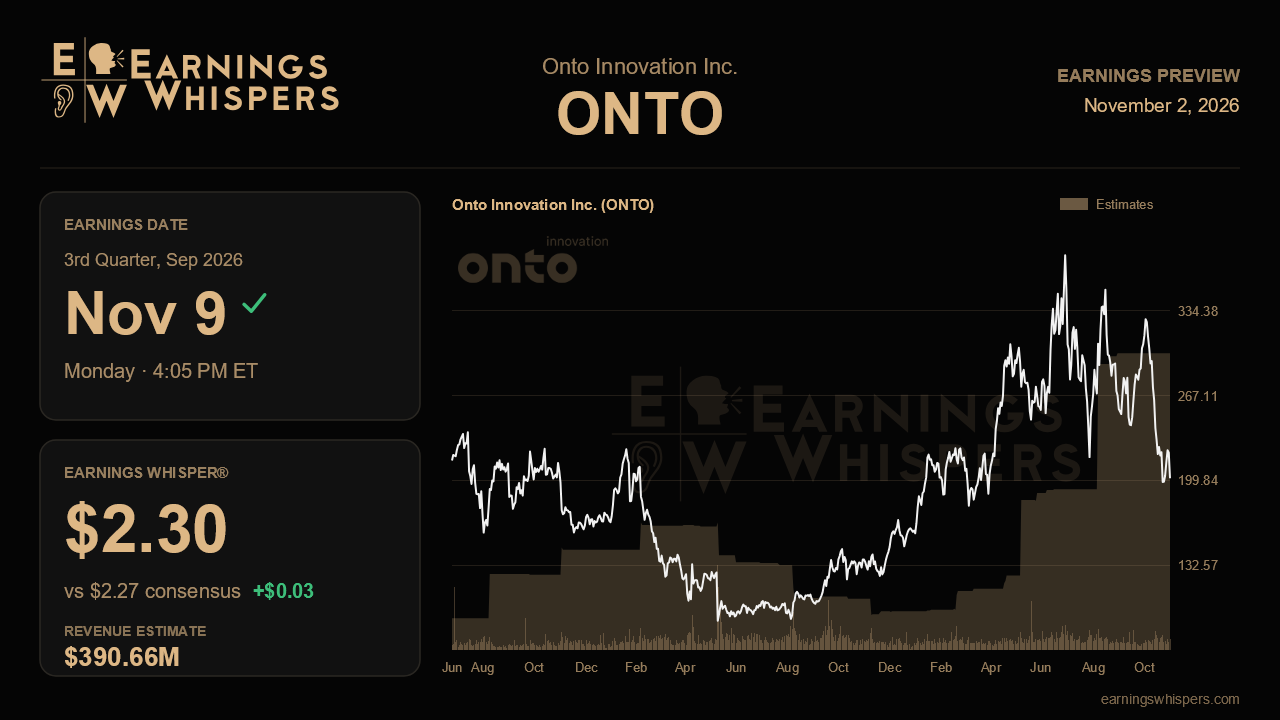
Few semiconductor equipment stories looked cleaner three months ago. Onto Innovation raised every major guidance figure for the third straight quarter, reported a record backlog above $1.1 billion, and described AI-driven demand visibility stretching into 2027. The stock has since fallen nearly 33%, trailing the S&P 500 by about 31 percentage points. When the company reports third-quarter results after the close on November 9, the question is less whether Onto can hit its numbers and more whether the market still believes the numbers that come after them.
The near-term bar is clearly defined. Consensus calls for EPS of $2.27 on revenue of $390.7 million, which sits almost exactly at the midpoint of management's guidance of $2.18 to $2.38 per share and $380 million to $400 million in revenue. Those figures imply EPS growth of roughly 147% and revenue growth of 79% from the year-ago quarter's $0.92 and $218.2 million, an extraordinary step up for an instrument maker. The Earnings Whisper of $2.30 is only slightly above consensus, so the unofficial bar is not demanding a blowout. That fits Onto's recent pattern of beating its own guidance. Clearing the midpoint is the minimum. A quarter near the top of the range, plus a fourth-quarter outlook that again moves higher, is what would answer the doubters.
The previous call gives investors a detailed checklist. Management lifted its full-year growth target for advanced packaging from above 30% to about 50% and then to about 80%. Advanced nodes went from roughly 15% to more than 35%. Second-half revenue is now framed as more than 25% above the first half. Advanced nodes revenue jumped 50% sequentially to about $120 million in the second quarter, led by memory, and multiple Atlas G6 systems are slated for a major DRAM customer in the second half. Evidence that memory and logic shipments stayed strong, and that packaging tools such as Dragonfly G5 are shipping on schedule, would support the claim that the ramp is broad rather than concentrated in a single quarter. Investors should also watch whether backlog holds near record levels. The $200 million-plus OSAT Dragonfly order mostly ships in 2027, so a stable or growing backlog would signal that new bookings are keeping pace with deliveries.
Margins may be the most important test. Gross margin reached 57% in the second quarter, and management raised its full-year expansion target to 350 basis points while promising to exit the year with operating margin above 33%. Several risks could undercut that path. Management cited higher costs for materials, fuel and freight, longer lead times for precision optics, and rising inventory held to protect supply. If gross margin stalls or inventory grows faster than revenue, the market may conclude that rapid growth is coming at a higher cost than expected. Steady margin gains alongside stronger shipments would instead show genuine operating leverage. Smaller items include silicon photonics orders, which have already topped $50 million, and whether the specialty business stays flat rather than slipping as power and EV markets remain soft.
Sentiment has improved modestly, rising to 27% bullish from 20.6% before the last report, though that is hardly euphoric. Technically, the stock looks battered. At $201.57 it sits well below its 200-day moving average of $260.75 and just above its post-earnings low of $195.19, far from the $353.84 high. A drop below that low would erase most of the past two quarters' gains and tell a story of eroding confidence, not of weak earnings.
That gap between operating results and the stock price is the core of the setup. Onto's narrative depends on whether the record backlog converts into revenue at expanding margins and whether the fourth-quarter outlook keeps moving higher. If management confirms the second-half trajectory and the margin targets, the recent selloff will look like doubt about the cycle rather than about the company. If the guidance merely holds steady, the market may treat that as the first sign that the run of raises has peaked.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Oct-28 | |
| Oct-19 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-07 | |
| Oct-05 | |
| Oct-02 | |
| Oct-02 | |
| Sep-30 | |
| Aug-17 | |
| Aug-17 | |
| Aug-10 |
