Paysign's Q3 Test: Can Program Growth And A Plasma Recovery Justify A 35% Rally?
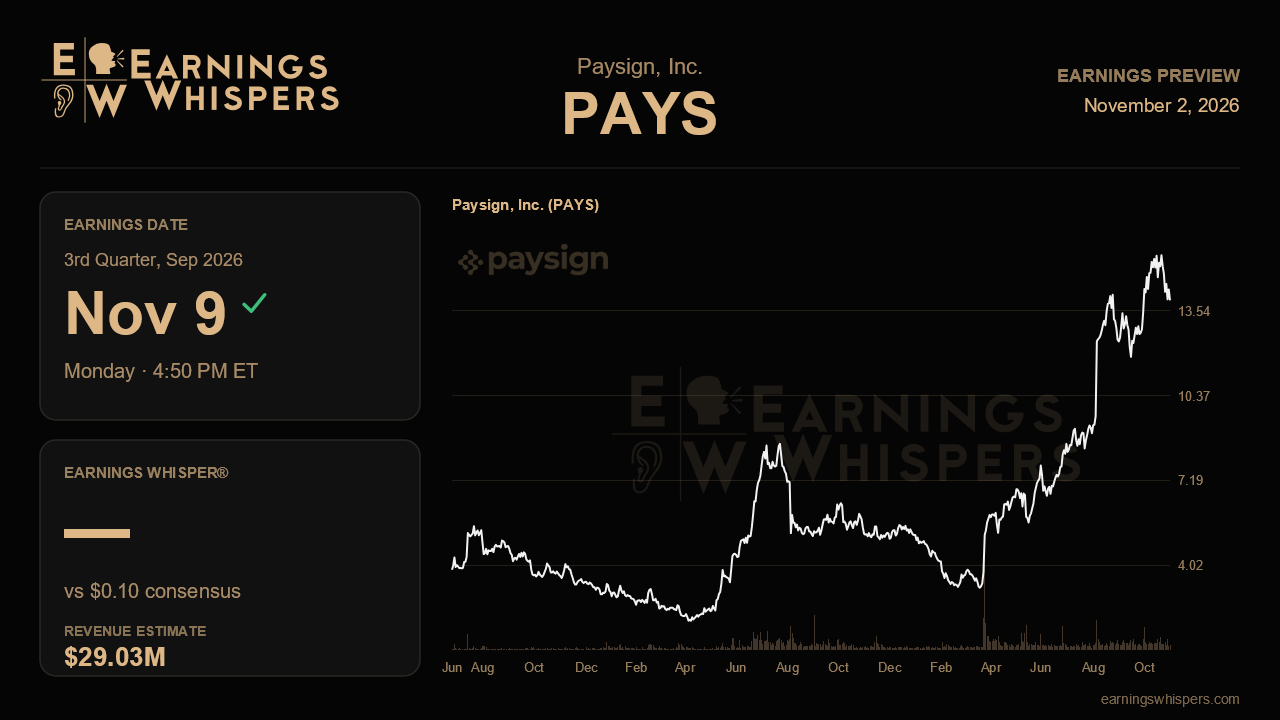
Paysign enters its third-quarter report with the rare combination of raised guidance, accelerating fundamentals and a stock that has already priced in a good deal of that good news. Shares have climbed about 34.5% since the last report while the S&P 500 slipped, so the question on November 9 is less whether the business is ramping and more whether it can keep outrunning a bar that management itself has been lifting.
The Street is looking for earnings of $0.10 per share on revenue of about $29.0 million, which would be roughly 34% revenue growth and a 150% jump in EPS from the $0.04 earned a year ago. Those figures sit squarely within management's third-quarter outlook of $0.09 to $0.10 per share and $28.5 million to $30.0 million in revenue, though the EPS estimate is pinned at the top of the range while revenue is near the midpoint. That matters because Paysign has made a habit of clearing its own guidance: second-quarter revenue of $28.3 million topped a $26.2 million to $26.7 million guide, following a similar beat in the first quarter. Another quarter at the high end of the revenue range would extend that streak, while a print merely in line would be a subtle change in rhythm for a company that has trained investors to expect upside.
The patient affordability business remains the engine. Revenue there rose 89% last quarter to $14.6 million, and active programs reached 148, with the company exiting July at 157 and targeting 165 to 170 by the end of September. Hitting that program count is probably the single cleanest validation of the growth story, since new copay assistance programs tend to generate claims and revenue over subsequent quarters. Falling short would raise doubts about the reaffirmed goal of more than 55 net additions this year and, by extension, the pipeline visibility management says now stretches into 2027. Growth rates in this segment will naturally cool as the base grows, so the absolute dollar gain is a better gauge than the percentage.
Plasma is the second test. After roughly 18 months of inventory-driven pressure, segment revenue grew about 21% last quarter and revenue per center recovered to $7,699, its best level since the third quarter of 2024. Management said the overhang had largely normalized. Sustaining per-center revenue near that level would confirm the recovery is real, which is especially important because the center count has been shrinking, falling to 561 from 595 a year earlier as low-performing sites closed. If per-center productivity slips while closures continue, plasma could quickly revert from tailwind to drag.
Margins round out the picture. Gross margin was 63.3% last quarter against a raised full-year target of 62% to 63%, and adjusted EBITDA margin reached 34%. Management has already flagged a fourth-quarter step-down tied to a higher tax rate, holiday capitalization effects and early hiring, so commentary about how steep that dip will be may move the stock as much as the third-quarter numbers. Updates on the BECS donor management system, still awaiting FDA review without a timeline, and the new Irish subsidiary aimed at international life-sciences software are longer-dated options rather than near-term drivers.
Sentiment has turned a bit more skeptical, with bearish readings rising to 18.7% from 12.4% ahead of the prior report, an understandable reaction after such a sharp run. At $13.93, the stock trades far above its 200-day average of $8.31 but below its post-earnings high of $16.15, suggesting some profit-taking has already occurred. The narrative stays intact if Paysign lands revenue near the top of its range, delivers the promised program count and shows plasma productivity holding firm. Anything less would invite the market to treat the full-year raise as the peak rather than a waypoint.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-16 | |
| Oct-13 | |
| Aug-27 | |
| Aug-18 | |
| Aug-06 | |
| Aug-05 | |
| Aug-04 | |
| Jul-14 | |
| May-27 | |
| May-13 | |
| May-12 | |
| May-11 | |
| Apr-15 | |
| Mar-24 |
