Alliance Laundry Must Prove Margin Gains Can Outrun International Slowdown After Stock's Slide
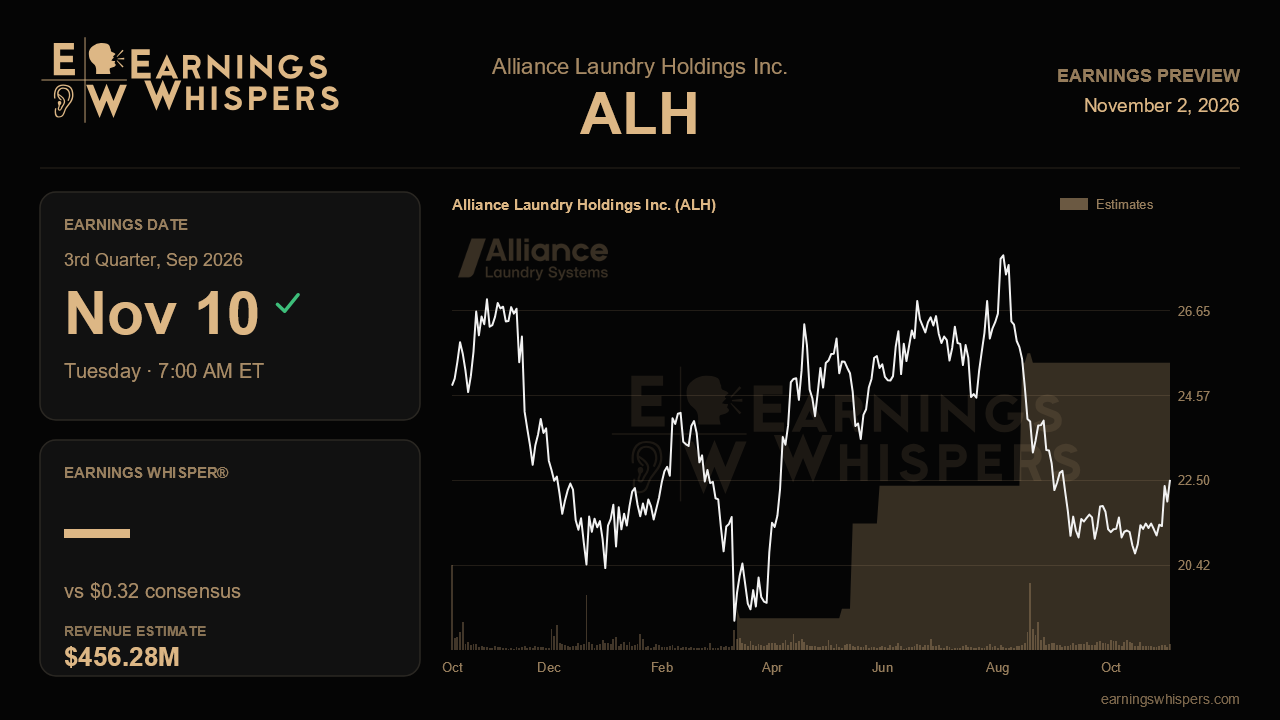
Alliance Laundry heads into its third-quarter report with a curious disconnect. Management has raised its full-year adjusted EBITDA outlook three times in a row, cut its leverage target and described domestic demand as uniformly healthy. Yet the stock has fallen 19.5% since the last report, trailing the S&P 500 by more than 16 percentage points. The November 10 release, due before the open, needs to show whether the market is overreacting to a cooling international business or sensing that the margin story has peaked.
The Street expects earnings of $0.32 per share on revenue of $456.3 million, which would mark 14.3% EPS growth on a 4.3% revenue increase from a year ago. That gap between the top and bottom lines is the core of the bull case: falling interest costs, a lower tax rate and margin expansion turning modest sales growth into double-digit earnings growth. The revenue figure, though, deserves a closer look. Management reaffirmed 2026 sales of $1.81 billion to $1.83 billion, and consensus of $1.82 billion sits squarely at the midpoint. But the company's 6% to 7% full-year growth target implies a stronger pace than the roughly 4% the Street pencils in for this quarter. A miss on revenue would raise questions about whether the reaffirmed range leans on an aggressive fourth quarter.
The biggest swing factor is international. That segment went from 12% growth to 10% and then to roughly flat last quarter, with its margin slipping to 28.9% from 30.4%. Management pinned much of the weakness on the Middle East and Africa, a region under 2% of sales where Saudi Arabia and the UAE paused orders and shipping was delayed, and said it did not expect a recovery this year. The more consequential issue is Europe, where higher energy costs left demand steady but somewhat slower. If international stays near flat and margins stabilize, the explanation that this is a contained, regional problem holds. If Europe deteriorates further or segment growth turns negative, the slowdown starts to look broader than management suggested.
North America carries the other half of the test. The segment delivered 9% revenue growth and a margin near 31.6% in the second quarter, but that period included a $3.8 million one-time benefit from tariff refunds and business interruption insurance. Even excluding it, segment EBITDA rose about 12%, a strong underlying result. The bar this quarter is whether margins remain well above the 27% to 28% range of prior quarters without that help. Consolidated adjusted EBITDA margin of 28.1% last quarter will be hard to match cleanly, so investors should judge results against the year-ago comparison rather than the flattered second quarter. Any additional tariff refunds, which were not built into guidance, would be upside.
Deleveraging is the quieter but more reliable lever. Net leverage fell to 2.4x from 4.6x over the past year, rating upgrades trimmed borrowing costs, and the year-end target is now 2.0x. Continued debt paydown in the quarter would confirm that cash generation is tracking plan. Also worth monitoring are management's early views on 2027, given its warning that steel and inflation look a bit hotter than normal with steel costs locked only through the first quarter, and any update on the finance and investor relations transitions.
Sentiment has improved modestly from the prior quarter but remains on the bearish side, and the stock at $22.51 sits below its 200-day average and closer to the bottom of its post-earnings range of $20.40 to $27.96. That suggests a skeptical crowd. The report will turn on a simple question: can North American strength and lower financing costs keep pushing the EBITDA guidance higher while international weakness stays confined to a small corner of the business? A fourth consecutive raise would challenge the market's doubts; a reaffirmation paired with softer revenue would validate them.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-02 | |
| Nov-02 | |
| Oct-27 | |
| Sep-02 | |
| Aug-18 | |
| Aug-17 | |
| Aug-17 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Jul-29 | |
| Jun-29 | |
| Jun-02 | |
| May-12 |
