Autolus Faces A Credibility Test On Obe-Cel Momentum As Shares Slide Below Range Lows
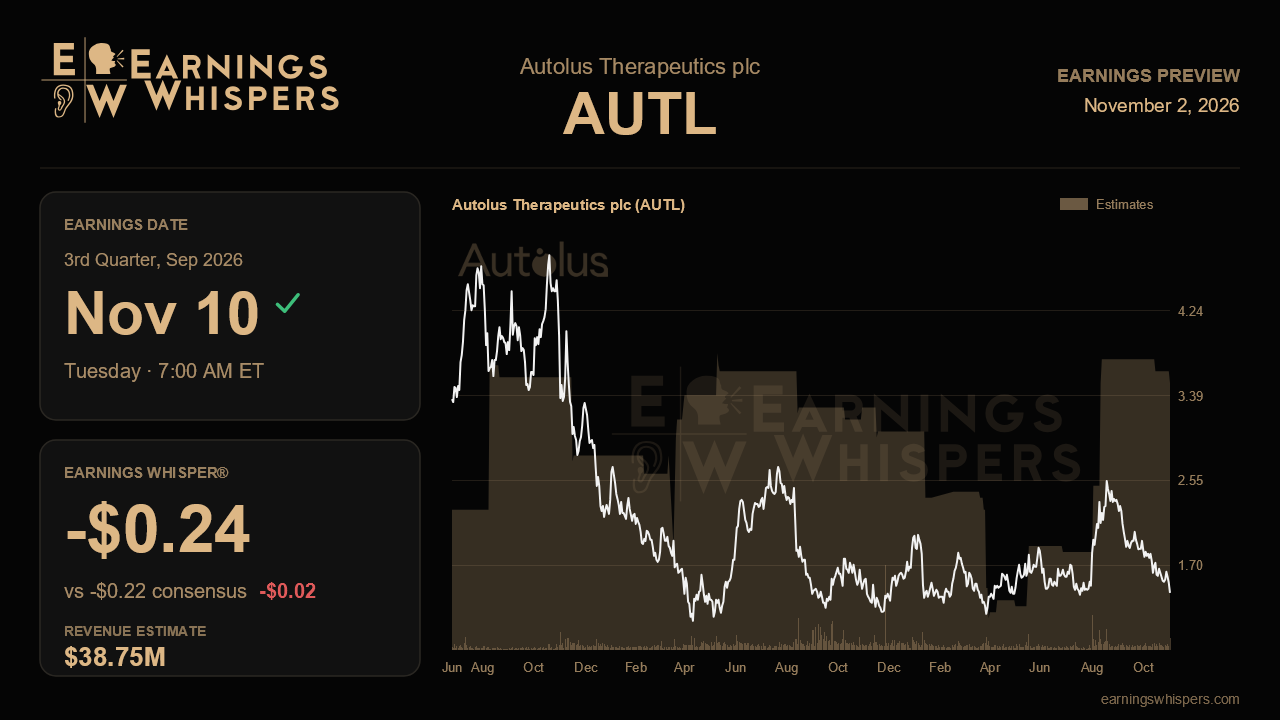
Three months ago Autolus finally gave investors the quarter they had been waiting for: revenue that nearly doubled sequentially, a gross margin that leapt into positive territory, and the first raise to annual guidance since the obe-cel launch began. The market's response since then has been a shrug that turned into a slump. Shares have fallen about 30% since that report, badly lagging a roughly flat S&P 500. That gap between operating momentum and stock performance is what makes the November 10 report, due before the open, so consequential. Autolus needs to show that the second quarter was a new baseline and not a high-water mark.
The Street is not asking for a repeat. Consensus calls for revenue of $38.8 million, up nearly 83% from the year-ago $21.2 million but down about 15% from the second quarter's $45.7 million. The loss estimate of $0.22 per share would be a meaningful improvement from the $0.30 lost a year ago, yet wider than last quarter's $0.15. The whisper number sits a touch lower at a $0.24 loss, a small difference that nonetheless hints at modest caution about spending or margins rather than any expectation of an upside surprise.
That sequential dip is largely management's own framing. Full-year guidance of $140 million to $150 million, raised from $120 million to $135 million after holding steady for several quarters, implies second-half revenue of roughly $68 million to $78 million against a first half of $71.9 million. Management attributed that implied flattening to seasonality and prudence, not softer demand. The Street's $143.8 million full-year estimate sits in the lower half of the range, and simple arithmetic shows it assumes a fourth quarter near $33 million after the third-quarter estimate. In other words, analysts have built in a fair amount of deceleration. A third quarter that lands near or above $40 million would suggest the conservatism was just that, and would put the top end of guidance clearly in play.
The operational evidence matters as much as the headline numbers. Gross margin jumped to 55% from 6% in the first quarter, helped by higher batch volumes, moving clinical production into the Nucleus facility and cost savings from the April workforce reduction. The key question is whether that margin holds if volumes ease seasonally, since manufacturing leverage cuts both ways. Management also said peak margins of 65% to 70% for the leukemia indication are still 12 to 18 months away, so stability rather than another leap would be a reasonable outcome. On the commercial side, activated U.S. treatment centers rose to 82 with a target of more than 90 by year-end; steady progress toward that goal would support the claim that obe-cel is taking share of the CAR-T market. Investors should also look for SG&A to retreat from the $41.2 million level that included one-time restructuring costs, and for an early read on interest expense from the new $250 million Perceptive credit facility, which pushed the cash runway into the second quarter of 2028. Any color on the UK launch, still under 10% of U.S. sales, would be a bonus.
Sentiment has warmed considerably, rising to about 45% bullish from 11% heading into the last report, yet the stock has moved the other way. At $1.42, shares trade below their 200-day moving average of $1.66 and beneath the $1.48 low set since the last report, approaching the prior quarter's $1.38 floor. That leaves little optimism priced in.
Ultimately, this report hinges on whether Autolus can show that demand and margins are durable enough to make the guidance raise look conservative. Revenue comfortably above the Street's discounted estimate with margins holding near mid-50s would reinforce the shift from building to scaling. A sharper revenue dip or margin giveback would hand skeptics the argument that the second quarter was a one-off.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-04 | |
| Nov-03 | |
| Nov-02 | |
| Oct-26 | |
| Oct-05 | |
| Sep-09 | |
| Aug-11 | |
| Aug-11 | |
| Aug-03 | |
| Aug-03 | |
| Jul-01 | |
| Jun-30 | |
| Jun-25 | |
| Jun-12 | |
| May-27 |
