Gilat Faces A Credibility Test As Stock Slumps Ahead Of A Back-Loaded Year End
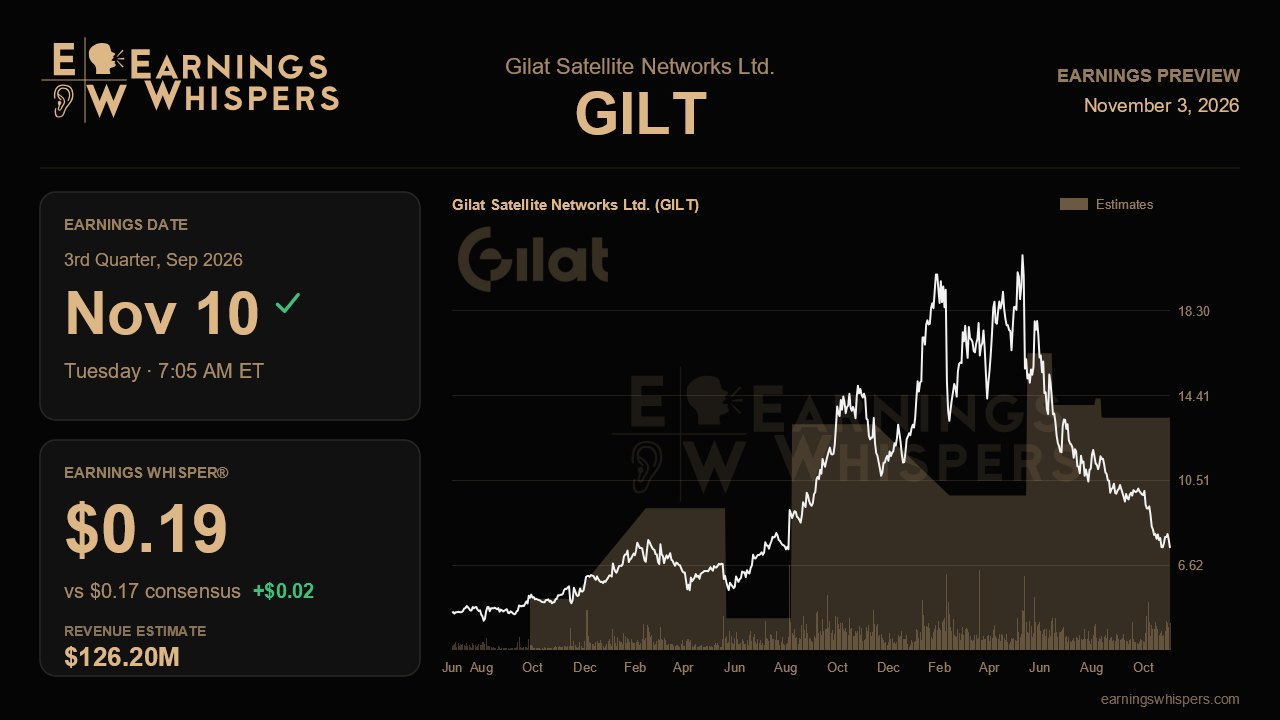
Gilat Satellite Networks heads into its third-quarter report with a striking disconnect. Last quarter management sounded more confident than it had in a year, unveiling a deal to buy most of Comtech's satellite and space communications business, citing record in-flight connectivity terminal deliveries and pointing to fresh defense orders. The market's reply has been brutal. Shares have fallen 36.5% since that report, trailing the S&P 500 by more than 33 percentage points. This release needs to show whether the operating story still holds or whether investors spotted cracks that management played down.
The Street expects earnings of $0.17 a share on revenue of $126.2 million. The revenue figure would be up 7.2% from a year ago, a clear slowdown from growth of 20% in the first quarter and 17% in the second. The Earnings Whisper sits at $0.19, a bit above consensus. That suggests some investors think profit can top the published number despite the gloomy price action, but even the whisper only matches last year's $0.19, so the bar does not call for earnings growth. Management has kept its full-year revenue outlook at $500 million to $520 million, and consensus of $509.6 million sits near the midpoint. The calendar is the catch. First-half revenue was $233.1 million, so if third-quarter sales land near $126 million, Gilat would need about $150 million in the fourth quarter to hit consensus. That makes the year heavily back-loaded and puts real weight on any comments about fourth-quarter visibility.
The most important operating question is gross margin. Non-GAAP gross margin fell to 32% in the second quarter from 36% in the first, which management blamed on a less favorable commercial deal mix. That undid the margin-improvement story the company had told just one quarter earlier. A rebound toward the mid-30s would support the view that the dip was a one-off. Another quarter near 32% would raise doubts about pricing power in commercial programs. Margin also matters because management warned that a stronger shekel could add $3 million to $5 million of operating expenses in the second half. Adjusted EBITDA guidance of $61 million to $66 million has not changed across four calls, so watch whether currency costs start squeezing it.
In-flight connectivity is where the growth story has the most to prove. Gilat delivered more than 200 Sidewinder terminals last quarter, a record, and its installed base reached roughly 600 units. New IFC orders of $43 million topped the prior quarter. Continued delivery strength and steady order intake would back up the claim that IFC is accelerating. Investors should also look for confirmation that Boeing line-fit deliveries remain on schedule for the fourth quarter and for signs of progress on the Airbus first order. Working capital also bears watching. The company used cash in both of the first two quarters to build inventory for second-half shipments. If that inventory does not convert into revenue and cash now, the build starts to look like a risk instead of preparation.
The Comtech deal is the transformational piece, and it is expected to more than double Gilat's defense revenue. With closing targeted for around year end and still subject to HSR and CFIUS review, any update on regulatory timing will matter. So will signs that defense demand is broadening on its own, through the US and European orders, the VIPER-KA UAV terminal and any business won from customers unsettled by the Hughes bankruptcy.
Sentiment has soured, with the bearish reading widening to 22.1% from 12.1% before the last report. The stock sits at $7.41, close to its post-earnings low of $7.23 and far below its 200-day average of $13.82, so expectations are clearly depressed. Ultimately, the report comes down to whether Gilat can show that second-quarter margin slippage was temporary while proving it has the deliveries in hand to support a fourth quarter much larger than anything it has produced so far. Deliver both, and the confident tone of last quarter looks earned. Miss either, and the selloff will look like a warning the company failed to heed.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-29 | |
| Oct-15 | |
| Oct-08 | |
| Oct-07 | |
| Oct-05 | |
| Sep-09 | |
| Aug-31 | |
| Aug-17 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-30 | |
| Jul-16 | |
| Jul-15 |
