Nine Energy Service Faces A Coil Tubing And Cost Inflation Test As Losses Widen
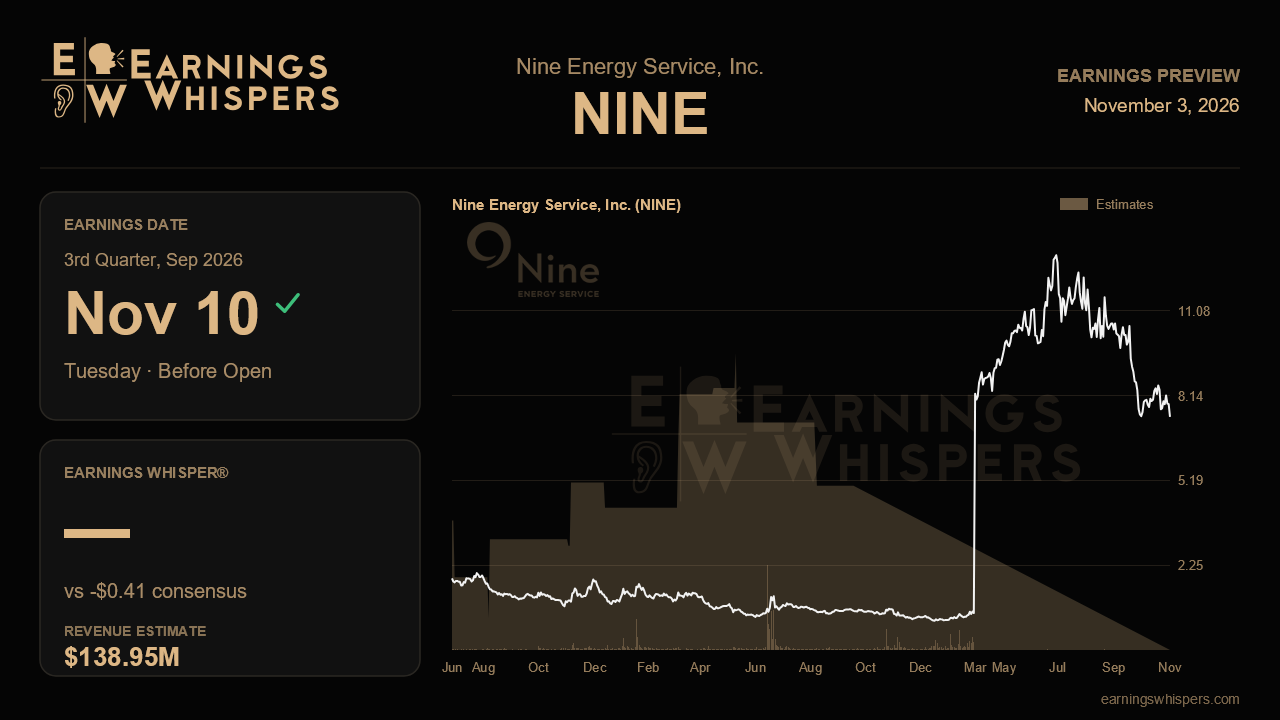
Three months ago, Nine Energy Service offered investors two very different stories in one quarter. Its completion tools business posted a standout period, while its coil tubing operation lost an unusually large share of its deep-reach fleet and cost inflation outran pricing across several service lines. The third-quarter report, due before the open on November 10, will show which of those stories carries more weight. Judging by the stock's slide since then, the market has already decided that the problems matter more.
The Street expects a loss of $0.41 per share on revenue of about $139.0 million. That revenue figure sits just above the $138 million midpoint of management's $133 million to $143 million guidance range, so analysts are not reaching beyond what the company signaled. It would also mark a modest 5.2% gain from the year-ago quarter but a slight step down from the $141.8 million reported in the second quarter. The earnings picture is less forgiving. The expected loss is far wider than the $0.04 per share loss posted last quarter and roughly 17% worse than the year-ago $0.35 loss. In other words, consensus assumes that flat revenue arrives with meaningfully thinner margins, which matches management's warning that rising costs would be repriced only with a lag.
Coil tubing is the first place to look. Two of the company's twelve large-diameter deep-reach units went out of service last quarter, with one possibly sidelined through year-end, and the blended day rate fell about 15% sequentially. Management chose to absorb margin pressure to keep skilled crews intact, betting the outage is temporary. Evidence that the first unit returned on schedule, and that day rates stabilized, would support that view. A second quarter of falling day rates or further downtime would suggest a structural problem rather than bad luck. The same logic applies to cost inflation. Coil costs rose about 12% sequentially, and cementing faced higher materials and labor costs while revenue per job dropped roughly 8%. Management framed inflation as stabilizing by the fourth quarter, so this report should show whether pricing is beginning to catch up or whether the gap is still widening.
Completion tools carries the bullish case. Revenue jumped about 44% sequentially to $37.1 million on strong international dissolvable plug sales and domestic share gains, reversing share losses flagged a year earlier. The key question is whether that surge reflected durable demand from longer laterals or a lumpy order pattern. Holding most of that gain would validate the share-gain narrative; a sharp pullback would remove the main offset to weakness elsewhere. Wireline, where stages fell about 7% last quarter, needs the Haynesville expansion to start contributing visibly, ideally with cement and plug pull-through supported by the gas activity management highlighted. Cash flow also deserves attention after operating cash burn narrowed to $2.3 million, with capital spending now expected toward the lower half of the $20 million to $30 million range.
Sentiment has cooled, slipping to 20.8% bullish from 28.7% ahead of the last report, and the stock has fallen about 23% since then against a roughly 2% decline for the S&P 500. At $7.40, shares sit just below the 200-day moving average and barely above the $7.33 post-earnings low, far from the $12.72 high. That positioning suggests much of the disappointment is priced in, though it also leaves little technical support if the news worsens.
Ultimately, this report hinges on whether management's description of last quarter as temporary holds up. If coil units return, pricing begins closing the inflation gap and tools momentum largely survives, the recovery story bends rather than breaks. If margins slip beyond what the wider consensus loss already assumes, the stalled recovery starts to look like a reversal.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-21 | |
| Oct-15 | |
| Oct-13 | |
| Oct-08 | |
| Oct-01 | |
| Sep-24 | |
| Sep-23 | |
| Aug-29 | |
| Aug-27 | |
| Aug-25 | |
| Aug-12 | |
| Aug-05 | |
| Jul-14 | |
| May-18 |
