Sea Limited's Shopee Profit Pledge Faces Its First Real Test After A 41% Slide
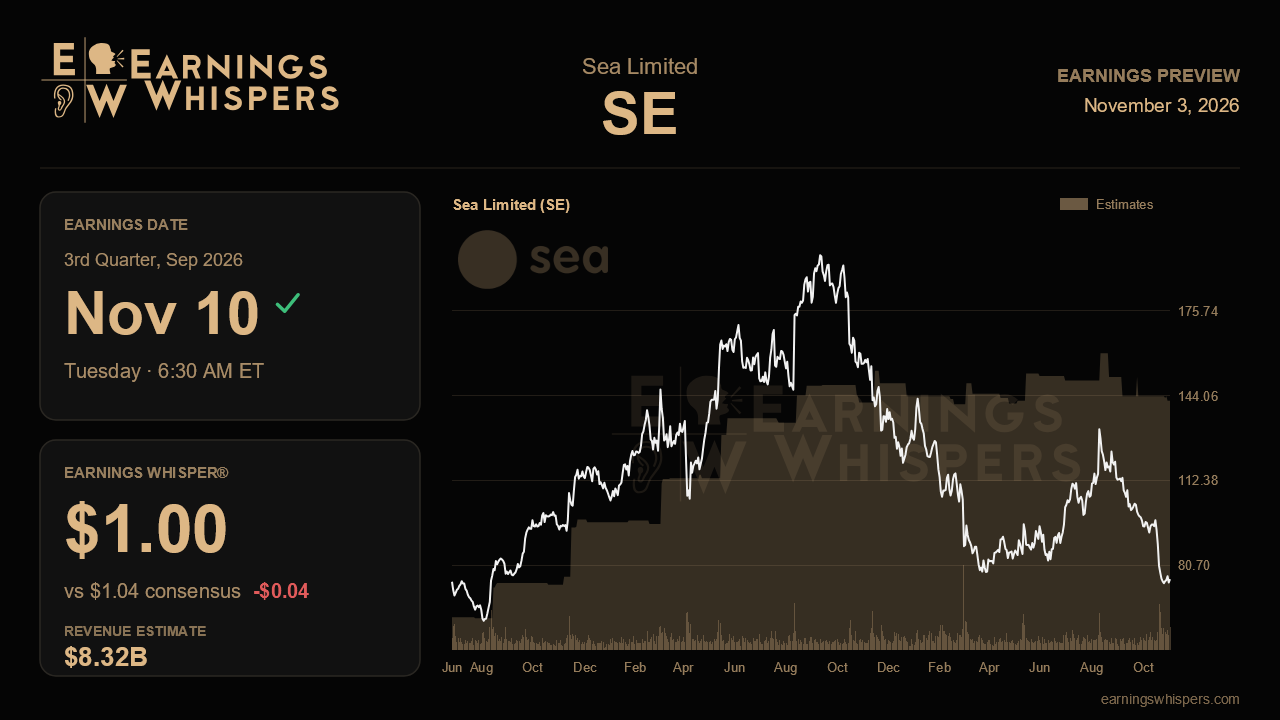
Three months ago, Sea Limited gave investors the most confident message it had delivered in a year, lifting Shopee's full-year adjusted EBITDA target to more than $1 billion and promising that the second half would outearn the first. The market's reply has been brutal. Shares have fallen 41% since that report while the S&P 500 slipped less than 3%, leaving the stock near its post-earnings low. When Sea reports before the open on November 10, the question is whether the operating story still holds or whether the stock's collapse was an early warning that management was too optimistic.
The Street is not setting a low bar. Consensus calls for non-GAAP earnings of $1.04 per share on revenue of $8.32 billion. That revenue figure implies roughly 39% growth from $5.99 billion a year ago, an acceleration for a company of this scale. The earnings estimate is more demanding still. It would more than double last quarter's $0.48 and sit well above the $0.59 earned in the year-ago period. The Earnings Whisper of $1.00 sits slightly below consensus. The gap is small, but it suggests the most engaged investors expect Sea to fall a bit short of the published number rather than clear it.
Shopee is the main event. Its adjusted EBITDA returned to growth last quarter, up 12% to $255 million after a 16% decline in the first quarter. Clearing a $1 billion full-year target requires a meaningfully larger third quarter, so a figure that moves decisively above $255 million would validate the raised guidance. A flat result would leave too much work for the fourth quarter. The levers management highlighted should show up in the details. Advertising revenue grew more than 70% with take rates rising, new buyer growth accelerated to 35%, and the VIP program passed 15 million members, including more than a million in Brazil. GMV growth near the 25% guided pace, holding up against a tougher second-half comparison base, would confirm that monetization gains are not coming at the expense of volume. Management also flagged currency headwinds from weaker local currencies against the dollar. Investors should watch whether dollar-reported results absorb that pressure or whether FX becomes the explanation for a soft quarter.
The Money segment poses a quality-versus-quantity question. The loan book has compounded rapidly to $11.1 billion, up 62%, and nonperforming loans improved to 1.0%. Yet EBITDA growth slowed to 13% as provisions rose on a riskier mix of Brazilian borrowers and off-Shopee SPayLater lending, which now makes up more than a fifth of the portfolio. Continued loan growth with stable credit metrics would support management's claim that new underwriting models lift approvals without adding risk. A jump in NPLs would turn an intentional trade-off into a genuine problem.
Garena is the swing factor on sentiment. Bookings growth has fallen from 51% to 15% over four quarters as exceptional prior-year IP collaborations roll off. Another step down would be expected, but a sharp drop below the mid-teens would reinforce fears that the profit engine funding Shopee's expansion is cooling. The newly announced Palworld and Monster Hunter titles are longer-term stories, so any update on their timing matters more than near-term revenue.
Sentiment has soured, moving from essentially neutral to modestly bearish, and the stock trades about 23% below its 200-day moving average. That combination means a clean report could meet relief, but the elevated earnings estimate leaves little room for tax or investment drag to dent the bottom line again. In the end, the report turns on one issue: whether Shopee's third-quarter profit shows the second-half step-up management promised. If it does, the selloff will look overdone. If not, the raised guidance will start to look like a high-water mark.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-27 | |
| Oct-27 | |
| Oct-20 | |
| Oct-20 | |
| Oct-20 | |
| Oct-02 | |
| Oct-02 | |
| Aug-13 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 |
