Fabrinet's Seventh Straight Acceleration Collides With Thin Margins, Negative Free Cash Flow And A 39% Share Slide
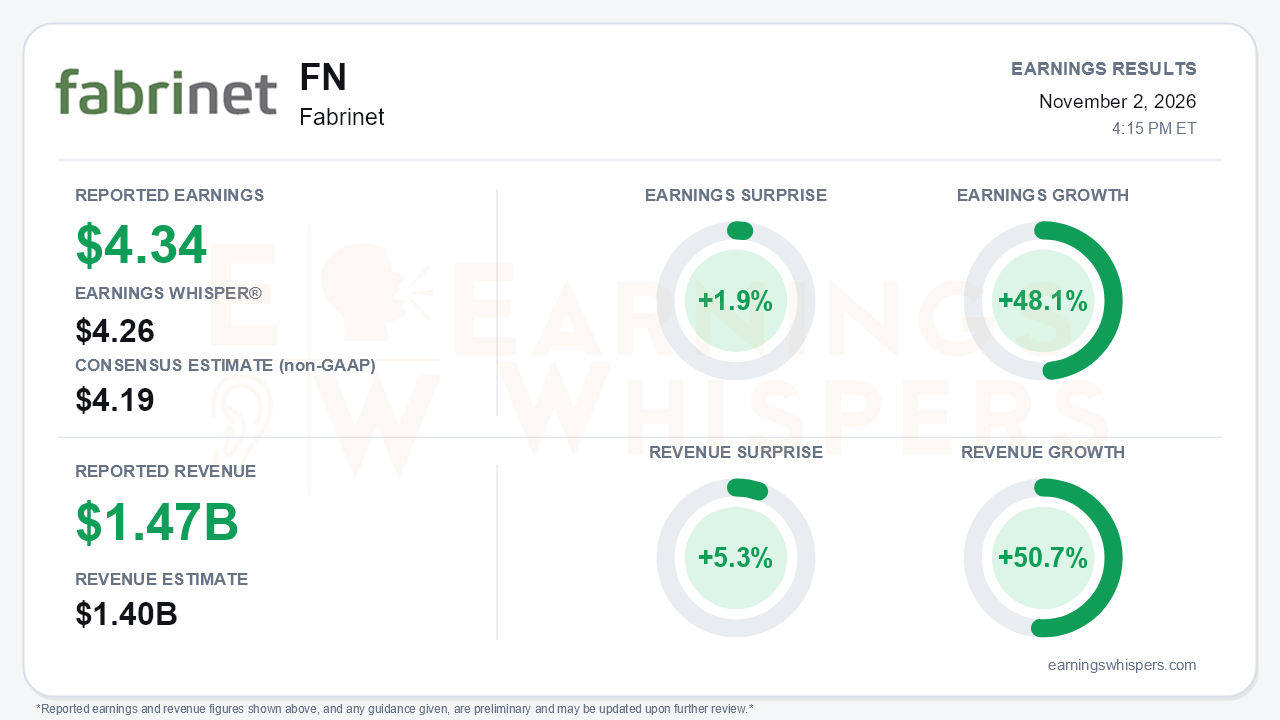
Fabrinet (NYSE: FN) delivered the kind of quarter growth investors usually reward. Fiscal first-quarter non-GAAP earnings of $4.34 per share beat the $4.19 consensus by 1.9% and topped the $4.26 Earnings Whisper number. Revenue of $1.474 billion exceeded the $1.40 billion consensus by 5.3%. Earnings grew 48.1% from a year ago, and revenue rose 50.7%, the company's fastest growth in a decade and the seventh straight quarter of acceleration: from 36% two quarters before the prior one, to 39%, 45% and now 51%. Management guided the December quarter to $1.60–$1.65 billion in revenue, above estimates. The central tension is that the beat was overwhelmingly a volume story. Earnings outpaced consensus by far less than revenue did, margins went nowhere, and the capacity buildout that underpins the growth narrative is now consuming cash at an accelerating rate.
The quality of the beat deserves scrutiny on both the GAAP and cash lines. GAAP EPS rose only to $2.86 from $2.66. That gap is wide because of two non-operating items: a $21.5 million ($0.59 per share) markdown on the non-marketable Raytech investment and a $19.9 million ($0.55) Pillar Two minimum-tax provision. The tax issue is not a one-off. Q2 guidance excludes another $0.60 of Pillar Two charges, putting GAAP EPS guidance at $3.81–$3.96 versus $4.77–$4.92 non-GAAP. Operationally, non-GAAP gross margin of 12.1% slipped from 12.2% in the prior quarter and 12.3% a year ago, which management attributed to merit increases and currency. Non-GAAP operating margin of 10.8% was up 20 basis points year over year but down 10 basis points sequentially. The bigger issue is cash. Operating cash flow collapsed to $21 million as receivables and inventory swelled. With $158.7 million of property and equipment purchases, which the call put at roughly $169 million including the $77 million second Santa Clara campus, free cash flow fell to -$137 million. That compares with -$37 million in Q4 and -$11 million in Q3. Cash and short-term investments dropped to about $757 million from $876 million, and Fabrinet drew roughly $75 million in Thai borrowings.
Beneath the headline, demand broadened rather than narrowed:
- Data center revenue reached $777 million, up 78% year over year and 53% of the mix, versus $669 million and 68% growth in Q4.
- Communications infrastructure re-accelerated to 8% sequential growth from 1%.
- Automotive, industrial and other grew 20% versus 8%.
The new transceiver programs previewed two quarters ago, both hyperscale direct and more than one merchant OEM, are now ramping. Management's tone also escalated. It moved from saying accelerating fiscal 2027 growth was "not beyond the bounds of possibility" to being "as optimistic, if not more so," with demand visible "as far as the eye can see."
The forward catalysts are capacity-driven:
- Revenue capacity is targeted at roughly $10 billion by January, up from $5.8 billion at the fiscal 2026 exit.
- Building 11 at Chonburi breaks ground in January 2027, upsized to about $3 billion of capacity.
- The long-term capacity target rose to roughly $16 billion, from $12.5–$14 billion last quarter and about $11.5 billion the quarter before.
- NPO and CPO programs are expected to contribute late in fiscal 2027, and management described NPO and OCS as potential multi-hundred-million-dollar opportunities.
- The Lumentum-Marvell combination involves two existing customers, which management framed as historically beneficial.
Bears still have legitimate ammunition. The Q2 guide implies about 43% growth at the midpoint, a deceleration from 51%, though Fabrinet has beaten every recent guide. Components remain tight across the board, and capex may rise further as Building 11 and other sites layer in. On the buyback, the release cites an additional $103 million bringing aggregate authorization to $637.3 million. The call described a roughly $110 million expansion to about $200 million remaining. The figures likely reflect cumulative versus remaining authorization, but they do not reconcile cleanly.
The market setup is more complicated than the surprise implies. Shares opened at $513.70 after the August report and now sit at $314.70, down 38.7% and roughly 40% below the $523.44 200-day moving average. That decline came even as growth accelerated. Earnings Whispers investor sentiment remained slightly positive but weakened meaningfully, falling from 0.19 to 0.05. The price and AVWAP trend readings are negative, while sequential growth remains positive. This is a stock the market has de-rated while fundamentals improved, which suggests concern about margins, cash burn, customer concentration or the durability of AI-related optical spending rather than near-term demand.
The bottom line is that Fabrinet's growth engine is running harder than ever, with accelerating revenue, broadening segments and a sharply larger capacity roadmap. But the earnings leverage is modest, margins are flat to slightly down, and free cash flow has turned decisively negative to fund the expansion. With shares deeply below their 200-day average and sentiment cooling, the next leg depends less on beating guidance than on showing that the $16 billion capacity bet converts into margin stability and cash generation.
Read our earnings preview for Fabrinet: https://www.earningswhispers.com/article/FN/21393
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 5 hours | |
| 6 hours | |
| 7 hours | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-26 | |
| Oct-19 | |
| Oct-12 | |
| Sep-09 | |
| Aug-26 | |
| Aug-20 | |
| Aug-18 |
