Apple Clears Consensus But Falls Short Of The Whisper As Margin Guidance Slides Again
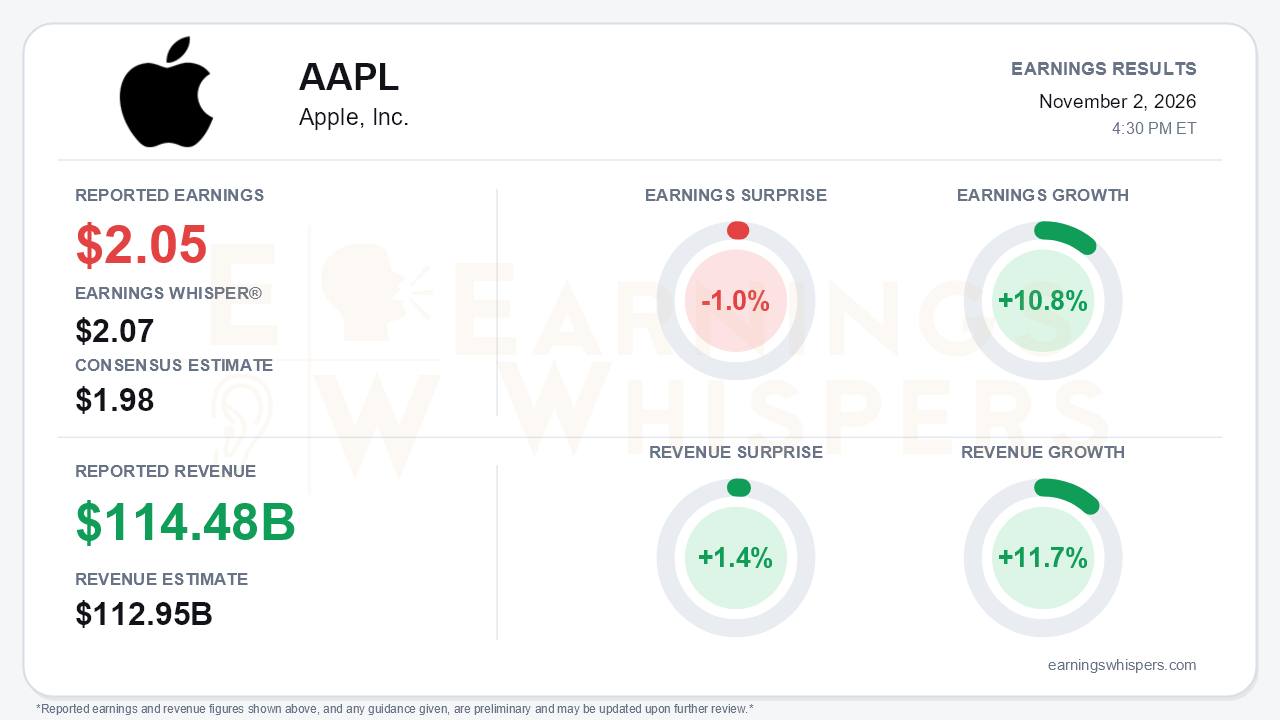
Apple (NASDAQ: AAPL) closed a record fiscal year with a quarter that looked stronger on the surface than underneath. Earnings Whispers-normalized EPS of $2.05 beat the $1.98 consensus but fell 1.0% short of the $2.07 Earnings Whisper number. Revenue of $114.48 billion was a September-quarter record, 1.4% above consensus and ahead of the 9-11% growth management had guided on the prior call. Earnings grew 10.8% and revenue rose 11.7%, both slower than the full year, when revenue climbed 15% to $478.8 billion and EPS rose 20%. That is the central tension. Apple is still growing at a double-digit pace and guiding to the biggest revenue quarter in its history, but each successive outlook has been a little less generous, and the margin guide has now moved decisively lower.
The quality of the beat deserves scrutiny. Reported diluted EPS was $2.10, up 14%, but it included a $0.05 benefit from tariff refunds. Gross margin of 47.9% also carried roughly a one-point lift from those refunds, and management said the vast majority of the refunds have now been received. Excluding them, gross margin was closer to 46.9%. Below the gross line, research and development spending jumped to $11.7 billion from $8.9 billion a year ago, a 32% increase. That pushed total operating expenses up about 21% and held operating income growth to roughly 10%. Share count reduction helped, with diluted shares down about 1.6% year over year. The balance sheet showed another change: inventories jumped to $14.5 billion from $5.7 billion, and manufacturing purchase obligations rose $33 billion sequentially, consistent with Apple stocking memory ahead of rising prices.
The segment mix showed a clear divergence.
- **iPhone** revenue rose 17% to $57.6 billion, a September-quarter record but a step down from the 22-23% growth of the first three quarters.
- **Mac** was the standout, up 24% to $10.8 billion on MacBook Neo and MacBook Pro demand.
- **Greater China** grew 21%, capping a 28% year.
- **iPad** fell 10% and **Wearables** fell 8%.
- **Services** reached an all-time high of $31.6 billion with gross margin edging up to 76.0%, but growth has decelerated from 16% in Q2 to 12% in Q3 and roughly 10% this quarter. Management guided to 8-9% next quarter, citing currency, third-party licensing, mobile-gaming softness and App Store regulatory and court rulings.
The forward guide is where bears have legitimate ammunition. December-quarter revenue growth of 7-10% is still enough to deliver a record quarter, which explains the above-consensus revenue framing. But the guide continues a steady slide from 13-16% in Q1, 14-17% in Q2 and 9-11% in Q3. The gross margin guide of 45-46% compares with 48-49% at the start of the year. Management called memory costs "unprecedented" and said they are still rising beyond December, while the benefit of lower-cost carry-in inventory fades. Siri AI inference costs will flow through services cost of sales, and hardware revenue deferrals add further pressure. Price increases on Mac, iPad and now iPhone may offset some of the cost inflation, but management said elasticity is not yet known.
The catalyst slate is the bull rebuttal, and it is substantial. The iPhone Duo foldable launched supply-constrained, with no visibility yet on when supply will match demand. Siri AI is in beta across six languages, with paid iCloud+ tiers planned for expanded server-side AI access. Apple also introduced touch-enabled MacBook Pros, new home hardware and its largest-ever Mac education deal, 170,000 MacBook Neos for the Philippines. Advanced-node chip constraints are easing with the move to 2nm. Memory, however, will constrain Mac and iPad shipments in the December quarter. This was also the first call under CEO John Ternus.
Investors did not enter the report with much enthusiasm. Earnings Whispers sentiment slipped from -0.06 to -0.17, a meaningful but not dramatic move deeper into negative territory. Price action tells a more constructive story. Shares have gained 11.0% since the open after the July report and sit about 14% above the 200-day moving average. Price and AVWAP trend readings are positive, while sequential growth and momentum are neutral. The stock has rallied even as investors grew more cautious, which leaves less cushion for a quarter that missed the whisper and lowered the margin outlook.
The bottom line is that Apple delivered a record quarter with a lower-quality beat: tariff refunds flattered both EPS and margins, and normalized earnings fell short of the whisper. A potentially powerful product cycle led by the iPhone Duo and Siri AI is real, but it is running into memory inflation, AI cost absorption and decelerating Services growth. For a stock trading well above its long-term average, the December-quarter margin trajectory matters more than the revenue record.
Read our earnings preview for Apple, Inc.: https://www.earningswhispers.com/article/AAPL/21359
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 30 min | |
| 30 min | |
| 50 min | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 1 hour | |
| 2 hours | |
| 2 hours | |
| 2 hours | |
| 2 hours |
