Wix Must Prove Base1 Margin Gains Can Offset A Fading Partners Business
Wix heads into its third-quarter report with two stories pulling in opposite directions. On one side is Base44, the AI app-building business whose economics were transformed in June by Base1, the company's first in-house language model. On the other is a partners business that management now concedes is losing activity to Base44 and to competitors, part of the reason full-year revenue and bookings outlooks were trimmed last quarter. The report due before the open on November 10 should show which story deserves more weight.
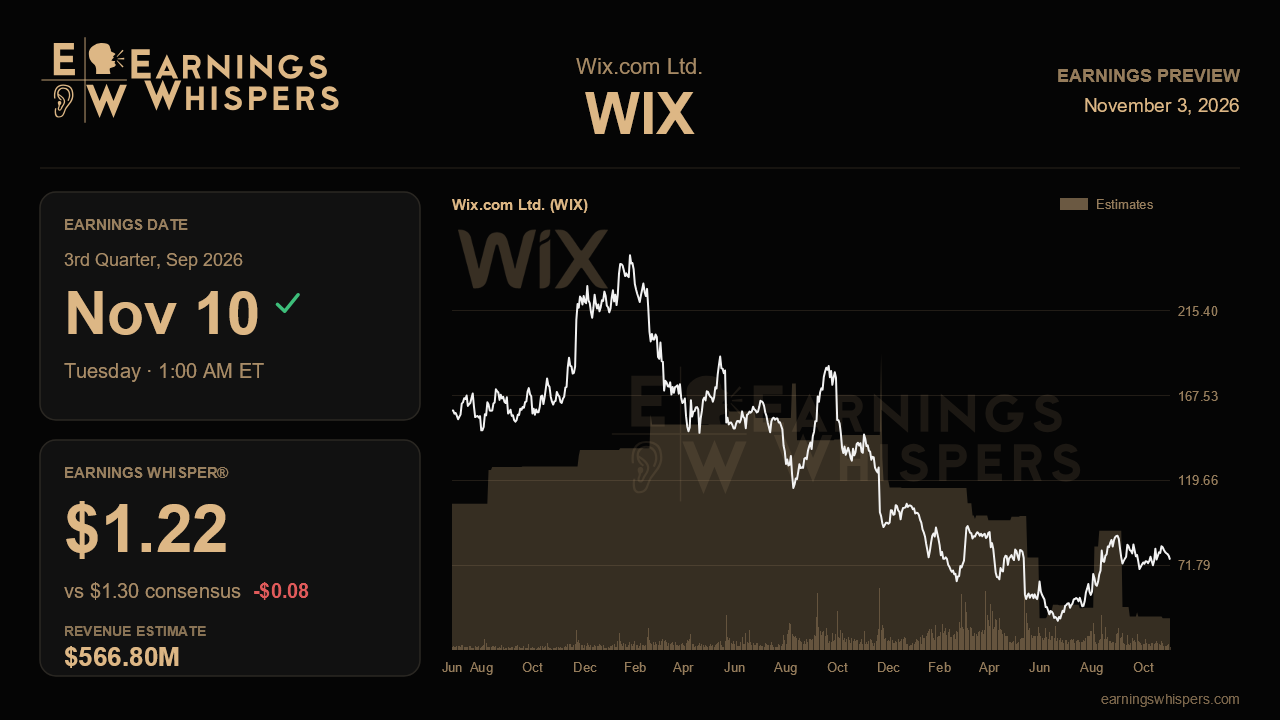
The Street expects non-GAAP earnings of $1.30 per share on revenue of $566.8 million, a 12.2% increase from a year earlier. That is solid but clearly slower than the mid-teens pace Wix delivered in the second quarter, and it matches management's guidance for only low double-digit growth this quarter. The company has reaffirmed its target of roughly $568.3 million, so consensus sits essentially on top of guidance. The more interesting gap is annual: management still expects about $2.29 billion in 2026 revenue, while analysts are at $2.25 billion. That suggests the Street remains skeptical of the full-year plan, which gives Wix room to impress simply by holding its number. The Earnings Whisper of $1.22, below consensus, points to a somewhat lower informal bar on profit, a reasonable stance given that management said every dollar of gross-margin savings would be pushed back into sales and marketing during the second half.
That reinvestment is central to judging the quarter. Base44's non-GAAP gross margin was close to zero entering the year, and management guided to roughly 60% in the second half thanks to Base1, adding about two points to consolidated gross margin versus the first half. Consolidated gross margin already edged up to 67% last quarter. A clear step higher this time would validate the Base1 claims, including the assertion that the model beats frontier models on Base44 tasks at a fraction of the cost. A flat margin would raise doubts. Investors should also look for updated Base44 ARR, which climbed from $59 million at the end of 2025 to $150 million by mid-May, with management describing a similar trajectory since. Because the company raised its marketing return threshold to chase share, faster ARR growth is the payoff that justifies heavier spending.
The risks flagged last quarter are just as testable. Bookings growth was cut to the low teens and now trails revenue by a few points, a leading indicator that future revenue could slow further. Any sign that the gap is widening would challenge the 2026 guide. Gross payment volume growth slumped to 3% in the second quarter, partly because of the InkFrog wind-down, so evidence of stabilization in commerce and in partner activity matters. Free cash flow margin has already been reset to the high teens from 30% in 2025, which leaves little tolerance for further slippage. Early Base44 annual cohorts are also nearing renewal, and any color on retention would be valuable.
The market has leaned toward the optimistic reading. Shares have gained about 33% since the last report while the S&P 500 slipped, and sentiment, though still bearish, has improved from roughly 44% bearish to 34% bearish. Yet the stock, near $75, sits well below its post-earnings peak of $96.80 and only modestly above its 200-day average of $70.58, signaling that enthusiasm has already cooled from its high.
Ultimately, the quarter turns on whether Base44's improved margins and rising ARR are growing fast enough to outrun the erosion in partners and bookings. If gross margin expands as promised and bookings stop deteriorating, the full-year target looks credible. If not, the June reset may not prove to be the last.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 50 min | |
| Nov-02 | |
| Oct-25 | |
| Oct-22 | |
| Oct-22 | |
| Oct-15 | |
| Oct-14 | |
| Sep-24 | |
| Sep-16 | |
| Sep-02 | |
| Aug-25 | |
| Aug-24 | |
| Aug-13 | |
| Aug-12 | |
| Aug-11 |
