B&G Foods Faces New CEO's Debut With Street Doubting Its Reaffirmed Outlook
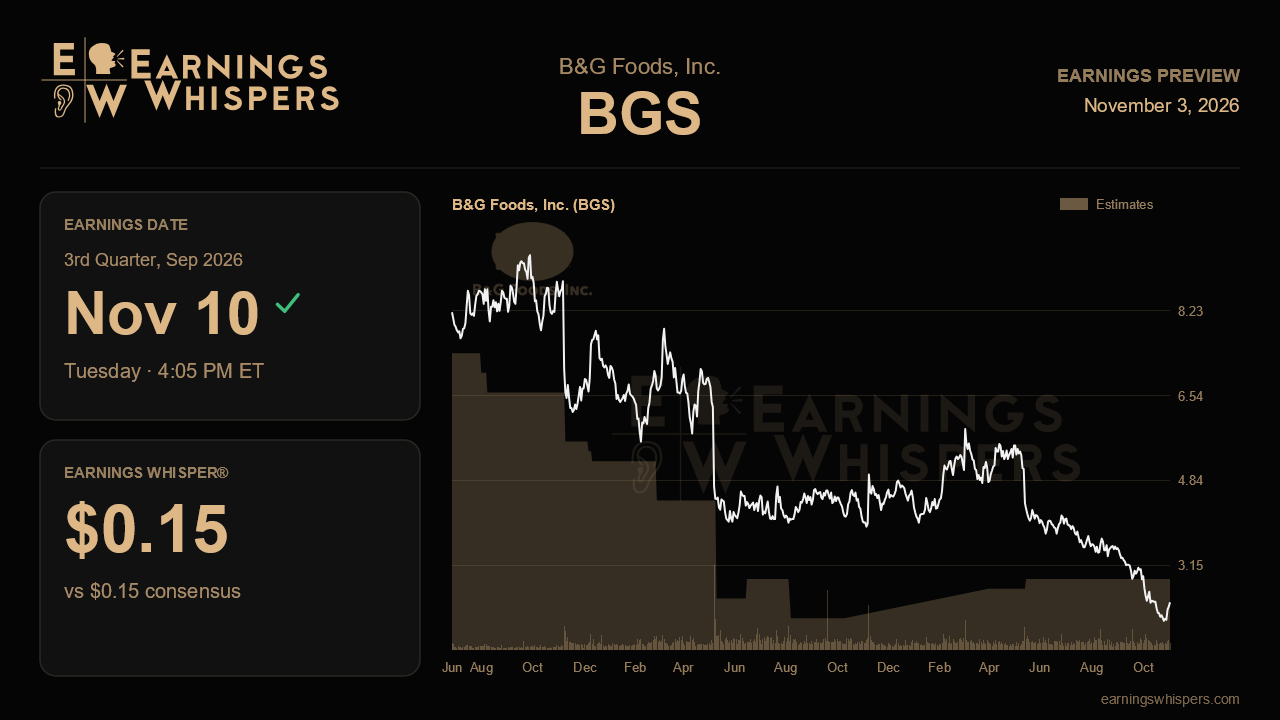
B&G Foods heads into its third-quarter report with a peculiar split screen. Management has spent the year arguing that pruning low-margin brands and buying higher-margin ones would leave a smaller but healthier company, and the second quarter offered real evidence on margins. Yet the stock has lost roughly 30% since that report, and Wall Street now sits just below the low end of the company's own full-year earnings range. When the results arrive after the close on November 10, new chief executive Rob Mills will make his first appearance on the call, and he will be doing it with a share price that already reflects deep skepticism.
The quarterly bar itself is modest. Analysts expect earnings of $0.15 per share, identical to the year-ago figure, and the Earnings Whisper matches consensus, so there is no hidden optimism baked into the number. Flat earnings on a revenue base shrunk by divestitures would actually be consistent with the strategy, since a year ago the company generated $439.3 million in sales and the second quarter came in at just $383.3 million. The more telling comparison is annual. B&G reaffirmed 2026 guidance for earnings of $0.58 to $0.68 per share on revenue of $1.735 billion to $1.775 billion, while the Street is at $0.57 and $1.74 billion. In other words, analysts are positioned at or below the bottom of both ranges, signaling doubt that the back half can deliver what management promised.
That doubt has a clear source. Base business net sales fell 2.9% in the second quarter after a positive first quarter, returning to the pattern of declines seen in late 2025. Management attributed $5 million to $7 million of the shortfall to July 4th shipping-day timing, which means some of that volume should theoretically land in the third quarter. If base sales stabilize or turn modestly positive, the timing explanation gains credibility. Another negative print would suggest the weakness in tracked retail channels is structural and that growth is leaning too heavily on non-measured channels.
Margins are the part of the story most worth defending. Adjusted EBITDA reached 15.8% of sales in the second quarter versus 13.7% a year earlier, helped by exiting Green Giant U.S. Frozen, adding College Inn and Kitchen Basics, and tariff refunds. Spices and Flavor Solutions profit jumped 29%. The challenge is that management itself flagged soybean oil and freight inflation as back-half headwinds, and the Specialty segment was already absorbing Crisco pricing investments. Holding margins near the second-quarter level, with full-year adjusted EBITDA still tracking toward the $275 million to $290 million target, would validate the repositioning. A meaningful slip would raise the question of how much of the improvement was one-time tariff relief.
Below the operating line, the 11% notes due 2031 have pushed expected full-year interest expense to $157.5 million to $162.5 million, which eats into whatever operating gains materialize. With the dividend already halved and expected Green Giant Canada proceeds lowered to about $32 million from a prior $60 million placeholder, deleveraging progress and cash generation deserve as much attention as the headline EPS figure.
Sentiment has drifted from mildly bullish before the last report to mildly bearish now, and the shares at $2.41 sit far below the 200-day moving average of $4.09, though above the post-earnings low of $1.99. That leaves room for relief if the quarter is clean, but it also reflects a market that is no longer giving the benefit of the doubt. The central issue is whether B&G can show that higher margins survive commodity inflation while the base business stops shrinking. If Mills reaffirms guidance with evidence on both fronts, the gap between the Street and management may begin to close. If not, the low end of the range likely becomes the new ceiling.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Oct-28 | |
| Oct-27 | |
| Oct-14 | |
| Oct-14 | |
| Oct-13 | |
| Oct-12 | |
| Oct-07 | |
| Oct-06 | |
| Aug-28 | |
| Aug-20 | |
| Aug-20 | |
| Aug-19 | |
| Aug-12 | |
| Aug-12 |
