Chemours Matches The Whisper As TiO2 Pricing And AI Demand Improve, But A Third Straight Guidance Cut Keeps Pressure On The Stock
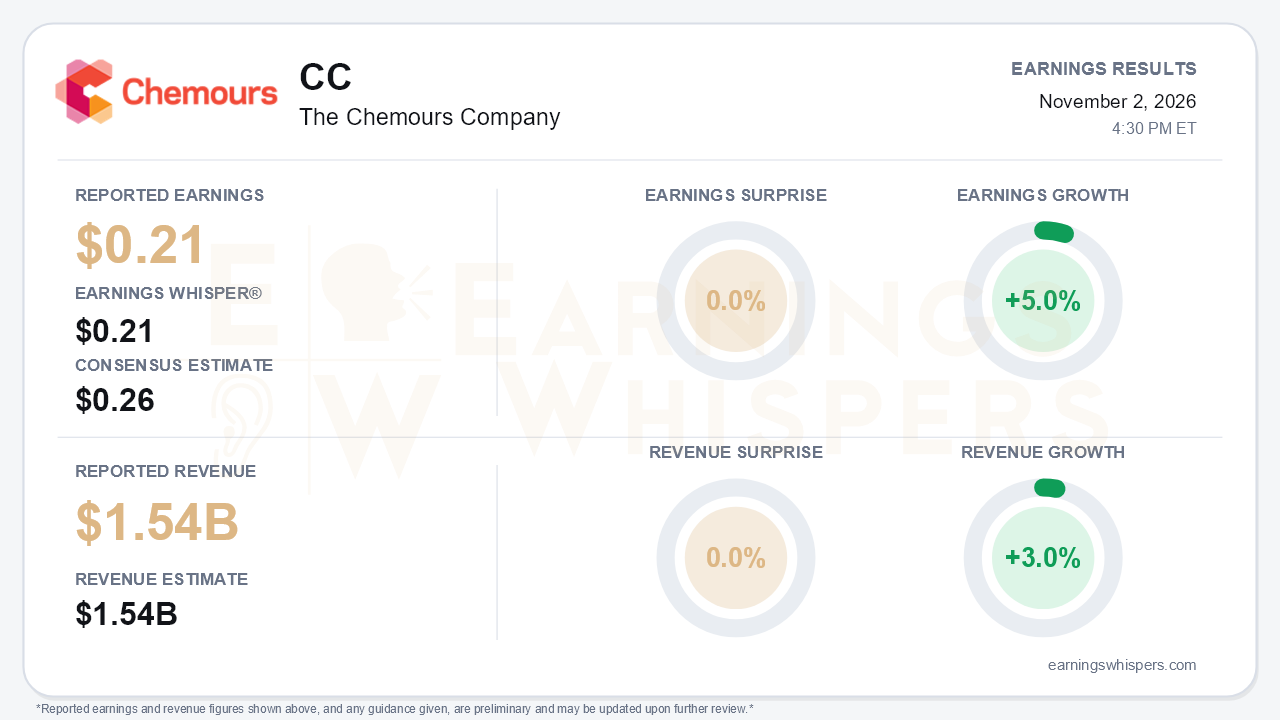
Chemours (NYSE: CC) delivered a quarter that met the market's real bar but not the published one. Adjusted earnings of $0.21 per share matched the Earnings Whisper number exactly and came in below the $0.26 consensus. Earnings Whispers treats that as an in-line result, with a 0.0% surprise. Revenue of $1.54 billion matched consensus, rising 3.0% year over year, while earnings grew 5.0%. Underneath that steady headline, the business is splitting. Titanium Technologies pricing and AI-linked specialty demand both strengthened. Thermal & Specialized Solutions weakened, and management trimmed full-year targets for the third consecutive call. That is the central tension.
The GAAP numbers need careful reading. Net income of $196 million, or $1.29 per share, swung from a $274 million loss in the second quarter. Most of that swing came from items outside the operating business:
- a $150 million PFAS insurance receipt booked as a reduction to SG&A, which turned SG&A negative for the quarter;
- a $50 million gain on the final Kuan Yin land sale;
- $138 million of net litigation-related income in the reconciliation.
The operating trend is better captured by the sequential decline. Adjusted EPS halved from $0.42 in the second quarter, and adjusted EBITDA fell 19% sequentially to $200 million. That EBITDA figure still landed near the top of the $175-205 million range management had guided, so the quarter itself was executed largely as planned.
The segment mix is where the story changed:
- **TSS weakened sharply.** Sales fell 9% and adjusted EBITDA dropped 30% to $136 million. Margin compressed eight points to 27%, as Opteon refrigerant sales fell 22% against last year's AIM Act channel fill. Management now does not expect visibility on the stationary aftermarket until late in the first quarter of 2027. That is a clear retreat from the earlier framing of restocking ahead of next season.
- **TT improved sharply.** EBITDA more than tripled to $85 million on 10% year-over-year pricing, up from the roughly 5% year-to-date gain cited last quarter. However, the call described volumes as weaker across key regions, reversing the second-quarter expectation of year-over-year volume growth in the back half.
- **APM showed the most growth.** Performance Solutions grew 26%, versus 8% in the second quarter. AI, data center and semiconductor applications now represent about 10% of combined TSS and APM sales.
The forward-looking ledger is mixed but tilts negative near term. On the positive side:
- APM's fourth-quarter EBITDA guide of $40-45 million sits above its normalized range, partly because of contractual timing.
- Chemours formally launched its two-phase and immersion liquid-cooling portfolio. The release brands it Faizeon while the call materials refer to Phaseon, a discrepancy investors should note.
- Management said it expects company earnings growth in 2027.
- The North Carolina PFAS settlement and final New Jersey consent order reduce legacy-liability uncertainty.
The cuts, however, were broad:
- Full-year adjusted EBITDA narrowed to $775-800 million, from $775-825 million last quarter and $800-900 million at the start of the year.
- Sales growth is now about 2%.
- Free-cash-flow conversion fell to 15-20% from above 25%.
- Capex was cut partly by deferring strategic projects.
- The leverage target slipped to below 4.2x, versus roughly 3.8x previously.
With net leverage at 4.3x and stockholders' equity of just $155 million, bears have legitimate ammunition on the balance sheet. The guidance implies fourth-quarter EBITDA of $160-185 million and a sequential sales decline of 5-10%. Earnings Whispers notes that this revenue outlook sits below estimates.
Investors appear to have anticipated much of this. Sentiment moved from roughly neutral at 0.06 after the August report to a clearly negative -0.41, a meaningful deterioration. Shares have fallen 17.8% since the post-report open of $16.01 to $13.16, and they sit 28.4% below the 200-day moving average of $18.37. The Earnings Whispers trend signals are largely negative, with price, momentum and AVWAP all pointing lower and sequential growth neutral.
That backdrop cuts both ways. A whisper-matching quarter suggests expectations had already reset lower, which limits the damage from another trim. But the repeated pattern of lowering targets has eroded management's credibility on timelines, particularly for TSS recovery and deleveraging. TiO2 pricing could help, with an Indian anti-dumping duty reinstated and Chinese producers raising prices. Rising Chinese imports into the U.S. and a softening housing market argue for caution.
The bottom line is that Chemours is improving in the places that carry long-term upside, TiO2 pricing and AI-linked specialty materials, while its most profitable segment and its balance-sheet targets keep slipping. The quarter met lowered expectations, but a third straight guidance cut and leverage still above 4x leave the stock dependent on a 2027 earnings recovery that management has promised but not yet shown in the numbers.
Read our earnings preview for The Chemours Company: https://www.earningswhispers.com/article/CC/21375
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-03 | |
| Nov-02 | |
| Nov-02 | |
| Nov-02 | |
| Oct-29 | |
| Oct-29 | |
| Oct-27 | |
| Oct-26 | |
| Oct-26 | |
| Oct-21 | |
| Oct-21 | |
| Oct-20 | |
| Oct-19 | |
| Oct-16 | |
| Oct-14 |
