Astronics Must Prove Record Margins Can Last After A 29% Post-Raise Slide
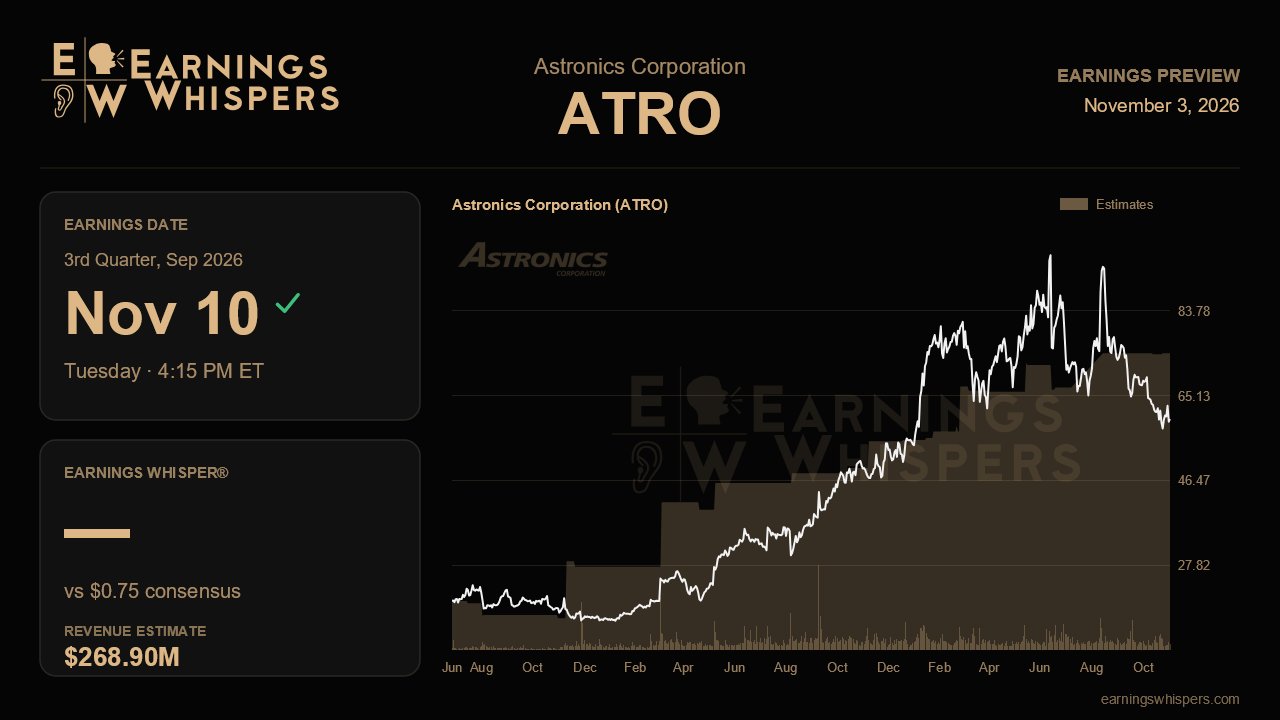
Astronics heads into its third-quarter report with one of the stranger setups in aerospace. Last quarter the company posted records in revenue, bookings, backlog and margins, raised full-year guidance for the third time, and finally landed the Army radio-test production order it had been promising for most of a year. The stock has since fallen nearly 29%, trailing the S&P 500 by about 26 percentage points. When a company does almost everything right and the market still sells, the next report becomes less about beating a number and more about convincing skeptics that the good news is durable.
The Street is looking for earnings of $0.75 per share on revenue of $268.9 million when results arrive after the close on November 10. That would mean roughly 27% revenue growth and 53% earnings growth from a year ago, a pace that says operating leverage, not just volume, is doing the heavy lifting. The revenue estimate sits almost exactly at the midpoint of management's $265 million to $275 million third-quarter guide. Notably, consensus was closer to $250 million when that guidance was issued, so analysts have already marked their models up to management's view. A result near $270 million would simply confirm the plan. Real upside would require pushing toward the top of the range or beyond, and full-year guidance of $1.02 billion to $1.04 billion leaves room for a fourth consecutive raise only if the fourth quarter looks as strong as the third.
Margins are the heart of the debate. Adjusted EBITDA margin jumped to 19.8% in the second quarter from 16.4% in the first, which management attributed to volume leverage, contract repricing that is now largely complete, lower employee turnover and site consolidation. Those are mostly structural drivers, and holding something close to that level would validate the idea that Astronics has reset its earnings power. But a few pieces of the second quarter will not repeat cleanly. A one-time tariff refund of about $2 million helped, while the underlying tariff drag runs at $3 million to $4 million a quarter. The test segment's ramp on the Army 4549T award also brings roughly $4.1 million of near-term raw-material revenue carrying no margin. Some sequential margin slippage would be understandable; a sharp retreat toward first-quarter levels would undercut the narrative.
Demand is the other test. Bookings have climbed in a steady staircase to a record $306 million, lifting backlog to roughly $780 million. Orders do not need to set another record, but a book-to-bill comfortably above one would show the ramp is broad rather than a pull-forward. Within that picture, two newer soft spots deserve attention. Management flagged that its roughly $60 million geostationary connectivity business is struggling during the shift to low-earth-orbit systems, arguing LEO demand should more than offset it. Any sign of that offset arriving, or not, will matter. The MV-75 program, described as the largest military effort in company history with about $35 million of expected revenue this year, also carries exposure to federal funding after September 30, a question the company should address directly.
Sentiment has cooled to 31.4% bullish from 38.1% heading into the last report, and the stock at $59.95 sits well below its 200-day moving average of $74.04 and only about 7% above its post-earnings low of $56.20. Expectations, in other words, look more guarded than the operating trend would suggest. Possible tax valuation allowance releases could also distort reported earnings, so the quality of the beat will matter more than its size.
Ultimately, this quarter comes down to whether the second-quarter margin leap was a new baseline or a high-water mark. If Astronics delivers revenue near the top of its range, keeps EBITDA margins in the high teens despite tariffs and zero-margin test revenue, and shows bookings still outpacing shipments, the recent selloff will look disconnected from fundamentals. If margins fade meaningfully, the market's doubts will appear justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| Oct-28 | |
| Sep-08 | |
| Aug-31 | |
| Aug-12 |
Stock Of The Day: Boeing, Airbus Supplier Soars 15% On Earnings, Flashing Buy Signals
ATRO +17.33%
Investor's Business Daily
|
| Aug-12 |
SpaceX Supplier Sinks On Earnings; Aerospace Parts Vendor Soars
ATRO +17.33%
Investor's Business Daily
|
| Aug-12 | |
| Aug-11 | |
| Jul-28 | |
| Jul-27 | |
| Jun-29 | |
| Jun-01 | |
| May-27 | |
| May-13 | |
| May-12 |
