Amprius Must Prove Its Second-Half Ramp As Stock Lags Its Raised $140 Million Outlook
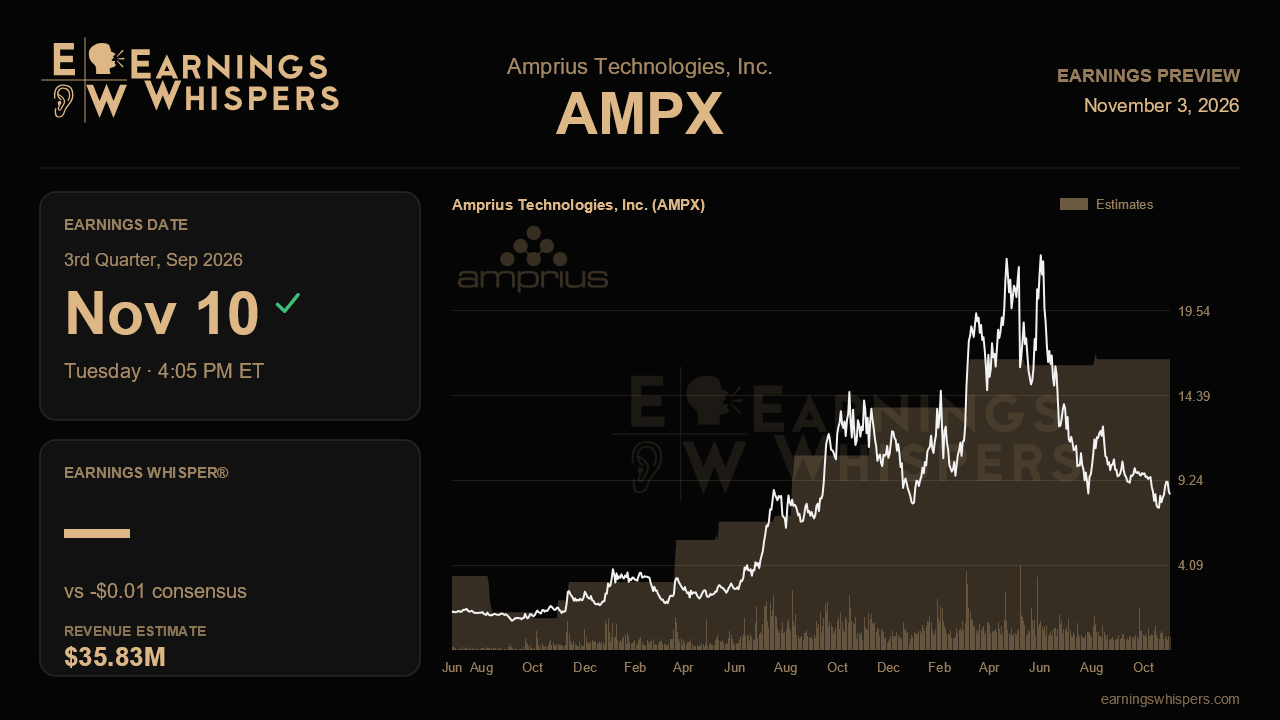
Amprius Technologies heads into its third-quarter report with a striking disconnect. Management has raised its full-year revenue outlook twice and lifted its margin target, yet the shares have fallen more than 32% since the last report, trailing the S&P 500 by roughly 29 percentage points. When the battery maker reports after the close on November 10, the question is less whether the business is growing and more whether the steep second-half ramp built into guidance is actually showing up in shipments.
Wall Street expects a loss of a penny per share on revenue of about $35.8 million. That would be a 67% jump from the $21.4 million posted a year ago and a meaningful narrowing from the 3-cent loss in the same quarter last year. On a sequential basis, though, the bar is modest. Consensus implies only about 5% growth over the second quarter's $34.0 million, a clear slowdown from the 19% sequential gain that produced the company's sixth straight revenue record. The arithmetic of guidance is more demanding. Amprius now targets at least $140 million for 2026, and with roughly $62.5 million booked in the first half, it needs about $77.5 million from the final two quarters, or close to $39 million per quarter on average. The full-year consensus of about $133 million sits well below management's floor, which suggests analysts either have not fully caught up or doubt the company can deliver. A third-quarter figure near $38 million or better would go a long way toward closing that credibility gap.
Margins are the second test. Gross margin climbed from 15% a year ago to 27% in the second quarter, and management raised its full-year target to at least 28%, citing a favorable mix of European and pouch-cell business and tighter control of contract manufacturing costs. Because the first half averaged below that level, hitting the annual goal likely requires second-half margins around 31%. That is a stretch when management itself warned that margins could step back in a given quarter as it builds out a higher-cost U.S. supply chain for defense compliance. A margin print at or above the second quarter's level would validate the mix story; a dip into the low 20s would raise doubts about both the margin guide and the reaffirmed target for more than $4 million in adjusted EBITDA.
The catalyst list from the last call deserves follow-up. The $24 million order from a new European drone customer was slated to ship over about three quarters, so it should begin contributing now. Updates on the Drone Dominance Program, where roughly half of the invited drone makers use Amprius cells ahead of a planned 60,000-drone order, and on Redwire's Marine Corps purchase order would help gauge how quickly defense demand converts to revenue. Investors should also check receivables, which swelled to $40.7 million on back-end-loaded shipments. Healthy collections alongside a cash balance near or above the prior $74.5 million would ease concerns about the quality of growth, while further receivable buildup would invite questions.
Sentiment has warmed, swinging from notably bearish before the last report to modestly bullish now, but the stock tells a harsher story. At $8.38, shares sit far below the 200-day moving average near $13.38 and toward the bottom of their post-earnings range of $7.26 to $13.42, a range that itself fell entirely beneath the prior quarter's trading band. The market is clearly pricing in execution risk and uncertainty around an unauthorized defense budget that carries a six-to-nine-month revenue lag.
Ultimately, this report hinges on whether Amprius shows a credible path to its $140 million floor with margins moving toward 30%. Clear evidence of that ramp could force a reset of skeptical Street models. Anything that looks like a stall would suggest the guidance raises got ahead of the business.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Oct-21 | |
| Oct-05 | |
| Sep-28 | |
| Sep-28 | |
| Sep-28 | |
| Sep-02 | |
| Sep-01 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-30 | |
| Jul-15 | |
| Jul-14 |
