Clearfield's Reset Quarter Puts Broadband Weakness And A $22 Million Data Center Order On Trial
Clearfield heads into its fiscal fourth-quarter report having already delivered the bad news. Three months ago, management abandoned a full-year revenue target it had reaffirmed for three straight quarters, cutting it to $151 million to $155 million from $160 million to $170 million and slashing the earnings outlook by roughly two-thirds. The same call unveiled the company's first hyperscale data center order, worth about $22 million. That leaves the upcoming report, due after the close on November 10, with an unusual job: proving the cut was a clean reset rather than the first step down, while showing that the data center pivot can carry the story into fiscal 2027.
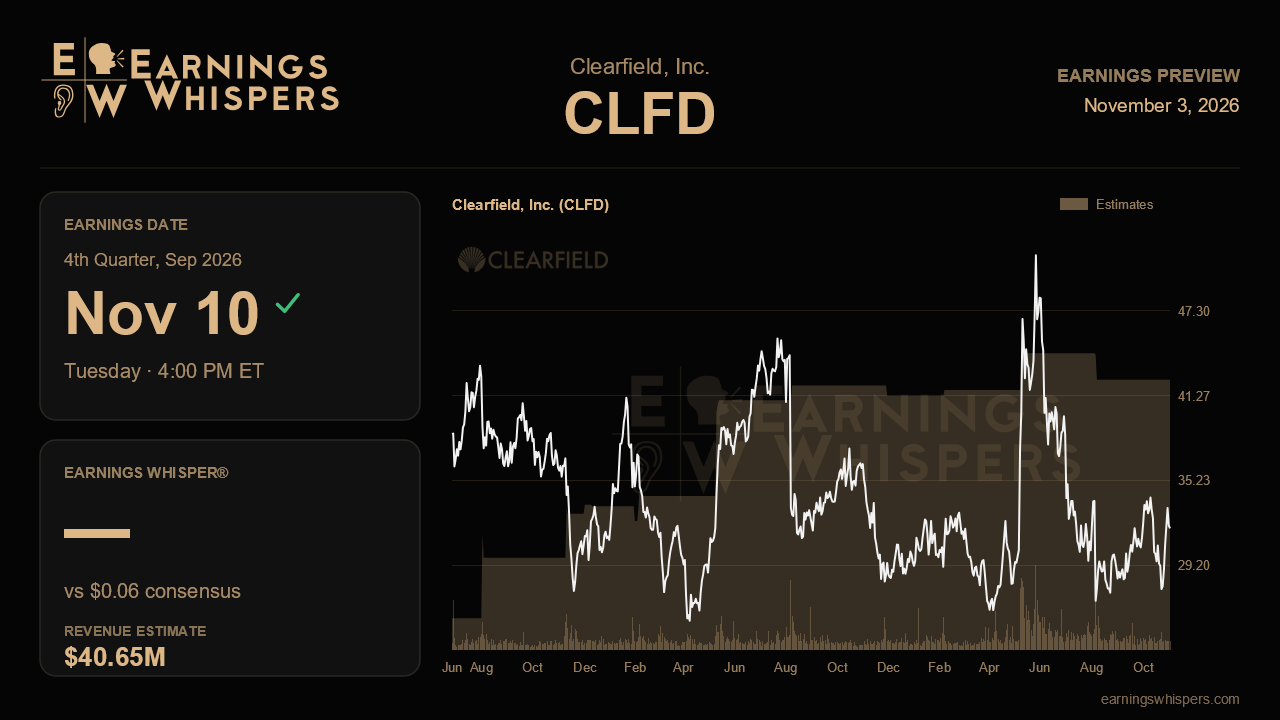
The Street has fully absorbed the guidance. Consensus calls for earnings of $0.06 a share on revenue of $40.7 million, against management's range of breakeven to $0.07 on sales of $38 million to $42 million. Revenue expectations sit modestly above the midpoint, but the earnings estimate is crowded toward the top of the range, which suggests analysts are counting on gross margin stabilizing rather than slipping again. The comparison is unflattering on its face: revenue would be roughly flat versus last year's $41.1 million, while earnings would fall about 54% from $0.13. Sequentially, the quarter is a step back from the $43.9 million and $0.22 delivered in the third quarter.
Margins are the swing factor. Gross margin has eroded every quarter for a year, from 34.6% to 31.8%, though the latest figure included about 1.8 points of one-time drag tied to a $2.6 million write-off of custom inventory after the company's largest community broadband customer walked away from its backlog. Stripping that out, underlying margin looked closer to stable. A fourth-quarter print back in the 33% range would support the view that the write-off was an isolated event. Another slide on lower volume would point to pricing pressure or poor absorption, and would make the $0.06 estimate look ambitious. Operating expenses, which fell 14% sequentially to $11.4 million last quarter, need to stay disciplined for the earnings math to work.
The broadband commentary matters just as much as the numbers. Management blamed the cut on spring quoting activity that never turned into summer bookings, on BEAD funding delays that are now slowing commercial projects as well, and on a tightening domestic fiber supply as data centers absorb capacity. Investors should look for any evidence that bookings have bottomed, that the lost anchor customer's volume is being replaced, and that BEAD timing has firmed up. Because this report closes the fiscal year, it is also the natural point for management to frame fiscal 2027, and the credibility of that framework will depend on how conservative it appears after this year's miss.
The data center side is about execution. The $22 million hyperscale order is slated to begin shipping early in fiscal 2027, and the company plans a broader launch of a customer co-developed Innova panel later this calendar year, along with a new fault-managed power line. Confirmation that shipments are on schedule, and any sign of follow-on orders or additional hyperscale engagements, would do more for the stock than a penny of upside.
The market has already leaned toward the optimistic reading. Shares have gained about 15% since the last report while the S&P 500 slipped 2.4%, though that rebound came after a collapse from levels above $52 the prior quarter. At $31.82, the stock sits just below its 200-day average and about 7% under its post-earnings high of $34.21. Sentiment remains mildly bearish but has softened slightly. The central question is whether the broadband business has found a floor; if it has, the data center story gets room to run, and if it has not, the new catalyst may not arrive fast enough to offset the erosion.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Oct-27 | |
| Oct-20 | |
| Sep-24 | |
| Sep-02 | |
| Aug-20 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-28 | |
| Jul-22 | |
| Jul-21 | |
| May-19 | |
| May-18 | |
| May-15 |
